United Arab Emirates Keeps Pace with Thailand and Malaysia as Winter-Sun Tourism Battle Intensifies Over Luxury Hotels, Air Routes and Visitor Spending
Published
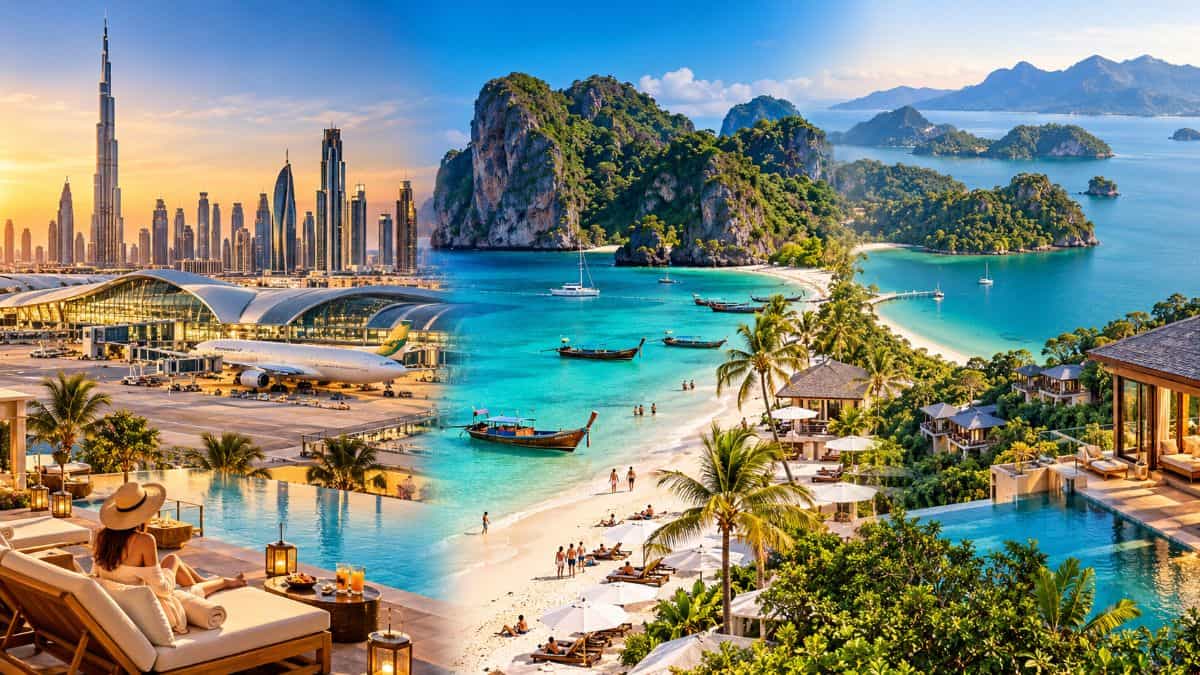
The winter-sun tourism market is entering a decisive period as the United Arab Emirates, Thailand and Malaysia pursue international visitors through contrasting hospitality and aviation strategies. The UAE recorded 32.34 million hotel guests and AED 49.21 billion in hotel revenue in 2025, while Thailand welcomed 32.97 million international visitors. Malaysia recorded 42.2 million international visitor arrivals, alongside RM110.6 billion in travel receipts. These figures reveal different tourism strengths, although their definitions are not directly comparable. The emerging contest centres on whether premium accommodation, longer holidays or affordable family packages deliver stronger economic returns. Hotel rates, visitor spending, overnight stays and airline capacity will help determine which destination converts demand into sustainable growth.
Three Tourism Markets Reveal Different Growth Patterns
The three destinations approach the winter travel market from different commercial positions. The UAE combines international aviation, premium hospitality, shopping and major events. Thailand draws visitors through tropical beaches, wellness retreats, island resorts and cultural experiences, while Malaysia combines urban attractions, island escapes, food tourism and family-oriented holidays.
Their latest full-year figures establish the baseline for this comparison. However, national arrivals, hotel guests and tourism receipts measure different activities, so they should not produce a simplistic league table.
| Tourism Indicator, 2025 | United Arab Emirates | Thailand | Malaysia |
|---|---|---|---|
| Reported visitor measure | 32.34m hotel guests | 32.97m international visitors | 42.2m international visitor arrivals |
| Revenue measure | AED 49.21bn hotel revenue | ฿2.70tn total tourism revenue | RM110.6bn travel receipts |
| International tourism trend | Dubai overnight visitors rose 5% | International arrivals fell 7.23% | International visitor arrivals rose 11.2% |
| Commercial priority | Premium hospitality and higher room yields | Higher-value experiences and revenue recovery | Visitor growth and stronger overnight spending |
The UAE’s figures indicate stronger hotel revenue growth than guest growth. Thailand faces the challenge of rebuilding international demand, while Malaysia is expanding its visitor base and tourism receipts. Nevertheless, these results cover different measures and should be treated as starting points, not proof of which country performs best during winter.
Advertisement
Advertisement
UAE Hotels Turn Visitor Demand into Higher Revenue
The UAE’s hospitality performance provides one of the clearest examples of revenue growth outpacing visitor growth. National hotel establishments recorded 32.34 million guests in 2025, compared with 30.75 million in 2024. Guest nights increased from 104.45 million to more than 110.62 million, while hotel revenue climbed 9.7% to AED 49.21 billion. Occupancy reached 79.3%, demonstrating sustained demand across the country’s accommodation market.
Dubai’s results provide a more detailed view of this performance. The emirate welcomed 19.59 million international overnight visitors in 2025, up from 18.72 million in 2024. Western Europe supplied 4.1 million visitors, accounting for 21% of arrivals, while the Gulf Cooperation Council contributed 2.99 million. Visitors from the Americas totalled 1.4 million, offering further evidence of Dubai’s reach beyond nearby regional markets.
Advertisement
Advertisement
Hotel indicators also strengthened. Dubai’s average daily rate rose 8% to AED 579, while revenue per available room, known as RevPAR, increased 11% to AED 467. Occupancy reached 80.7%, compared with 78.2% in 2024, and occupied room nights climbed 4% to 44.85 million. The average stay remained 3.7 nights, suggesting that higher rates and occupancy both contributed to stronger hotel performance.
Dubai’s accommodation supply reached 154,264 rooms across 827 establishments by December 2025. New openings included Ciel Dubai Marina, Jumeirah Marsa Al Arab and Mandarin Oriental Downtown, Dubai. This expanding inventory gives visitors more choice across luxury, upscale and other hotel categories, although additional supply also requires sustained demand to maintain room yields.
Advertisement
Advertisement
The key question for the coming winter is whether higher rates will continue alongside strong occupancy. Premium pricing can raise revenue without equivalent growth in visitor numbers, but excessive price increases may divert budget-conscious travellers towards competing destinations. The UAE’s broader challenge is to sustain room demand while keeping its offer attractive to families, couples and longer-stay visitors.
Thailand Pursues Spending Rather Than Arrival Totals
Thailand enters the next winter period with a different commercial challenge. The country welcomed 32.97 million international visitors in 2025, down 7.23% from the previous year. Total tourism revenue reached 2.70 trillion baht, declining 1.26%, while receipts from international visitors fell 4.71% to 1.54 trillion baht. Domestic tourism partly offset the weakness, generating 1.17 trillion baht from 202.37 million trips.
The difference between the decline in arrivals and the sharper fall in international receipts warrants closer investigation. Changes in source-market composition, length of stay and expenditure may influence the results, but annual totals alone cannot establish which factor had the greatest effect. Destination-level hotel rates and spending data will be necessary to determine whether higher-value travellers are compensating for weaker visitor volumes.
Thailand’s long-haul markets provide an important opportunity. The Tourism Authority of Thailand reported 10.8 million long-haul visitors in 2025, a record, with the United Kingdom and United States each exceeding one million arrivals. These travellers can support extended holidays across Bangkok, Phuket, Krabi, Chiang Mai and other destinations, although their individual spending patterns vary considerably.
Advertisement
Advertisement
The country’s 2026 strategy, branded the Amazing 5 Economy, places greater emphasis on value creation. Its five areas cover wellness and medical tourism, specialist cultural and lifestyle segments, the night-time economy, circular-economy principles and digital travel platforms. The approach seeks to encourage meaningful experiences, longer stays and wider economic benefits rather than relying exclusively on arrival growth.
For travellers, Thailand’s breadth remains a major advantage. Visitors can combine city hotels, island resorts, wellness experiences and cultural excursions within one itinerary. However, the financial comparison must include transfers between destinations, domestic flights, seasonal accommodation rates and activity costs, not simply the nightly price of a beach resort.
Malaysia Builds Momentum Ahead of Visit Malaysia 2026
Malaysia enters the comparison with strong visitor growth and an expanding international tourism profile. Tourism Malaysia reported 42.2 million international visitor arrivals in 2025, approximately 11.2% above the 38 million recorded in 2024. Bank Negara Malaysia separately reported 26.6 million tourist arrivals and RM110.6 billion in travel receipts, compared with 25 million tourists and RM95.3 billion in receipts during 2024.
The distinction between these figures is essential. Malaysia’s broader visitor total includes tourists and excursionists, while the narrower tourist category focuses on overnight visitors. The two measures capture different types of demand, particularly because Malaysia shares land borders with Singapore and Thailand. Cross-border journeys can generate substantial arrivals without producing the accommodation revenue associated with extended holidays.
The country’s tourism proposition extends well beyond Kuala Lumpur. Langkawi offers beach resorts and island excursions, Penang combines heritage tourism with food experiences, and Sabah and Sarawak provide rainforest, wildlife and nature-based travel. This geographical variety could encourage visitors to extend their holidays, provided transport connections and accommodation availability support multi-destination itineraries.
Malaysia’s aviation sector also offers useful evidence of the opportunity. The Malaysian Aviation Commission forecast passenger traffic of 105.8 million to 112.9 million in 2025, compared with an estimated 97.6 million in 2024. These were forecasts rather than confirmed final results, but they indicated expectations of rising demand and additional airline capacity ahead of Visit Malaysia 2026.
Advertisement
Advertisement
Tourism Malaysia has also pursued partnerships with hospitality operators and international promotional campaigns. Such initiatives can help convert general awareness into bookings, but their success ultimately depends on actual visitor spending, room occupancy and length of stay. The coming winter will therefore provide an important opportunity to assess whether increased arrivals translate into stronger economic returns.
Hotel Prices Reveal Where Revenue Is Growing
Hotel performance offers a more commercially meaningful comparison than arrivals alone. Average daily rate measures the average price paid for an occupied room, while RevPAR divides room revenue by available rooms. Together with occupancy, these indicators help explain whether hotels are benefiting from stronger demand, higher prices or both.
| Hotel Performance Measure | What It Reveals | Why Travellers Should Care |
|---|---|---|
| Average daily rate (ADR) | Average revenue per occupied room | Indicates room-price trends |
| Occupancy | Share of available rooms occupied | Helps assess demand pressure |
| RevPAR | Room revenue per available room | Combines price and occupancy |
| Average length of stay | Typical duration of a visit | Affects total accommodation expenditure |
| Available room inventory | Scale of accommodation supply | Helps explain competition and availability |
Dubai’s 2025 figures provide the clearest verified benchmark in this comparison. Its AED 579 average daily rate and AED 467 RevPAR accompanied occupancy of 80.7%. Comparable figures for Bangkok, Phuket, Kuala Lumpur and Langkawi should be collected from consistent reporting periods before ranking the destinations.
That comparison should also distinguish luxury hotels from mid-market and budget accommodation. A luxury resort’s rates may rise substantially during peak winter weeks, while economy hotels experience a different pricing pattern. National averages can conceal these differences, so a reliable investigation needs both destination-level and hotel-category data.
Hotel revenue must also remain separate from total tourism receipts. Accommodation revenue excludes many visitor purchases outside hotels, while tourism receipts can include transport, dining, shopping and other services. Treating the two as interchangeable would distort the comparison and potentially overstate the economic importance of accommodation alone.
Long-Haul Flights Could Shift the Competitive Balance
Direct air connectivity can influence destination choice by reducing journey times and eliminating connections. Additional frequencies can also give travellers greater flexibility, while expanded seat capacity may improve fare competition when airlines have sufficient demand. However, a new route does not automatically produce profitable traffic or higher visitor spending.
Advertisement
Advertisement
Dubai benefits from its role as a major international aviation hub, connecting European, American, African and Asian markets. Thailand’s tourism authorities are prioritising long-haul demand and working with aviation partners to strengthen year-round access. Malaysia, meanwhile, is positioning its airports and tourism products to support the Visit Malaysia campaign and wider international demand.
The most useful airline comparison would examine direct flights and weekly seat capacity from the same departure markets. London, Frankfurt and selected North American gateways could provide a consistent starting point, subject to route availability. Researchers should then compare flight duration, fare ranges, seasonal schedules and access to resort destinations.
| Connectivity Indicator | Research Question |
|---|---|
| Direct routes | Which destinations offer non-stop access from the same departure cities? |
| Weekly seat capacity | Which markets are adding the most available seats? |
| Seasonal frequencies | Does capacity increase during the winter peak? |
| Airfares | How much does a return journey cost for comparable dates? |
| Airport access | How easily can visitors reach beaches, hotels and secondary destinations? |
Airport passenger totals should support this analysis, not replace airline schedule data. A busy airport may serve connecting passengers, domestic travellers or residents rather than international holidaymakers. The research must distinguish these groups wherever published statistics allow.
Luxury, Families or Packages: Which Segment Wins?
The contest is not simply between expensive and affordable holidays. Each segment produces a different mix of accommodation, transport, dining, retail and activity expenditure. The strongest economic result may come from visitors who stay longer and spend across several local businesses, rather than those who pay the highest nightly rate.
The UAE is well placed to attract luxury shoppers, premium hotel guests and travellers combining business with leisure. Yet Dubai’s average stay of 3.7 nights means total expenditure per trip deserves scrutiny alongside spending per day. A short luxury visit may generate high daily receipts, while a longer holiday can accumulate greater total spending.
Thailand’s resort economy provides another model. Families and couples may spend several nights in Phuket or Krabi, with additional expenditure on excursions, restaurants and domestic transfers. Wellness visitors can also support specialist services, although the actual financial contribution of these groups needs confirmation through segment-level research.
Advertisement
Advertisement
Malaysia’s value-led proposition may appeal to families seeking varied attractions, competitive accommodation and longer itineraries. Its diverse geography can encourage visitors to combine urban stays, islands and cultural destinations. However, affordability should be established through comparable package prices rather than broad assumptions about the country’s overall cost level.
The investigation should therefore compare spending per trip, spending per night and total holiday cost. These measures answer different questions. They reveal how much destinations earn, how efficiently visitor nights generate receipts and how much travellers must budget.
Winter Seasonality Changes the Value Equation
Annual figures cannot establish which country is winning the November-to-March market. Winter demand varies by source market, school holidays, weather, festivals and airline schedules. The next stage must compare identical months year on year, separating seasonal strength from broader annual growth.
The UAE’s cooler months support outdoor dining, desert excursions, beach visits and major events. Thailand’s peak-season patterns differ by region, with the Andaman coast and Gulf islands experiencing different weather conditions. Malaysia also has regional variations, meaning visitors should check conditions for their intended destination rather than assume every beach offers identical weather throughout winter.
A robust seasonal comparison should examine monthly arrivals, hotel occupancy, room rates and tourism receipts. Researchers should also record major events, new airline routes and changes in accommodation capacity that may explain unusual results. This will help identify whether growth reflects stronger underlying demand or a temporary increase in prices.
| Seasonal Research Measure | Comparison Required | Editorial Value |
|---|---|---|
| November–March arrivals | Same months in the previous year | Identifies winter demand growth |
| Monthly hotel occupancy | Destination and hotel category | Reveals peak-period pressure |
| ADR and RevPAR | Equivalent months and currencies | Tracks room-price performance |
| Average stay | Overnight visitors where available | Indicates trip duration |
| Airline seat capacity | Same routes and seasonal weeks | Measures changes in access |
| Visitor receipts | Consistent national definitions | Assesses economic value |
Measure Spending Without Misleading Readers
Visitor spending is central to the investigation, but national tourism receipts require careful interpretation. Dividing receipts by overnight tourist arrivals can provide an indicative average, while dividing receipts by tourist-nights can help estimate expenditure per night. Neither measure represents the actual spending of every visitor.
Advertisement
Advertisement
Exchange rates also matter. Baht, dirhams and ringgit should not be compared using nominal totals alone, because the currencies have different values and the countries measure tourism receipts differently. A cross-country comparison should present local-currency figures first and use a consistent exchange-rate date if converting them into a common currency.
The research should also account for inflation when comparing several years. A nominal increase in hotel revenue may partly reflect higher prices rather than additional real demand. Where reliable inflation-adjusted data are unavailable, the article should state that limitation rather than present nominal growth as proof of improved economic performance.
For businesses, the distinction is commercially significant. Higher receipts can support hotels, airlines, restaurants and tour operators, but the distribution of spending matters. A destination that attracts longer stays and spreads expenditure across smaller businesses may deliver different local benefits from one concentrated around premium resorts and major retail centres.
Travel Planning Tips for the Winter Season
Travellers can use the comparison to choose a destination according to their priorities rather than headline arrival figures. Before booking, compare the full itinerary and the conditions at the particular destination.
- For premium city breaks: Compare Dubai hotel rates, airport transfers and attraction costs before committing to peak-season dates.
- For extended beach holidays: Check Thailand’s regional weather patterns and include domestic transfers when comparing resort prices.
- For value-led family trips: Compare Malaysia’s accommodation, transport and attraction costs as a combined package.
- For long-haul journeys: Check direct-flight availability, baggage allowances, arrival times and onward airport transfers.
- For winter savings: Compare flexible dates and total trip costs rather than relying on the lowest advertised room rate.
- For multi-stop itineraries: Allow sufficient time for domestic flights, ferries and transfers between islands or regions.
- For reliable budgeting: Check official entry requirements, travel advisories and local transport arrangements before departure.
What the Next Winter Season Must Prove
The latest figures reveal three distinct tourism strategies, but they do not yet identify a definitive winner. The UAE has demonstrated strong hotel revenue growth and rising room yields, Thailand is pursuing higher-value experiences amid weaker international arrivals, and Malaysia is expanding visitor numbers alongside higher travel receipts. The decisive test will be whether these trends continue during the same winter months. A consistent comparison of overnight arrivals, accommodation prices, length of stay, airline capacity and visitor expenditure will provide a more credible assessment. For travellers and tourism businesses, the greatest insight will come from identifying which destinations deliver the best combination of value, experience and measurable economic return.
Advertisement
