Dubai Outpaces Oman and Egypt in Visitor Spending Growth as Winter Sun Destinations Compete for International Travellers
Published
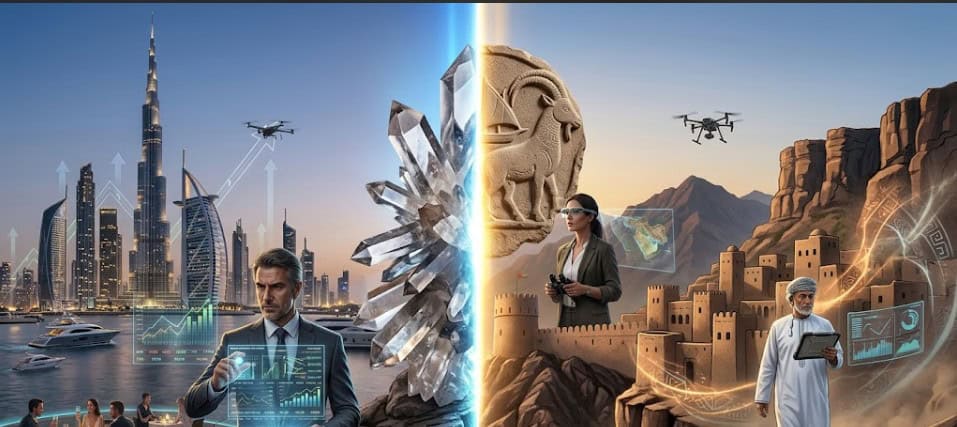
Dubai visitor spending growth has reached unprecedented heights in 2026, solidifying the emirate’s position as the dominant winter sun destination across the Middle East and North Africa. As international travellers seek warm weather, high-end hospitality, and diverse cultural experiences, Dubai continues to outperform rival regional destinations such as Oman and Egypt in per-capita expenditure, hotel revenue metrics, and total economic impact. Understanding this shift is vital for global aviation leaders, hospitality investors, and tourism boards navigating the competitive regional landscape during the high-demand winter season.
Background of the Regional Winter Sun Tourism Market
The Middle East and North Africa (MENA) region has long served as a primary global hub for international tourists seeking winter sun escapes between October and April. Historically, nations such as Egypt, Oman, and the United Arab Emirates have competed vigorously for long-haul visitors from Europe, North America, and Central Asia seeking warm climates, heritage sites, and luxury beach resorts.
Over the past decade, national economic transformation strategies—including the UAE’s Economic Vision, Oman Vision 2040, and Egypt’s Sustainable Tourism Strategy—have funnelled tens of billions of dollars into transportation infrastructure, airport expansions, port developments, and resort construction. However, while visitor volume trends have fluctuated due to macroeconomic conditions, dynamic regional geopolitics, and currency valuations, the primary metric defining destination success has shifted from pure arrival counts to gross yield, average daily rates (ADR), and total per-tourist expenditure.
In this evolving ecosystem, Dubai visitor spending growth has outpaced regional competitors, creating a widening economic divergence between the United Arab Emirates, Oman, and Egypt during peak winter trading periods.
Advertisement
Advertisement
┌─────────────────────────────────────────────────────────────────────────┐
│                      MENA WINTER SUN TOURISM METRICS                    │
├─────────────────────────┬───────────────────┬───────────────────────────┤
│ Destination             │ Primary Focus     │ Key Economic Metric       │
├─────────────────────────┼───────────────────┼───────────────────────────┤
│ Dubai (UAE)             │ Luxury & Yield    │ High ADR & Total Yield    │
│ Sultanate of Oman       │ Eco & Heritage    │ Mid-High Length of Stay   │
│ Arab Republic of Egypt  │ Volume & Culture  │ High Arrival Volumes      │
└─────────────────────────┴───────────────────┴───────────────────────────┘
Official Performance Data and Statistical Breakdown
Data published by the Department of Economy and Tourism (DET) in Dubai, alongside comparative reports from national statistical agencies, illustrates the structural advantage Dubai maintains in capturing high-value international spending.
Dubai Hospitality and Revenue Performance
Official performance indicators published by the Dubai Department of Economy and Tourism (DET) demonstrate robust resilience and sustained financial yield through August 2026:
Advertisement
Advertisement
- International Overnight Visitors: Dubai welcomed 6.97 million overnight international visitors between January and August 2026, building upon the baseline established by the 19.59 million visitors recorded across 2025.
- August Peak Volume: In August 2026 alone, Dubai welcomed approximately 869,000 international overnight visitors, marking the highest monthly volume recorded since February 2026.
- Occupied Room Nights: Hotels across Dubai recorded 21.61 million occupied room nights between January and August 2026.
- Average Daily Rate (ADR): Yield figures highlight strong pricing power, with Dubai’s hotel Average Daily Rate climbing to USD $211.17 in peak periods, representing a 13.5% year-on-year increase.
- Revenue Per Available Room (RevPAR): RevPAR reached USD $182.02, reflecting a 16.0% gain compared to equivalent prior-year cycles.
- Hotel Inventory: The city’s total accommodation inventory reached nearly 149,000 active rooms across 647 properties by the end of August 2026.
┌─────────────────────────────────────────────────────────────────────────┐
│                   DUBAI TOURISM PERFORMANCE (JAN-AUG 2026)               │
├───────────────────────────────────────────┬─────────────────────────────┤
│ Metric                                    │ Official Figure             │
├───────────────────────────────────────────┼─────────────────────────────┤
│ International Overnight Visitors          │ 6.97 Million                │
│ August Monthly Visitor Arrivals           │ 869,000                     │
│ Occupied Room Nights                      │ 21.61 Million               │
│ Hotel Room Inventory                      │ ~149,000 Rooms (647 Hotels) │
│ Average Daily Rate (ADR Peak)             │ USD $211.17                 │
│ Revenue Per Available Room (RevPAR Peak)  │ USD $182.02                 │
└───────────────────────────────────────────┴─────────────────────────────┘
Comparative Analysis: Oman and Egypt
While Oman and Egypt remain highly attractive winter sun destinations, their economic capture per visitor reflects distinct structural models:
- Sultanate of Oman: According to the National Centre for Statistics and Information (NCSI), Oman continues to capture steady visitor volumes focused on eco-tourism, cultural heritage, and adventure travel. While length of stay remains strong, total overall yield per visitor trails Dubai due to a smaller footprint of ultra-luxury hotel inventory and luxury retail infrastructure.
- Arab Republic of Egypt: Data from the Ministry of Tourism and Antiquities reveals strong top-line visitor arrivals driven by heritage assets in Luxor and Aswan alongside coastal resorts in Sharm El Sheikh and Hurghada. However, lower overall Average Daily Rates and currency adjustments mean total visitor expenditure growth tracks behind Dubai’s premium luxury baseline.
Key Drivers Behind Dubai’s Yield Dominance
Integrated Air Connectivity and Fleet Capacity
A cornerstone of Dubai’s ability to drive sustained international visitor spending is its aviation infrastructure. Operating out of Dubai International Airport (DXB) and Al Maktoum International Airport (DWC), flag carrier Emirates and low-cost operator flydubai provide direct connectivity to more than 200 cities worldwide. This network enables seamless long-haul transit and high-yield point-to-point traffic, whereas competitor markets rely more heavily on charter flights and third-party carrier capacity.
Diversified Source Market Strategy
Dubai’s Department of Economy and Tourism maintains a balanced geographic sourcing strategy, protecting the emirate from economic headwinds in any single originating market. Official distribution data highlights a balanced market share across:
- Western Europe: Continues to represent the largest regional source market, contributing high-spending leisure tourists during the European winter.
- GCC Neighboring States: Accounting for over 15% of total arrivals, driving frequent, high-spending short-break stays.
- South Asia & Eastern Europe: Providing sustained, high-volume year-round arrivals.
- The Americas and Africa: Representing fast-growing long-haul segments with high length-of-stay averages.
┌─────────────────────────────────────────────────────────────────────────┐
│                    DUBAI VISITOR SOURCE REGION BREAKDOWN                │
├───────────────────────────────┬─────────────────────────────────────────┤
│ Source Region                 │ Share of Total Arrivals (%)             │
├───────────────────────────────┼─────────────────────────────────────────┤
│ Western Europe                │ Top Contributing Region                 │
│ GCC Countries                 │ ~15.7%                                  │
│ South Asia                    │ ~14.8%                                  │
│ CIS & Eastern Europe          │ Significant Market Share                │
│ Americas & Africa             │ Emerging High-Growth Markets            │
└───────────────────────────────┴─────────────────────────────────────────┘
Retail, Gastronomy, and Entertainment Infrastructure
Unlike regional competitors focused primarily on sun-and-sand or historical sites, Dubai has monetised every facet of the tourist journey. The expansion of high-end dining, Michelin-starred establishments, global entertainment venues, and annual shopping events ensures that per-capita daily spending extends far beyond accommodation costs.
Policy Implications and Economic Impact
The divergence in visitor spending growth carries significant broader economic implications across the MENA region:
- GDP Contribution: Tourism directly accounts for approximately 11% to 12% of Dubai’s Gross Domestic Product (GDP), serving as a central pillar of non-oil economic diversification.
- Foreign Direct Investment (FDI): High room occupancy rates (averaging 66% through August 2026, peaking higher in winter) continue to attract international capital into luxury hospitality, mixed-use commercial developments, and leisure infrastructure.
- Fiscal Revenues and Employment: High per-capita spending supports extensive tax revenues (such as VAT and tourism dirham fees) and direct employment across aviation, retail, logistics, and service sectors.
In contrast, while Egypt and Oman benefit from tourism employment, lower yield per visitor requires higher total physical volumes to achieve equivalent national fiscal benefits, putting additional pressure on local infrastructure and natural environmental assets.
Advertisement
Advertisement
Future Outlook for MENA Winter Sun Tourism
Looking ahead through the remainder of 2026 and into 2027, the competition for winter sun international travellers will intensify:
- Dubai’s Strategic Horizon: The Dubai Economic Agenda (D33) aims to consolidate the city’s position among the top three global urban destinations for business and tourism, backed by the ongoing mega-expansion of Al Maktoum International Airport (DWC).
- Oman’s Targeted Growth: Oman is investing heavily in sustainable tourism clusters, green luxury resorts, and cultural tourism projects designed to raise average daily spend without diluting its distinct natural heritage.
- Egypt’s Infrastructure Push: Egypt continues to leverage new transportation infrastructure, renovated heritage museums, and resort zone expansions to convert high arrival volumes into longer stays and greater overall economic returns.
While all three destinations remain essential pillars of Middle Eastern tourism, Dubai’s unique blend of high aviation capacity, luxury retail, and pricing power positions it to maintain its lead in Dubai visitor spending growth across upcoming winter seasons.
Advertisement
