
What Foreign Operators Need To Know About The Upcoming Maldives 2026 Regulations For International Travel
Published
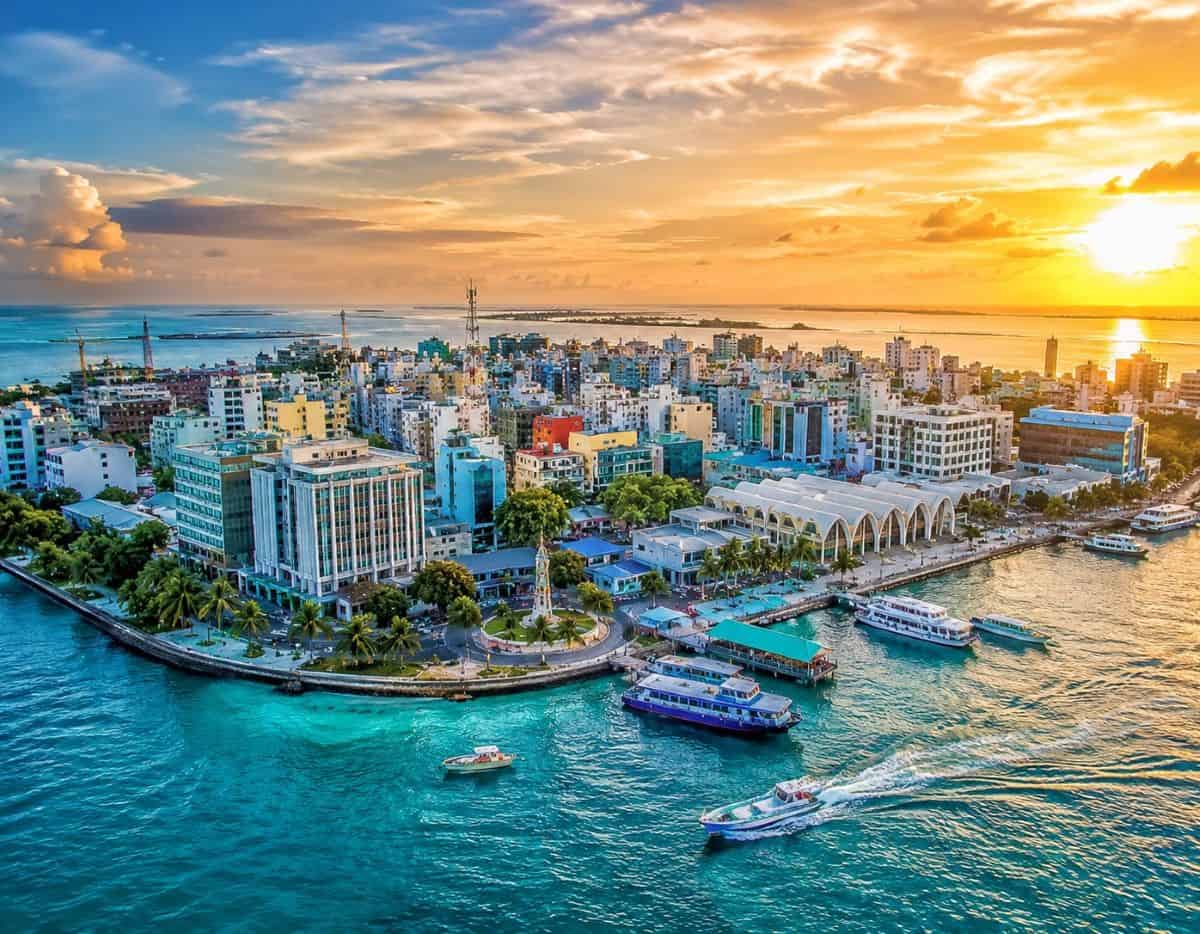
Image generated with Ai
There is an appeal to thinking about vacationing in the Maldives and slowly wandering through the waters and feeling sand between your toes. Scheduling this vacation is easy, but behind the perfect postcard views, there is a constant, effortless earthquake changing the way these vacations are packaged and sold. Beginning October 1, 2026, travel and tour package selling operators will be affected by new regulations and taxes. When you see a travel package and the price you have to pay says it is much more than what is advertised, this is becoming a reality and only continue even more so. Brexit, the environmental levy, and the new regulations will increase the difficulties to get to the islands. Understanding what foreign travel operators need to know about the Maldives GST 2026 will not enable them to understand the new changes in tax law. It will help them maintain the spirit of traveling and preserve the confidence of their clients. Without a doubt these platforms will need to stay in business to help travel dreams materialize.
Comprehensive Insights on What Foreign Tour Operators Need to Know Regarding Maldives GST 2026 Adjustments
Advertisement
Advertisement
Therefore, significant fiscal updates are altering how overseas merchants distribute tropical vacation packages worldwide. Beginning on 1 October 2026, statutory agencies across the Maldives will formally integrate cross-border commerce entities into the nation’s internal revenue mechanisms. Additionally, global distributors, foreign agents, and digital booking gateways must adjust to these modified rules. This evolving landscape underscores exactly what foreign tour operators need to know regarding Maldives GST 2026 implementation standards. By enforcing the destination principle, fiscal responsibilities will depend strictly on where vacation activities occur. Consequently, every commercial vendor promoting holiday accommodations across the archipelago must re-evaluate its exposure to local tax authorities.
Moreover, this statutory shift alters financial obligations across international travel supply networks. Tourists traveling to various island resorts across the Maldives will encounter revised retail prices on packaged itineraries. Because foreign commercial entities must account for local tax compliance, overall consumer expenses will probably increase globally. Furthermore, travelers securing boutique luxury stays or local transfers might observe increased upfront charges upon booking. As a result, international tourists must prepare for stricter booking terms, updated invoice calculations, and potential administrative adjustments when arranging tropical holidays after the enforcement date.
Advertisement
Advertisement
Strategic Decisions Surrounding Direct Resort Contracting Versus Establishing Local Destination Partnerships
Advertisement
Advertisement
Global travel merchants currently face critical operational choices regarding their ongoing commercial practices throughout the Maldives. Establishing direct supplier agreements with isolated island properties requires handling significant logistical hurdles independently. For example, arranging transfers from Velana International Airport to distant private atolls demands constant ground coordination. Foreign companies choosing direct management must handle property contracts, supplier payments, customer relations, and regulatory compliance simultaneously. Thus, smaller overseas intermediaries may find direct administrative workflows increasingly difficult to sustain under the modernized tax regulations.
On the other hand, coordinating with authorized onshore representatives provides a streamlined commercial workflow. Established local partners organize complex logistics by managing resort inventory, regional flight transfers, and guest reception services through one central contact point. However, international distributors must understand that engaging ground representatives does not provide automatic tax exemption under the Maldives legal framework. Instead, onshore partnerships primarily reduce daily operational friction while navigating transit arrangements involving speedboats, seaplanes, and regional air terminals.
Clarifying Tax Compliance Realities and Evaluating Global Effects for Future Island Visitors
Advertisement
Advertisement
The statutory framework explicitly mandates that offshore vendors maintain compliance regardless of their chosen operational arrangements. Operating through locally registered ground representatives simplifies daily coordination, yet it does not eliminate statutory tax responsibilities. The underlying tax obligations persist based on service consumption within the Maldives, making accurate accounting mandatory for every commercial booking. Therefore, global travel suppliers must consult qualified advisors to align their booking systems with official directives issued by national revenue authorities.
Ultimately, these tax modifications will affect the broader global hospitality market, shaping how consumers plan visits to the Maldives. As foreign distributors update their pricing systems, travelers worldwide will feel the practical effects of destination-based taxation. Managing unexpected flight delays, tropical weather shifts, or rapid schedule adjustments across remote island chains will require reliable ground support. Consequently, stricter tax enforcement and complex island logistics will transform how overseas travel suppliers design, market, and deliver holiday packages moving forward.
Advertisement
Advertisement
Financial Quantification of Stacking Taxes and Cumulative Cost Breakdown for Overseas Bookings
Therefore, evaluating the exact mathematical structure behind island room quotes reveals how drastically cumulative levies impact consumer billing. When foreign travel distributors formulate retail pricing for accommodation packages, they must account for a 17% Tourism Goods and Services Tax (T-GST), a mandatory 10% Service Charge, and a flat Green Tax of USD 12 per person for each night of stay. Combined, these mandatory additions generate an effective baseline markup of 27% on top of room rates, before accounting for per-head environmental assessments.
For instance, when an overseas agent reserves a room listed at USD 500 per night, the statutory 17% T-GST adds USD 85 per day, while the 10% Service Charge contributes another USD 50 daily. Furthermore, a 7-night stay for a party of two incurs an additional USD 168 in flat Green Tax charges. Consequently, a baseline accommodation quote of USD 3,500 increases to a final total of USD 4,203. Maintaining complete financial clarity across these stacked fee structures remains essential for international sellers attempting to preserve profit margins while presenting transparent quotes to clients.
Revenue Collection Escalation and Fiscal Benchmarks from National Tax Authorities
Furthermore, statutory records illustrate a rapid expansion in local revenue generation driven by modernized compliance monitoring. Official performance metrics from national tax agencies confirm that Green Tax collections reached USD 27.31 million during January and February 2026 alone. This performance reflects a 63.7% year-over-year increase compared to the USD 16.68 million recorded during the corresponding period in 2025. This substantial growth in tax collection coincided with the arrival of 474,920 international visitors during those same two opening months.
Advertisement
Advertisement
These financial benchmarks highlight how local revenue authorities, including the Maldives Inland Revenue Authority, are actively monitoring cross-border monetary flows. Tax administrators closely track fiscal contributions generated by roughly 6,000 daily tourist arrivals entering through major aviation hubs. Overseas sellers must recognize that local enforcement mechanisms are growing increasingly sophisticated. As a result, cross-border commercial transactions are scrutinized to ensure full destination tax capture on all sold itineraries.
Aviation Logistics and Multi-Modal Transit Cost Realities Across Remote Atolls
Additionally, physical transit across scattered island geography introduces significant operational complexity and additional tax liabilities. Incoming travelers arriving at Velana International Airport rely on complex transport networks comprising over 60 active seaplanes, regional turboprop flights, and high-speed water vessels to access resorts scattered across 26 distinct geographic atolls. Because localized transit services incur their own statutory 17% T-GST charges, inter-island transfer fees carry noticeable tax add-ons that foreign distributors must incorporate into overall package pricing.
For example, when an overseas booking agent arranges a USD 450 round-trip seaplane transfer to properties located in Baa Atoll or South Ari Atoll, the transaction triggers an extra USD 76.50 in tax per passenger. Managing these localized transit levies complicates non-resident accounting procedures, particularly when handling multi-leg itineraries involving separate aviation providers. Foreign intermediaries must carefully calculate these stacked transport charges to avoid unexpected margin erosion on pre-packaged transfers.
Digital Systems Compliance, API Integration, and Electronic Invoicing Deadlines
Advertisement
Advertisement
Moreover, global travel distributors and online booking engines face notable technical compliance requirements leading up to official enforcement dates. The statutory transition scheduled for 1 October 2026 requires overseas reservation platforms to integrate their software architecture directly with online tax management portals. Furthermore, foreign booking engines processing transactions in foreign currencies under USD pricing structures must update their checkout systems to calculate, itemize, and process destination levies automatically.
This technical mandate requires global digital distributors to modify their core billing infrastructure and Application Programming Interfaces (APIs). Reservation systems must accurately separate base rates from statutory taxes at the point of sale, ensuring real-time reporting to onshore revenue databases. Software engineers must reconfigure global booking portals to reflect regional tax rules seamlessly, preventing billing discrepancies and technical non-compliance when selling island accommodations online.
Foreign Exchange Fluctuations, Cross-Border Remittance, and Banking Gateways
Equally important are the financial and monetary mechanics involved in remitting client payments across international borders. The local currency operates under an official peg fixed at 15.42 Maldivian Rufiyaa per 1 USD. However, international wire transfers and cross-border commercial banking channels typically impose transaction processing fees ranging between 2% and 4%. Foreign agencies handling large-volume reservations must navigate these banking surcharges while remitting funds to onshore accounts.
Navigating these banking channels presents distinct cash-flow challenges for non-resident tour operators. Converting foreign currencies, absorbing bank processing surcharges, and accounting for non-resident tax withholdings can erode thin profit margins if not structured correctly. Consequently, international travel firms must establish efficient financial clearing mechanisms and clear contractual terms with local banking partners to mitigate cross-border transfer friction.
Advertisement
Advertisement
Global Market Price Elasticity and Competitive Shifts in Tropical Luxury Tourism
Finally, rising destination costs alter international traveler behavior and modify competitive dynamics across global luxury markets. Inbound tourism data indicates that approximately 30% of all international visitors arrive via major Middle Eastern aviation hubs. However, cumulative destination taxes, service charges, and environmental fees increase baseline costs by 29% to 39% across budget, mid-range, and ultra-luxury accommodation tiers.
These cost increases test consumer price sensitivity across international source markets. As total package costs rise, overseas travel advisors must manage prospective clients who actively evaluate alternative tropical destinations across Southeast Asia or the Caribbean that offer lower consumption taxes. Consequently, foreign tour operators must refine their sales strategies, highlight destination value, and deliver transparent pricing to maintain client trust in an increasingly cost-conscious global travel market.
Beyond the Horizon: Forecasting Trends in Tropical Escape Getaways
While the money required to travel diminishes neither the happiness nor your memories, watching the sunrise over the Emerald ocean, walking across the Maldives’s white sandy beach, and saving memories that you will hold dear and have plenty of still brings an immense joy. While travel in the 21st century may require much more planning, the desire to travel and relax in paradise is stronger than ever. True hospitality will triumph in the end. Travel planning requires more than just calculating numbers. It is defending vacation dreams of the saving traveler that is important to us. Although travel will undergo the inevitable process of change, so will the beauty that is there for traveler’s enjoyment.
Advertisement
