
Malaysia Emerges Alongside Thailand And Asia’s Leading Tourism Markets As Airport Hubs Redraw Travel Routes
Published
Asia’s aviation network is entering a new phase as mega-hubs and direct flights expand simultaneously. The latest connectivity data shows Asia-Pacific air connectivity rose 10% in 2025, while international city pairs increased 10%. Major gateways continue strengthening their transfer networks, yet low-cost carriers are opening more direct links between secondary cities and tourism destinations. Kuala Lumpur now ranks fourth globally among Megahubs, with 154 destinations and 35,749 potential connections. Meanwhile, Southeast Asia’s low-cost carriers account for 51% of seats. The shift matters for travellers because direct services can shorten journeys, while major hubs still provide broader long-haul choices. Asia’s tourism map is therefore becoming more distributed, not simply more concentrated.
The New Shape of Asian Air Travel
Asia’s aviation expansion is no longer following one clear model. Traditional hubs continue to attract airlines, transfer passengers and international capacity. At the same time, point-to-point networks are giving travellers more ways to bypass established gateways.
ACI Asia-Pacific and Middle East recorded 10% growth in Asia-Pacific air connectivity during 2025. Across the region, 74% of the 315 airports covered by its index recorded positive connectivity growth. International city pairs also increased by 10%, showing that network expansion is reaching beyond the largest airports.
The distinction matters because connectivity does not simply mean passenger volume. A hub may carry enormous numbers of connecting travellers without those passengers spending money in the host destination. Conversely, a smaller airport can have a strong tourism effect when direct services bring visitors who stay locally.
Advertisement
Advertisement
That creates a more useful way to understand Asia’s aviation transformation. Hub strength measures network reach, while direct connectivity can measure destination accessibility.
Advertisement
Advertisement
Kuala Lumpur Shows The Hybrid Model
Kuala Lumpur offers perhaps the clearest example of the two systems developing together. OAG’s 2026 Megahubs analysis places Kuala Lumpur International Airport fourth globally and first among Asian Megahubs.
The airport serves 154 destinations, with 35,749 potential connections and about 40 million seats in the September 2025-August 2026 measurement period. AirAsia holds a 34% share of flights, giving the airport an unusually strong combination of full-service and low-cost connectivity.
Kuala Lumpur also leads OAG’s global Low-Cost Megahubs ranking. It records almost 15,000 possible low-cost connections across 154 destinations. That makes it more than a conventional transfer airport.
It is simultaneously a transfer platform and a launchpad for direct leisure travel. For travellers, this means Kuala Lumpur can remain useful when a direct flight exists, while still providing an alternative when a journey requires a connection.
| Selected Asian Airport | 2026 Global Megahub Rank | Destinations | Key Connectivity Feature |
|---|---|---|---|
| Kuala Lumpur | 4 | 154 | Strong FSC and LCC mix |
| Seoul Incheon | 6 | 198 | High LCC and international reach |
| Tokyo Haneda | 8 | — | Dense regional and long-haul network |
| Singapore Changi | 11 | 167 | Major regional transfer gateway |
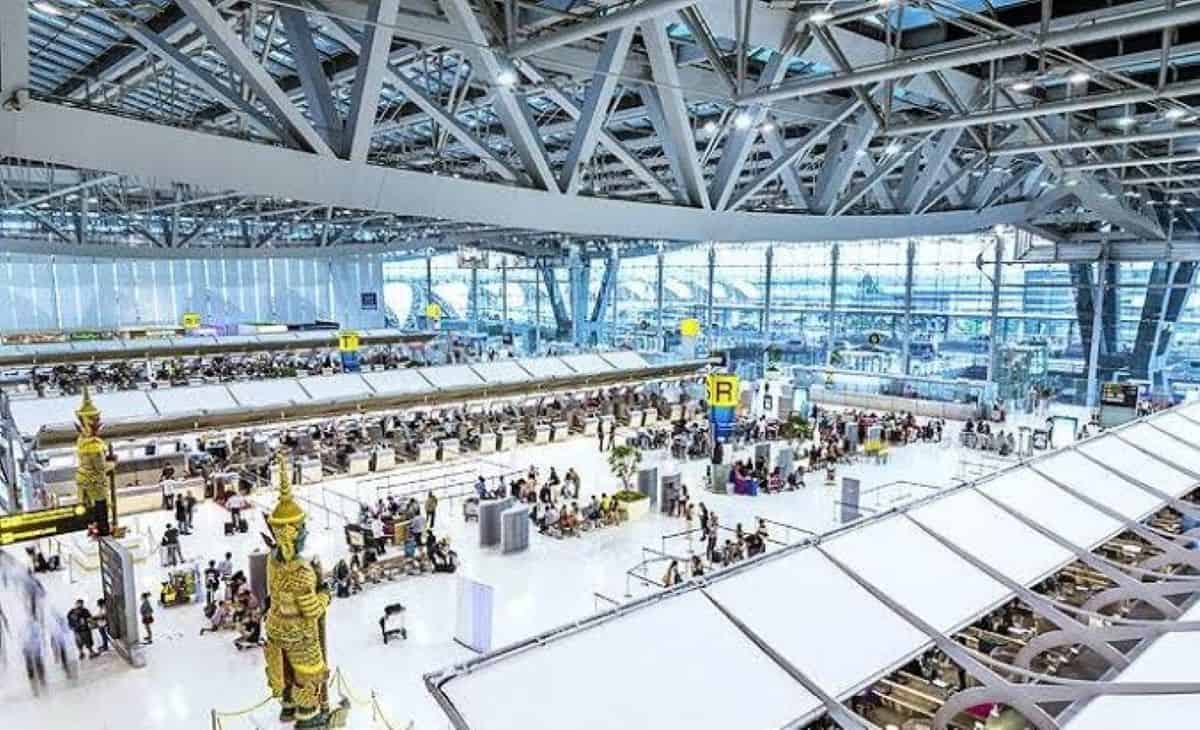
| Bangkok Suvarnabhumi | 12 | — | Strong tourism and regional connectivity |
| Shanghai Pudong | 14 | — | Rapid connectivity improvement |
| Delhi | 28 | 178 | Strong domestic feed and LCC growth |
| Jakarta | 29 | — | Large Southeast Asian catchment |
OAG ranks 17 Asia-Pacific airports among the global Top 50 Megahubs. Eight are inside the global Top 20, illustrating how deeply Asia’s aviation system remains anchored in major gateways.
Advertisement
Advertisement
Direct Flights Are Spreading Tourism
The more subtle change is occurring beneath the headline airport rankings. Direct international services are increasingly connecting secondary cities, island destinations and regional tourism centres.
ACI’s 2025 connectivity index identifies Phu Quoc, Surabaya, Da Nang, Hanoi and Ho Chi Minh City among airports showing notable connectivity improvements in their respective passenger categories. The organisation specifically links these improvements with route expansion, tourism recovery and regional development.
This creates a different tourism dynamic. A traveller visiting Da Nang does not necessarily need to enter Vietnam through a traditional national gateway and then transfer domestically. A direct international service can turn the destination airport itself into the tourism gateway.
That difference can influence hotel demand, airport transfers, local transport and spending patterns. It can also encourage tourism businesses outside capital cities to develop international markets.
The effect is particularly visible across Southeast Asia, where LCC networks have expanded rapidly. OAG reports that low-cost carriers now represent 51% of all seats across Southeast Asia, compared with a global average of 34%.
Advertisement
Advertisement
Why Mega-Hubs Still Matter
The rise of direct flights does not make mega-hubs obsolete. Instead, their role is becoming more specialised.
Long-haul travellers still require efficient transfer points where airlines can consolidate demand across numerous origins and destinations. Major hubs also allow carriers to serve markets that may not generate sufficient demand for nonstop flights.
ACI’s latest connectivity analysis shows that major hubs continue to lead regional connectivity growth. Between 83% and 97% of major hub airports recorded growth in 2025. Dubai remained the region’s leading hub, followed by Shanghai Pudong, Incheon, Hamad International and Guangzhou Baiyun.
The scale of these gateways remains considerable. ACI World estimates that Dubai handled 95.2 million international passengers in 2025. Incheon handled 73.6 million, while Singapore Changi handled 69.4 million international passengers.
Those figures demonstrate why hub aviation remains fundamental to Asian tourism. A traveller heading from a smaller Asian city to Europe, Africa or another distant market may still find a one-stop itinerary through a major hub more practical than waiting for a rare nonstop service.
Advertisement
Advertisement
The Passenger Is Not Always A Tourist
Airport statistics can create misleading impressions if passenger movements are treated as tourism arrivals. A passenger passing through an airport can be counted in airport traffic without becoming a visitor to the destination.
This distinction becomes particularly important for airports with extensive sixth-freedom networks. Such airports connect passengers between two foreign markets, generating enormous traffic while producing a different local tourism effect.
ACI’s 2025 figures illustrate the scale. The world’s international passenger leaders include Dubai, Heathrow, Incheon, Singapore, Amsterdam, Istanbul, Hong Kong and Doha. Their international passenger totals reflect the enormous role of aviation hubs in global mobility, but they should not be interpreted as equivalent tourism-arrival figures.
For travel businesses, the more meaningful question is therefore whether passengers terminate their journey at the airport. That distinction affects hotels, attractions, restaurants, tour operators and local transport providers.
India’s Gateway Network Is Expanding
India provides another important example of this transition. Delhi ranked 28th globally in OAG’s 2026 Megahubs ranking, while IndiGo accounted for 40% of flights at the airport. Delhi also ranked ninth globally in the Low-Cost Megahubs ranking, with 11,045 potential LCC connections across 178 destinations.
Advertisement
Advertisement
India’s enormous domestic market provides a powerful feeder system. Airlines can combine domestic demand with international traffic, allowing airports to support routes that might otherwise struggle.
Yet the tourism numbers show why connectivity must be assessed carefully. India’s Ministry of Tourism records 20.09 million international tourist arrivals provisionally in 2025, including foreign tourists and non-resident Indians. Foreign tourist arrivals alone were about 9.15 million. Indian national departures reached 32.83 million.
That outbound figure is particularly significant for Asian destinations. India’s growing international traveller base provides a large potential market for direct services to Southeast Asia, the Maldives, Japan, South Korea and other regional destinations.
Malaysia Illustrates The Tourism Effect
Malaysia demonstrates how aviation accessibility can operate alongside tourism promotion. The country recorded 28.2 million international visitor arrivals from January to August 2025, representing a 14.5% increase from the same period in 2024.
The first-quarter data provides another useful insight. Malaysia recorded 10.1 million visitor arrivals during January-March 2025, with air travel accounting for 28.9% of all arrivals. Among tourists specifically, air transport represented 42.9% of arrivals.
Advertisement
Advertisement
This demonstrates why airport connectivity and tourism growth should not be considered separate subjects. Direct air access can expand the geographical reach of a destination, while tourism demand gives airlines stronger reasons to sustain routes.
Malaysia’s Visit Malaysia 2026 campaign is targeting 47 million international visitor arrivals. The government has also identified enhanced air accessibility as part of the broader tourism strategy.
Thailand Shows How Airlines Shape Demand
Thailand offers a different example because its tourism market is already exceptionally mature. During January-June 2025, Thailand recorded more than 16.68 million international arrivals, while inbound airline seat capacity reached 24.59 million.
The Tourism Authority of Thailand reported that inbound seats were 7% higher year on year and 88% above pre-Covid levels during that period. It also brought together more than 50 airlines and tourism stakeholders to discuss capacity, connectivity and joint marketing.
This illustrates an important industry principle. Airlines do not merely respond to tourism demand. New capacity can also create demand by making destinations easier, quicker or cheaper to reach.
Advertisement
Advertisement
The relationship therefore works in both directions:
| Aviation Development | Potential Tourism Effect |
|---|---|
| New nonstop route | Easier access to destination |
| Higher frequency | Greater scheduling flexibility |
| LCC entry | Potentially broader price accessibility |
| Larger aircraft | Greater visitor capacity |
| New secondary-city route | Tourism dispersal beyond capitals |
| Hub expansion | More one-stop international options |
| Seasonal service | Access during peak leisure periods |
China And Northeast Asia Add Another Dimension
Northeast Asia demonstrates how established markets can still generate significant connectivity growth. Shanghai Pudong recorded a 32% improvement in connectivity during 2025, according to ACI’s regional index. Guangzhou Baiyun also moved sharply upward in OAG’s global Megahub ranking, reaching 19th place.
Japan provides another interesting contrast. Fukuoka ranks 33rd globally in OAG’s Megahub table and eighth among global Low-Cost Megahubs. Its airline mix is also unusually diverse, with Skymark accounting for only 7% of overall capacity in OAG’s analysis.
That diversity matters because connectivity can become more resilient when it does not depend excessively on one airline. It can also encourage competition across fares, schedules and destination choices.
The Gulf Remains Asia’s Long-Haul Bridge
The Asia-Pacific network cannot be understood without considering the Gulf. Dubai, Doha and Abu Dhabi continue to connect Asian markets with Europe, Africa and the Americas.
Advertisement
Advertisement
ACI found that Asia-Pacific intercontinental traffic grew 7% year on year in 2025 and stood 12% above pre-pandemic levels. Traffic from Asia-Pacific to Europe, the Middle East, Central and South America and Africa had surpassed pre-pandemic levels.
This reinforces the continuing importance of connecting hubs. Direct Asia-Europe services may grow, but Gulf gateways remain strategically positioned between major population and tourism markets.
For travellers, this means the future is unlikely to be purely direct or hub-based. Instead, different journeys will continue to favour different network structures.
What This Means For Travellers
The practical benefit of this transformation is greater choice. Travellers can increasingly compare nonstop services with one-stop alternatives instead of assuming that the biggest airport provides the only realistic route.
A direct flight may reduce journey complexity, transfer risk and total travel time. However, a connecting itinerary can offer more departure frequencies, broader destination coverage or different fare combinations.
Advertisement
Advertisement
Travellers should therefore compare the complete journey, rather than simply the advertised flight duration. A one-stop fare may look cheaper but become less attractive after baggage fees, long layovers and airport transfers are included.
For tourism destinations, direct connectivity can be even more consequential. A new international route can make a secondary city commercially viable as a standalone destination rather than merely an extension of a capital-city itinerary.
A More Useful Way To Measure Connectivity
The most valuable lesson from the data is that airport rankings alone cannot explain tourism growth. A more useful framework combines network scale with destination conversion.
| Measure | What It Reveals | Traveller Relevance |
|---|---|---|
| International destinations | Geographic reach | Where travellers can fly |
| Potential connections | Transfer strength | One-stop journey options |
| Direct city pairs | Nonstop accessibility | Faster, simpler travel |
| LCC share | Network affordability potential | More price-sensitive options |
| International passengers | Airport scale | Overall market depth |
| Tourist arrivals | Destination demand | Actual visitor impact |
| Air capacity growth | Available seats | Future access potential |
This approach also avoids a common analytical mistake. A larger airport is not automatically a stronger tourism gateway, because its traffic may contain a substantial transfer component.
Asia’s Two Networks Will Coexist
The evidence points towards coexistence rather than replacement. Mega-hubs continue to expand their networks, while direct city pairs increasingly connect travellers with destinations that once depended on transfers.
Advertisement
Advertisement
ACI reports that intra-regional flows still represent 91% of departing passenger traffic in Asia-Pacific. International city pairs grew 10% during 2025, while intercontinental traffic also expanded strongly.
For travellers, this means Asia is becoming more navigable at several levels. A major hub can provide breadth, while a direct regional route can provide simplicity.
For destinations, the implications are broader. Airports that attract direct international services can become engines of hotel development, visitor spending and regional tourism dispersal.
The next phase of Asian tourism may therefore be defined less by a battle between hubs and direct flights. Instead, it will be shaped by how intelligently destinations combine both forms of access.
The strongest tourism markets will not necessarily be those with the biggest airports. They may be the places that convert connectivity into actual stays, spending and repeat visits.
That makes Asia’s evolving aviation map more than an airline-network story. It is becoming a fundamental part of how the region distributes tourism, investment and traveller demand.
Advertisement
