
South Korea Overtakes China, Japan, Canada, Australia, Taiwan, Indonesia and More While Philippines Tourism Faces Lowest Performance in Three Years and 2026 Growth Target Slipping Due to Weak Arrivals
Published
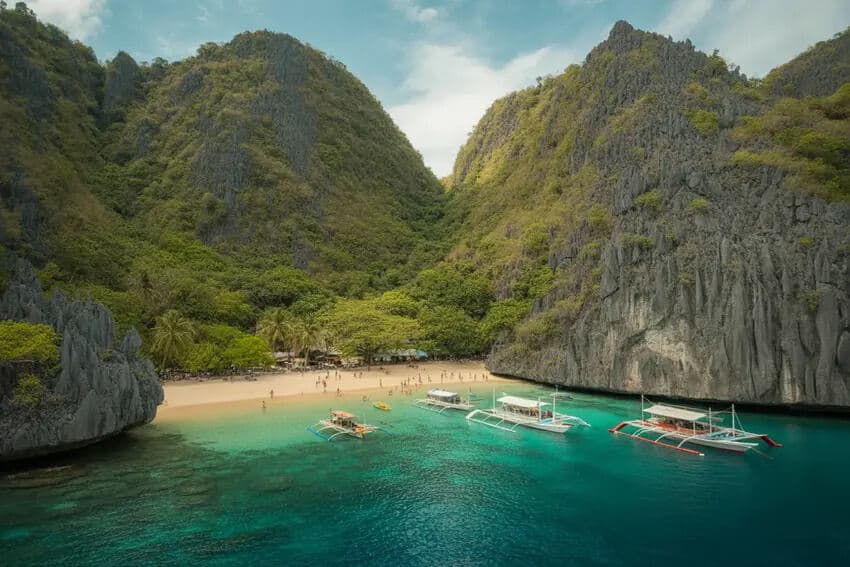
Image generated with Ai
South Korea Overtakes China, Japan, Canada, Australia, Taiwan, Indonesia and More as the Philippines experiences its lowest tourism performance in three years, with 2025 arrivals falling short of expectations. The decline has been driven by weaker visitor numbers from key markets, operational bottlenecks at airports, limited inter-island connectivity, and rising travel costs. These factors combined to reduce inbound spending and overall tourism value, putting the Department of Tourism’s 2026 growth target of 6.7 million visitors at risk. Urgent strategic reforms, infrastructure improvements, and enhanced accessibility are required to restore the Philippines’ competitiveness and attract high-value travellers.
The Philippines tourism industry was reported to have endured a pronounced downturn in 2025, with its economic contribution slipping to the lowest level seen in three years. Data compiled from official tourism statistics confirms that overall visitor numbers, spending patterns, and market dynamics were significantly altered, leaving growth targets for 2026 at risk. Once positioned as a robust engine for employment and foreign exchange, the sector was observed to have weakened in terms of inbound spending and value creation despite resilient local travel activity. Inbound markets from South Korea, China, Japan, Canada, Australia, Taiwan, Indonesia and other key sources were individually impacted, highlighting shifting travel behaviours and competitive vulnerabilities which required urgent strategic response.
A Three‑Year Decline in Philippines Tourism Value
In 2025, the direct contribution of tourism to the Philippines gross domestic product was assessed at 8.1 percent, down from 8.7 percent in the preceding year. This marked the lowest share in three years, and the total tourism gross value added was reported at PHP 2.27 trillion, reflecting a 1.4 percent decline. The downturn was attributed primarily to weaker spending by outbound visitors, even as local travel activity was maintained at steady levels. The shrinking share of total economic output underscored a broader challenge facing the industry: the disconnect between domestic tourism sustainability and international visitor momentum.
Key Source Markets and Changing Visitor Patterns
In 2025, visitor arrivals from major tourism source markets were shifted significantly. While total foreign arrivals were recorded at 6.48 million, the composition of those arrivals was altered, and several top markets had experienced declines that contributed to overall performance pressures.
Advertisement
Advertisement
- South Korea was confirmed as the largest source of visitors, overtaking other markets. However, arrivals were lower compared with previous years, resulting in reduced per‑capita expenditure within key tourism sectors.
- China was held as a historically significant market but saw a marked reduction in traveller numbers and spending, weakening overall inbound performance.
- Japan registered diminished arrival growth compared with early post‑pandemic rebounds, leading to constrained impacts on tourism value.
- Canada experienced a downturn in visits, consistent with weaker outbound travel trends from North America to the Philippines in 2025.
- Australia had fewer visitors than in the prior year, contributing to a softer tourism spend within accommodation and experience sectors.
- Taiwan saw a moderate decline after earlier gains, representing volatility in travel demand during the reporting period.
- Indonesia reflected a smaller but notable decrease in traveller arrivals, reinforcing the pattern of regional market softening.
- Other markets, including parts of Europe and the Middle East, were also observed to have contributed less to overall inbound travel compared with historic averages, as travellers were diverted to competing destinations across Southeast Asia.
These changes in source market dynamics were reflected in weaker overall spending despite continued strong participation in local excursions, festivals, and cultural experiences by domestic tourists.
Shifts in Tourism Spending and Sectoral Contributions
Inbound travel expenditure was observed to have fallen by 6.4 percent during the year, with foreign visitors allocating lower budgets for accommodation, transport services, and food and beverage experiences. By contrast, domestic tourism spending showed resilience and was estimated to have risen by 3 percent, highlighting the persistent demand for local travel experiences, cultural exploration, and regional tourism offerings.
Advertisement
Advertisement
Outbound travel by Filipino residents increased by 3.5 percent, signalling that a portion of tourism expenditure was increasingly directed overseas rather than spent within the domestic economy. This trend had an indirect effect on the overall tourism ecosystem, tightening the aggregate value retained in the national sector.
Major components of tourism employment continued to support significant workforce participation. Tourism‑related services employed an estimated 7.7 million workers, equivalent to approximately 15.7 percent of domestic employment. The composition of this labour force was distributed across several categories, with accommodation services and food and beverage sectors representing the largest share, followed by retail of tourism‑characteristic goods and health and wellness services. These contributions remained vital to community livelihoods, but the contraction in inbound revenue indicated that job creation pressures could emerge if slower growth persisted.
Operational Constraints and Competitive Context
A number of structural bottlenecks were cited as influencing the downturn in visitor performance. Limited airport capacity was highlighted as a persistent challenge, leading to periodic congestion at major gateways and constrained opportunities for expanded flight networks. Inter‑island transport efficiencies were still developing, and friction points at key destinations continued to affect seamless travel experiences.
Transport costs, including airfare, were impacted by global factors such as fluctuating fuel prices and broader geopolitical pressures emanating from West Asia. These external influences compounded the competitive disadvantage faced by the Philippines when compared with some neighbouring markets that had already implemented visa‑free policies, expanded airline incentive schemes, and more aggressive destination marketing programs.
Competing destinations such as Malaysia, Thailand, and Vietnam continued to attract robust visitor numbers, buoyed by expanded flight connectivity and diversified tourism offerings. These countries were collectively reported to have welcomed far larger volumes of visitors during 2025, underscoring the scale of the competitive challenge.
Domestic Tourism Resilience and Experience Demand
Despite the decline in visitor numbers and spending from overseas markets, local travellers were observed to continue exploring destinations across the archipelago. Domestic tourism experiences were supported by beach destinations, heritage and cultural sites, wellness retreats, and emerging adventure travel corridors. These trends helped to offset some of the economic impacts of weaker inbound demand and demonstrated a sustained appetite for travel among Filipino residents.
Advertisement
Advertisement
Local tourism service providers were reported to have responded by enriching experiential packages, prioritising community‑based tourism, and boosting inclusive travel products that catered to a broad cross‑section of segments.
TTW Founder and Editor-in-Chief, Mr. Anup Kumar Keshan shares: “South Korea overtaking China, Japan, Canada, Australia, Taiwan, Indonesia and more as the Philippines’ top source market highlights a significant shift in regional travel dynamics. The lowest tourism performance in three years, coupled with the 2026 growth target at risk due to weaker arrivals, underscores the urgent need for strategic reforms, improved connectivity, and enhanced visitor experiences to restore the country’s competitiveness.“
Outlook for 2026 and Strategic Imperatives
As 2026 approached, officials acknowledged that achieving projected visitor targets was increasingly uncertain without targeted interventions. A target of 6.7 million visitors had been established, yet the performance indicators of 2025 suggested that sustained efforts would be required to reverse the downward trend.
Clear strategic priorities were identified for stabilising and accelerating recovery:
- Capacity enhancements at primary and secondary airports were recommended to improve throughput and attract additional airline services.
- Expanded direct flight linkages and enhanced regional connectivity were advocated to reduce travel friction and improve accessibility.
- Investments in infrastructure modernisation were emphasised as a foundation for offering elevated visitor experiences.
- Strategic marketing approaches designed to showcase destination uniqueness and drive demand from high‑yield segments were highlighted as critical.
These measures were expected to support a stronger competitive stance relative to other regional destinations, ensuring that tourism remained a core contributor to national development goals.
South Korea Overtakes China, Japan, Canada, Australia, Taiwan, Indonesia and More as Philippine tourism records its lowest performance in three years due to weaker visitor arrivals, rising travel costs, and limited airport and inter-island connectivity. This decline has put the 2026 growth target of 6.7 million visitors at risk.
The Philippines tourism industry in 2025 was characterised by a notable downturn in inbound spending and a relative decline in the value contributed to national economic growth. While domestic travel continued to demonstrate resilience, the slip in annual contribution highlighted vulnerabilities tied to source market performance, operational constraints, and regional competition. As the sector prepared for 2026, the emphasis on strategic enhancements was seen as essential for re‑energising growth, restoring visitor confidence, and aligning performance with broader travel and tourism aspirations. Through deliberate improvements in connectivity, infrastructure, marketing, and visitor experience design, the industry was positioned to address short‑term risks while laying groundwork for longer‑term sustainable visitation growth.
Advertisement
