
Spain Retains European Summer Flight Booking Lead as Tourism Demand Recovers and Autumn Air Capacity Expands
Updated
Published
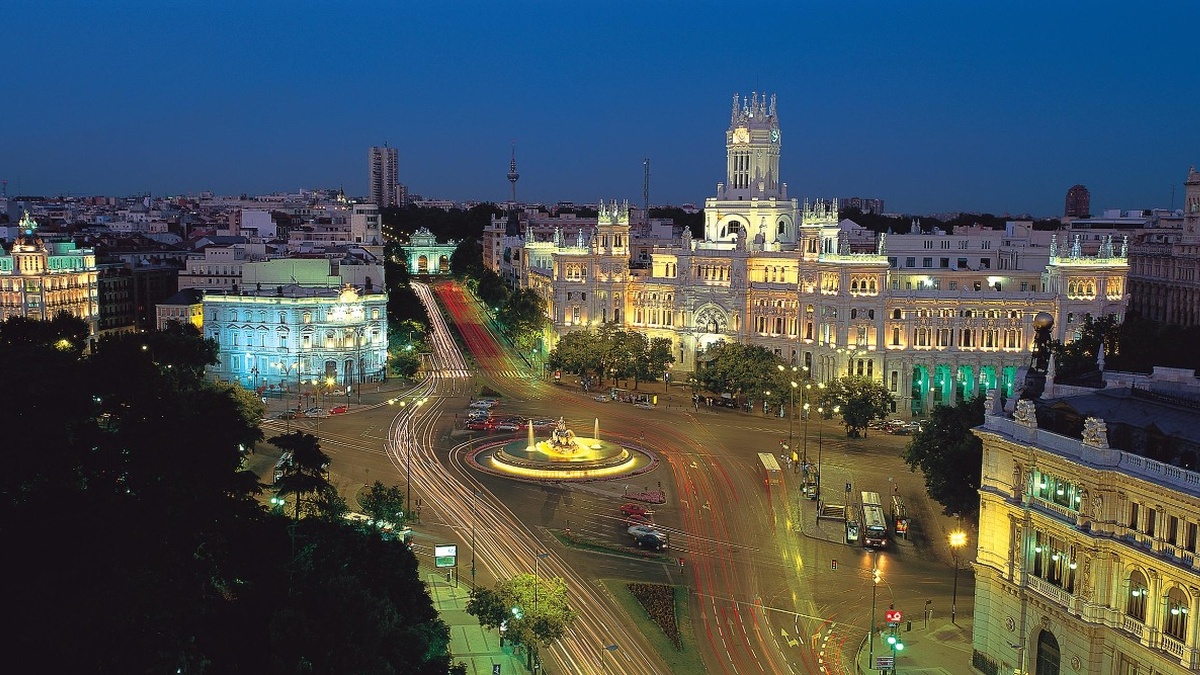
Spain’s 11% share of European flight bookings on RateGain platforms remained unchanged through June, July and August 2026, but the market underneath that headline changed substantially. Official Spanish data show hotel nights moving from a 0.9% decline in June to 1.4% growth in August. Non-resident hotel demand moved from a 2% fall to a 2.8% increase, while hotel-price growth accelerated. Meanwhile, Spain’s airports handled rising passenger volumes and airlines have scheduled 6.4% more international seats for October.
Spain’s Eleven Percent Booking Share Reveals a Stability Story Hidden Beneath Summer Growth
Spain’s position as the largest European destination market among European travellers becomes more significant when the three summer months are examined together rather than treated as a single seasonal total.
Advertisement
Advertisement
RateGain and Sojern data covering June to August 2026 show Spain consistently accounting for 11% of flight bookings recorded on RateGain platforms. The important distinction is that this represents market share within the company’s booking dataset, not 11% of every European flight reservation made through all global channels.
The new angle is therefore not simply that Spain ranked first.
Advertisement
Advertisement
It is that Spain’s relative share remained steady while several important components of its tourism economy changed month by month.
Spanish hotel demand weakened in June, stabilised in July and strengthened in August. International hotel demand followed an even clearer upward trajectory. Hotel prices accelerated. Airport passenger volumes climbed. Low-cost aviation expanded more rapidly than traditional-carrier traffic.
Advertisement
Advertisement
An unchanged booking share alongside those changing indicators suggests that Spain’s competitive position within the RateGain dataset was substantially less volatile than its monthly accommodation figures might imply.
That distinction matters for airlines, hotels, tour operators and destination-management companies attempting to understand whether summer demand represented a temporary peak or a more durable market position.
Official Hotel Figures Show How Spain Changed Between June and August
According to Spain’s National Statistics Institute, INE, hotel overnight stays fell 0.9% year on year in June, before rising 0.3% in July and 1.4% in August.
The composition of demand changed even more sharply.
Non-resident hotel nights declined 2% in June. They then increased 1.1% in July and accelerated to 2.8% growth in August. Domestic hotel nights moved in the opposite direction, rising 1.5% during June but falling 1.1% in both July and August.
| Spain summer tourism indicator | June 2026 | July 2026 | August 2026 |
|---|---|---|---|
| RateGain European flight-booking share | 11% | 11% | 11% |
| Hotel overnight stays YoY | -0.9% | +0.3% | +1.4% |
| Non-resident hotel nights YoY | -2.0% | +1.1% | +2.8% |
| Resident hotel nights YoY | +1.5% | -1.1% | -1.1% |
| Hotel Price Index YoY | +5.6% | +5.9% | +6.3% |
| Average occupied-room rate | €137.10 | €156.90 | €166.90 |
| Aena Spain-network passengers | 31.64m | 34.41m | 34.89m |
| Aena passenger growth YoY | +3.8% | +5.0% | +4.7% |
The table exposes the underlying shift.
Advertisement
Advertisement
Spain did not move through summer on a straight upward line. Hotel demand actually contracted at the beginning of the period before returning to growth. Yet the supplier booking dataset continued to assign Spain the same 11% share.
By August, INE recorded more than 48.7 million hotel overnight stays. Non-resident demand was growing while domestic demand was contracting. Across January to August, hotel nights were 1.5% higher than a year earlier, with non-resident stays up 2% compared with only 0.4% growth among Spanish residents.
Foreign Travellers Were Doing More of the Work by the Peak of Summer
The August hotel numbers strengthen the argument that Spain’s summer resilience increasingly rested on international rather than domestic accommodation demand.
Foreign travellers generated growth of 2.8% in hotel overnight stays during August. Spanish-resident nights declined 1.1%.
The Balearic Islands accounted for 33% of non-resident hotel nights, Catalonia for 20.6% and the Canary Islands for 18.2%. The United Kingdom supplied 25.5% of all non-resident hotel nights, followed by Germany at 14.5%.
This concentration remains commercially important.
Advertisement
Advertisement
Spain can maintain a strong national position while individual source markets and destinations follow very different trajectories. Tour operators therefore cannot safely apply the national 11% figure uniformly to every Spanish resort, island, urban destination or feeder market.
July visitor expenditure provides another indicator.
According to INE’s latest available FRONTUR figures on 1 October, Spain received 11,538,796 international tourists in July, 4.6% more than a year earlier. Of these, 9,234,063 arrived by air, an increase of 4.97%.
International visitors spent €18.218 billion during July, 10.9% more than in July 2025. Average expenditure reached €1,579 per tourist, while average daily spending increased to €218.
The expenditure increase therefore substantially exceeded growth in international visitor numbers that month.
That matters to the travel trade because Spain’s 2026 performance is increasingly a story about value and yield as well as volume.
Advertisement
Advertisement
Higher Hotel Prices Did Not Prevent Foreign Demand From Recovering
Spain’s accommodation market became more expensive as the summer progressed.
INE’s Hotel Price Index increased 5.6% year on year during June, 5.9% during July and 6.3% during August.
Average revenue per occupied hotel room rose from €137.10 in June to €156.90 in July and €166.90 in August. August’s average was 7.3% higher than a year earlier.
This creates a commercially important divergence.
Hotel-night volume rose only 1.4% in August, but the average occupied-room rate increased 7.3%. Operators assessing Spain solely through traveller counts could therefore underestimate the pricing pressure facing customers and package margins.
For travellers, the implication is straightforward. Strong destination demand does not necessarily produce abundant low-cost hotel inventory.
Advertisement
Advertisement
For travel sellers, it strengthens the case for dynamic accommodation contracting, flexible inventory management and closer monitoring of regional rates instead of assuming that national visitor growth determines the direction of hotel prices.
Spain’s Aviation Network Confirms That High Travel Volumes Were Reaching the Country
The accommodation recovery was accompanied by substantial aviation activity.
According to Turespaña, 12,309,076 passengers arrived in Spain from international airports in August 2026, 5.5% more than during August 2025. Europe generated 85.7% of these passengers, with European-origin traffic increasing 5.7%.
There is an important methodological distinction. Turespaña explicitly counts both Spanish residents and non-residents travelling on international flights. International air passengers must therefore not be treated as equivalent to international tourists.
Low-cost airlines carried 7,527,454 of August’s international arrivals, representing 61.2% of the total and growth of 8.5%. Traditional carriers carried 4,781,622 passengers, up only 1.1%.
That gap is strategically significant.
Advertisement
Advertisement
It shows that lower-cost aviation was expanding much faster than traditional airline traffic during the month when Spain’s foreign hotel demand was also strengthening.
Between January and August, international-flight passengers reached 79.33 million, an increase of 5.2%. Low-cost airlines accounted for approximately 3.3 million of the 3.9 million additional international passenger arrivals recorded over the period.
Madrid and Barcelona Show Why National Booking Strength Still Depends on Major Gateways
The aviation data also places Madrid and Barcelona directly inside the Spain-wide story.
Turespaña recorded 2,478,698 international-flight arrivals at Adolfo Suárez Madrid-Barajas in August, 4.6% more than a year earlier. Barcelona received 2,285,880, an increase of 5.9%. Together, the airports handled almost 39% of Spain’s international-flight passenger arrivals during the month.
The broader Aena figures, which include domestic and international airport traffic, reinforce their gateway role.
Madrid-Barajas handled 6,544,815 passengers in August, up 4.8%, while Barcelona-El Prat handled 5,933,007, up 4.6%. Across Aena’s Spanish network, total August throughput reached 34,890,784 passengers, 4.7% higher year on year.
Advertisement
Advertisement
Spain’s Aena airports had already handled 31,639,672 passengers in June and 34,406,581 in July.
The booking-share story is therefore supported by actual high-volume movement through the country’s aviation infrastructure rather than by forward intent alone.
October Air Capacity Opens the Next Test for Spain’s Tourism Resilience
Perhaps the most important new information available on 1 October lies beyond the completed summer.
Turespaña’s latest air-capacity report shows airlines have programmed 12,764,152 international seats to Spain for October 2026, an increase of 6.4% compared with October 2025. The forecast is based on scheduled airline capacity and remains subject to airline changes.
| Origin market | Planned October seats | Share of international capacity | YoY change |
|---|---|---|---|
| United Kingdom | 2,864,436 | 22.4% | +6.8% |
| Germany | 1,766,098 | 13.8% | +5.3% |
| Italy | 1,262,970 | 9.9% | +12.2% |
| France | 872,027 | 6.8% | -2.2% |
| Netherlands | 570,684 | 4.5% | +0.1% |
| Poland | 358,850 | 2.8% | +34.2% |
| United States | 301,961 | 2.4% | +2.6% |
| Total international | 12,764,152 | 100% | +6.4% |
The figures do not prove that Spain will retain its 11% booking share in October. Scheduled seats are capacity, not completed journeys or bookings.
They do, however, show that the aviation pipeline entering the autumn remains larger than last year.
Advertisement
Advertisement
That makes October a critical test of whether Spain’s summer resilience can translate into stronger shoulder-season activity.
Why This New Spain Tourism Angle Matters to the Travel Industry
The deeper signal is not simply market leadership. It is the decoupling of market-share stability from individual operating indicators.
Spain held the same RateGain booking share even while hotel nights first contracted and then recovered. Foreign hotel demand strengthened as domestic demand weakened. Room-price inflation accelerated. Low-cost international aviation grew much faster than traditional-carrier traffic.
For B2B travel companies, that combination changes how Spanish demand should be interpreted.
A stable national booking share can coexist with large variations by month, source market, accommodation sector and destination. That means a national headline cannot replace granular forecasting.
The UK continued to deliver substantial international hotel and aviation demand. Italy expanded strongly. Germany and France recorded softer August international-flight passenger performance. Poland grew from a much smaller base at an exceptional rate.
Advertisement
Advertisement
The opportunity therefore lies not merely in selling more Spain. It lies in identifying where, when and from which origin markets demand is expanding fastest, while accounting for rapidly rising accommodation costs.
That is the information hidden beneath the 11% headline.
Operational Takeaways for Travel Agents and Tour Operators
- Separate share from volume. Spain’s constant 11% RateGain share indicates relative market strength but does not establish that absolute bookings increased identically every month.
- Monitor foreign and domestic hotel demand separately. August growth was being driven more strongly by non-resident travellers while resident nights declined.
- Protect package margins. Hotel-price growth and occupied-room rates are increasing considerably faster than hotel-night volume, raising contracting and repricing risk.
- Segment source markets. UK and Italian aviation flows expanded in August, while Germany and France declined, making market-specific inventory strategies more useful than a single Europe-wide assumption.
- Watch low-cost connectivity. Low-cost international passenger arrivals increased 8.5% in August, far ahead of traditional-carrier growth.
- Use October capacity cautiously. The 6.4% scheduled increase creates additional sales opportunity but represents programmed seats rather than guaranteed passenger demand.
- Do not equate aviation passengers with tourists. Turespaña’s international-flight count includes Spanish residents returning from overseas.
- Wait for the next official evidence before extending the trend. Spain’s August FRONTUR international-tourist and EGATUR expenditure results are scheduled for publication on 2 October 2026.
Spain’s Next Tourism Test Comes After the Summer Peak
Spain enters October with a stronger aviation pipeline, higher hotel pricing and evidence that foreign accommodation demand accelerated through the latter part of summer.
Yet the strongest conclusion remains more precise than simply calling Spain a booming destination.
The new evidence shows resilience of competitive share despite substantial movement underneath the national total.
According to Turespaña’s official publication calendar, August international tourist arrivals and expenditure will be released on 2 October, September international-air passenger data on 19 October, and September hotel figures on 23 October. Those releases will establish whether foreign-led momentum continued beyond August.
Advertisement
Advertisement
For the international travel trade, Spain’s summer performance therefore carries a wider lesson. Mature tourism markets do not need explosive monthly growth to protect their competitive position. Connectivity, large feeder markets, destination diversity and pricing power can keep market share stable even while individual demand indicators move in different directions.
Spain’s 11% share is consequently more revealing as a measure of consistency than as another record-volume headline. October’s 12.76 million scheduled international seats will now test whether that consistency can extend from Europe’s peak summer season into the autumn travel economy.
Advertisement
