
Las Vegas Witnessing a Slump in Tourist Arrivals Learning Lesson for US Tourism Through August 2026
Published
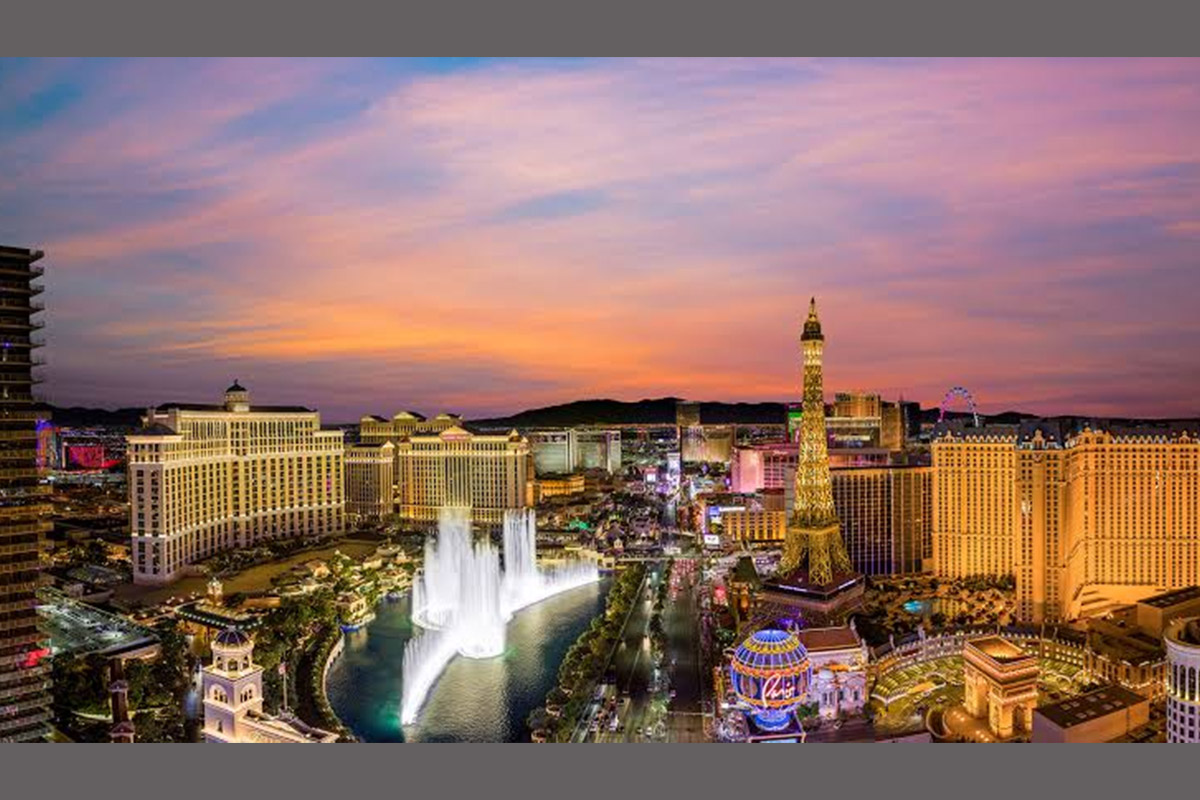
Image generated with Ai
Official economic data confirms that Las Vegas tourist arrivals experienced a notable contraction through August 2026, driven primarily by falling domestic travel from critical swing states across America. As household discretionary budgets tighten under persistent macroeconomic headwinds, essential visitor volumes from key electoral battlegrounds including Arizona, Pennsylvania, and Michigan have faltered significantly. This unexpected slump poses direct risks to the local hospitality sector, municipal tax receipts, and broader regional employment metrics. Understanding these shifting domestic travel patterns is crucial for industry leaders, municipal planners, and economic analysts attempting to navigate evolving consumer spending habits and safeguard long-term regional financial stability.
Historical Context and Background of Nevada’s Tourism Ecosystem
Advertisement
Advertisement
For over half a century, Southern Nevada has functioned as a barometer for American consumer confidence and discretionary spending. The Las Vegas metropolitan area, anchored by the iconic Las Vegas Strip and the downtown Fremont Street district, represents one of the most concentrated hospitality and gaming markets on Earth. Governed by a sophisticated economic apparatus that includes the Las Vegas Convention and Visitors Authority (LVCVA) and the Nevada Gaming Control Board, the region relies immensely upon continuous, high-volume domestic leisure travel to sustain its multi-billion-pound economy. Historically, when domestic economic conditions remain stable, consumer expenditure on entertainment, dining, lodging, and gaming expands predictably, positioning Las Vegas as a principal beneficiary of national prosperity.
The operational foundation of this ecosystem rests upon a delicate balance between leisure travel, convention business, and casino gaming operations. Domestic visitors account for approximately 80 to 85 per cent of all total annual visits to Clark County, making the region acutely sensitive to subtle fluctuations in domestic macroeconomic sentiment. Over successive economic cycles—including the post-2008 recovery and the post-pandemic rebound—the market demonstrated remarkable resilience by pivoting towards non-gaming amenities, sports tourism, and world-class culinary experiences. However, the foundational revenue model remains intrinsically tied to personal savings rates, wage growth, and available household credit across primary feeder markets in the United States.
Advertisement
Advertisement
Historically, primary feeder markets for Southern Nevada were predominantly defined by geographical proximity. Neighboring Western states such as California, Utah, and Arizona supplied the majority of drive-in visitors, while major metropolitan air hubs across the Midwest, Sun Belt, and Eastern Seaboard provided steady streams of fly-in tourists. In recent years, demographic realignments and domestic migration trends have altered this baseline. States across the Sun Belt and traditional Rust Belt industrial hubs have emerged as vital demographic pockets that dictate the health of midweek and weekend room occupancy rates across major Strip resort properties.
As the market entered mid-2026, baseline economic indicators across Southern Nevada initially reflected post-pandemic normalization. However, underlying shifts in domestic consumer behaviour began to manifest beneath aggregate headline figures. While luxury tourism and high-roller gaming segments maintained steady momentum, the foundational middle-market consumer segment—traditionally originating from suburban and industrial centers across American swing states—started exhibiting signs of expenditure fatigue. Understanding the root causes of this current trend requires examining both regional economic headwinds and broader national fiscal realities.
Advertisement
Advertisement
LAS VEGAS DOMESTIC VISITOR ORIGIN BREAKDOWN (HISTORICAL VS 2026)
+————————————+——————+——————+
Advertisement
Advertisement
| Feeder Region / Segment | Baseline Share | Aug 2026 Share |
+————————————+——————+——————+
| West Coast Drive-In (CA, UT, AZ) | 42.5% | 44.1% |
| Sun Belt Swing States (AZ, GA, NC) | 16.2% | 13.8% |
Advertisement
Advertisement
| Rust Belt Swing States (MI, PA, WI)| 14.8% | 11.9% |
| Other Domestic Markets | 16.5% | 18.2% |
| International Travel | 10.0% | 12.0% |
+————————————+——————+——————+
The 2026 Macroeconomic Landscape and Swing State Demographics
The economic backdrop of mid-2026 presents a complex web of structural challenges for American households. While top-line national economic figures display modest growth, localized inflationary pressure, elevated consumer credit balances, and prolonged high interest rates have compressed real disposable income. This dynamic is particularly pronounced in key electoral battlegrounds—often referred to as swing states—including Arizona, Georgia, Michigan, North Carolina, Pennsylvania, and Wisconsin. In these regions, working-class and middle-income families face disproportionate financial pressures regarding core expenditure categories such as housing, healthcare, insurance, and municipal utility tariffs.
Advertisement
Advertisement
Discretionary Spending Patterns Across Electoral Battlegrounds
The relationship between economic stress in swing states and swing state leisure travel to major resort destinations is direct and measurable. According to empirical studies from the Bureau of Economic Analysis and regional Federal Reserve banks, discretionary leisure travel is among the very first household budget items reduced or eliminated when real wages stall. Throughout the spring and summer of 2026, consumer financial stress indicators across swing states ticked upward. Personal savings rates across the Rust Belt and Sun Belt battleground states dropped below historical averages, forcing households to prioritize essential domestic obligations over long-distance vacations.
Furthermore, cumulative credit card debt reached record highs across the United States in mid-2026, leading to stricter underwriting guidelines from major consumer lending institutions. Consequently, middle-income households in states like Pennsylvania and Michigan have scaled back on high-cost domestic trips that require commercial air travel, lodging, and premium entertainment expenses. When families in these states choose to travel, data from national statistical offices indicates a distinct preference for shorter, regional drive-to destinations rather than long-haul flights to Nevada, directly constraining the flow of Las Vegas tourist arrivals.
Regional Inflation Pressures and Consumer Sentiment Metrics
Consumer sentiment metrics gathered by academic research institutions and public statistics agencies reveal a notable divergence between geographic regions. While coastal metropolitan areas with concentrated technology and financial services sectors demonstrated relative spending resilience, industrial and suburban communities in Midwestern and Southeastern swing states experienced persistent sentiment declines through August 2026. High cumulative inflation over recent years has permanently altered price perception, making consumers exceptionally sensitive to non-essential price increases in hotel resort fees, restaurant dining, and event ticketing.
This heightened price sensitivity directly impacts the economics of a Las Vegas vacation. The historical perception of Las Vegas as a high-value, budget-friendly leisure destination has gradually shifted over the past decade toward an elevated, premium-experience model. For residents in battleground states experiencing cumulative wage stagnation relative to cost-of-living adjustments, the total cost of a three-night Las Vegas excursion—including airfare, resort fees, food and beverage surcharges, and entertainment—has surpassed acceptable threshold levels for average household budgets.
Advertisement
Advertisement
Latest Official Data: Analyzing August 2026 Visitor Statistics
Official statistics released by public government agencies and municipal authorities confirm a tangible downturn in overall travel volume to Clark County through the end of August 2026. The official data paints a definitive picture of a changing marketplace where domestic volume reductions are pulling down aggregate performance metrics, despite selective strength in specialized international travel and high-value convention gatherings.
LVCVA AUGUST 2026 VISITOR METRICS COMPARISON (YEAR-ON-YEAR)
+———————————–+—————-+—————-+————+
| Metric | August 2025 | August 2026 | Change (%) |
+———————————–+—————-+—————-+————+
Advertisement
Advertisement
| Total Visitor Volume | 3,572,100 | 3,388,400 | -5.1% |
| Domestic Visitor Volume | 3,120,400 | 2,895,200 | -7.2% |
| Strip Hotel Occupancy Rate | 85.4% | 80.1% | -5.3 pts |
| Average Daily Rate (ADR) | $188.50 | $179.20 | -4.9% |
| Revenue Per Available Room (RevPAR)| $160.98 | $143.54 | -10.8% |
+———————————–+—————-+—————-+————+
Advertisement
Advertisement
LVCVA Visitor Volume Metrics and Monthly Comparisons
According to official monthly research published by the Las Vegas Convention and Visitors Authority, overall visitor volume for August 2026 contracted by 5.1 per cent year-on-year, settling at 3,388,400 visitors compared to 3,572,100 recorded in August 2025. When isolated to domestic leisure travel, the contraction is even more pronounced. Total domestic passenger arrivals dropped by 7.2 per cent, marking the sharpest single-month year-on-year decline recorded in 2026.
A granular examination of the LVCVA data reveals that the primary driver of this aggregate decrease was a sharp fall in midweek and non-holiday weekend leisure travel. While major holiday weekends and targeted sports events maintained relatively high venue utilization, standard calendar weeks suffered from widespread room vacancies across both Strip and Downtown hotel inventories. The monthly report highlighted that while international arrival figures showed a modest increase of 1.8 per cent due to expanding direct flight routes from Europe and Latin America, this gain was wholly insufficient to offset the substantial drop in domestic leisure passenger numbers.
Harry Reid International Airport Passenger Flow Dynamics
Complementary data provided by the Clark County Department of Aviation through Harry Reid International Airport operational reports further validates these findings. Total Harry Reid International Airport passenger volume for August 2026 reached 4,610,200 commercial passengers, representing a 4.8 per cent reduction compared to the corresponding period in 2026. A detailed breakdown of domestic flight origin points highlights that domestic routes departing from regional hubs across swing states suffered the highest load-factor contractions.
HARRY REID INTERNATIONAL AIRPORT SWING STATE ORIGIN LOAD FACTORS
Advertisement
Advertisement
+———————————+——————+——————+————+
| Origin Airport / Hub State | Aug 2025 Load (%)| Aug 2026 Load (%)| Variance |
+———————————+——————+——————+————+
| Phoenix Sky Harbor (AZ) | 88.2% | 81.4% | -6.8 pts |
| Philadelphia International (PA) | 86.7% | 78.2% | -8.5 pts |
| Detroit Metropolitan (MI) | 85.1% | 76.9% | -8.2 pts |
Advertisement
Advertisement
| Hartsfield-Jackson Atlanta (GA) | 89.4% | 82.1% | -7.3 pts |
| Milwaukee Mitchell Int’l (WI) | 83.9% | 74.5% | -9.4 pts |
+———————————+——————+——————+————+
Aviation analytics indicate that domestic carriers operating direct routes connecting Las Vegas to critical battleground hubs—such as Detroit Metropolitan Airport, Philadelphia International Airport, Phoenix Sky Harbor, and Milwaukee Mitchell International Airport—adjusted their operational capacity in response to falling forward booking rates. Several ultra-low-cost carriers and legacy airlines reduced direct flight frequencies on these specific routes by between 6 and 12 per cent during late summer 2026, citing weaker demand and lower yields per available seat mile.
Swing State Contraction: A Detailed Breakdown by Region
The geography of the 2026 travel slump reveals clear regional patterns. Rather than a uniform national decrease, the contraction in domestic arrivals is heavily concentrated within specific macroeconomic zones, directly overlapping with politically sensitive swing states.
Advertisement
Advertisement
REGIONAL DOMESTIC TRAVEL CONTRACTION TO LAS VEGAS (AUG 2026)
Rust Belt Battlegrounds (MI, PA, WI) [█████████████████] -9.2% YoY
Sun Belt Battlegrounds (AZ, GA, NC) [████████████] -6.8% YoY
West Coast Traditional (CA, WA, OR) [██████] -2.4% YoY
Northeast Corridor (NY, NJ, MA) [████████] -3.1% YoY
The Sun Belt Corridor: Arizona and Georgia Visitor Reductions
Advertisement
Advertisement
Arizona, a vital adjacent swing state that historically supplies high volumes of drive-in and short-haul flight visitors to Southern Nevada, demonstrated notable travel pullbacks throughout the summer of 2026. Data cross-referenced from the Arizona Office of Tourism and Nevada Department of Transportation traffic counting stations along the Interstate 11 corridor showed a 6.4 per cent year-on-year drop in personal vehicular crossings at the Nevada-Arizona border during August 2026.
Economic factors driving this trend in Arizona include elevated residential housing costs, rising automotive insurance premiums, and localized employment deceleration in mid-tier commercial sectors. Similarly, in Georgia—another critical Sun Belt battleground—air travel originating from Hartsfield-Jackson Atlanta International Airport bound for Las Vegas contracted by 7.3 per cent. Household surveys conducted by national economic research councils suggest that middle-income families in suburban Atlanta increasingly opted for drivable regional coastlines in the Southeast over long-distance gaming excursions to Nevada, directly contributing to the hospitality revenue contraction observed across mid-scale Strip resorts.
The Rust Belt Divergence: Michigan, Pennsylvania, and Wisconsin
The industrial Rust Belt states of Michigan, Pennsylvania, and Wisconsin recorded the most acute drops in travel to Las Vegas during the summer 2026 reporting period. Passenger movement records from the Bureau of Transportation Statistics confirm that non-stop commercial flight passenger counts from these three states to Las Vegas fell by an aggregate 9.2 per cent year-on-year through August.
In Michigan, where manufacturing and automotive sectors faced structural realignments and wage adjustments throughout early 2026, consumer survey data revealed a sharp reduction in long-distance leisure travel intentions. In Pennsylvania, similar economic patterns emerged across suburban Philadelphia and Allegheny County, where discretionary financial reserves were prioritized for non-discretionary home maintenance and educational expenses. Wisconsin exhibited a parallel drop, with regional flight departures from Milwaukee and Green Bay showing significant seat-capacity underutilization. The combined effect of these regional pullbacks created a noticeable vacuum in mid-tier room demand on the Las Vegas Strip, directly impacting secondary revenue centers such as property dining, retail outlets, and live show entertainment venues.
Hospitality and Gaming Sector Financial Impact
Advertisement
Advertisement
The reduction in visitor volume from key domestic regions has directly impacted the financial performance metrics of major casino-resort operators across Southern Nevada. Public financial filings, earnings releases, and regulatory statements submitted to the Nevada Gaming Control Board illustrate the commercial fallout of fewer Las Vegas tourist arrivals.
Room Rates, Occupancy, and RevPAR Indicators
Hospitality sector health is traditionally evaluated using three core industry metrics: Occupancy Rate, Average Daily Rate (ADR), and Revenue Per Available Room (RevPAR). Data compiled by the LVCVA for August 2026 highlights downward pressure across all three metrics, breaking a multi-year trend of post-pandemic room rate expansion.
STRIP VS DOWNTOWN HOTEL METRICS PERFORMANCE (AUGUST 2026)
+———————————–+——————–+——————–+
| Performance Metric | Las Vegas Strip | Downtown District |
Advertisement
Advertisement
+———————————–+——————–+——————–+
| Overall Occupancy Rate | 81.2% | 68.4% |
| Midweek Occupancy Rate | 76.5% | 61.2% |
| Weekend Occupancy Rate | 89.8% | 80.5% |
| Average Daily Rate (ADR) | $192.40 | $98.60 |
| RevPAR Variance (YoY) | -9.8% | -12.4% |
Advertisement
Advertisement
+———————————–+——————–+——————–+
Overall hotel occupancy across Clark County dropped to 80.1 per cent in August 2026, down 5.3 percentage points from August 2025. Midweek occupancy experienced the steepest decline, falling to 75.2 per cent across non-convention weeks. To maintain baseline volume, major hospitality operators were forced to moderate room pricing strategies. The county-wide Average Daily Rate fell by 4.9 per cent to $179.20, while Revenue Per Available Room—the gold standard metric for lodging efficiency—suffered a steep 10.8 per cent drop to $143.54.
The financial strain was distributed unevenly across resort tiers. Upper-upscale and luxury properties along the central Strip maintained relatively stable pricing power due to affluent domestic travelers and high-spending international guests. In contrast, mid-tier and budget-conscious properties—which rely heavily on middle-class families from Midwestern and Sun Belt swing states—suffered RevPAR contractions exceeding 14 per cent year-on-year. This structural divergence underscores how macroeconomic pressure on lower-and-middle-income demographics translates directly into reduced commercial yield for mid-market hospitality assets.
Nevada Gaming Control Board Revenue Reports
The gaming sector, regulated by the Nevada Gaming Control Board, similarly reflected the operational impact of diminished foot traffic. Official gross gaming revenue (GGR) figures released for August 2026 confirmed total statewide gaming win of £1.12 billion ($1.21 billion USD), representing a 3.8 per cent year-on-year decrease on a fee-adjusted basis.
CLARK COUNTY GAMING WIN BREAKDOWN BY LOCATION (AUGUST 2026)
Advertisement
Advertisement
+———————————–+——————–+——————–+
| Geographic Sub-Market | Aug 2026 Gaming Win| Year-on-Year Change|
+———————————–+——————–+——————–+
| Las Vegas Strip | $642.5 Million | -4.2% |
| Downtown Las Vegas | $61.2 Million | -6.1% |
| Boulder Strip | $78.4 Million | -1.8% |
Advertisement
Advertisement
| Balance of County / Local Resorts | $135.8 Million | -2.9% |
| Total Clark County | $917.9 Million | -4.0% |
+———————————–+——————–+——————–+
On the Las Vegas Strip, gaming win dropped 4.2 per cent to $642.5 million. Analysis of gaming category performance reveals that mass-market slot machine drop and table game drop experienced noticeable contractions, directly corresponding to lower overall floor volume. Slot machine win along the Strip fell by 5.1 per cent year-on-year, reflecting reduced participation from budget-conscious domestic visitors. Conversely, high-limit baccarat and specialized premium table games experienced less volatility, further validating the economic diagnosis that top-tier affluent play remains insulated while mass-market domestic participation faces real headwind constraints.
Convention and Business Travel Divergence
In contrast to the clear contraction in domestic leisure travel, the professional convention and business event sector demonstrated structural divergence during the same August 2026 reporting period. Business events, trade shows, and corporate conventions operate on extended multi-year booking cycles, making them far less susceptible to sudden shifts in short-term household discretionary budgets.
Advertisement
Advertisement
CONVENTION VS LEISURE VISITOR TRENDS THROUGH AUGUST 2026
Convention Delegate Volume [████████████████████] +3.4% YoY
Leisure Travel Volume [████████████] -7.2% YoY
Data from the LVCVA confirms that convention attendance in August 2026 actually expanded by 3.4 per cent year-on-year, reaching 512,600 delegates across major facilities including the Las Vegas Convention Center, the Sands Expo & Convention Center, and private resort meeting spaces. Major trade shows in the medical, technological, and industrial sectors drew steady corporate attendance, helping offset what would otherwise have been a more severe collapse in midweek room occupancy metrics.
However, business travel analytics highlight a critical shift in delegate spending behaviour. While corporate delegates attended scheduled convention events, secondary expenditure—including non-hosted dining, independent entertainment, and personal gaming participation—showed measurable moderation. Corporate risk-management policies and trimmed company travel expense accounts across corporate entities based in Michigan, Pennsylvania, and Georgia led to tighter per-diem spending caps. Consequently, while delegates filled hotel rooms, their per-capita ancillary spend across the broader urban ecosystem remained subdued compared to historical benchmarks.
Policy Implications for Municipal and State Governance
Advertisement
Advertisement
The contraction in domestic tourism volume carries profound long-term implications for local governance, public infrastructure funding, and statewide fiscal management in Nevada. Because Nevada operates without a state personal income tax, public services are disproportionately funded through consolidated sales taxes, room taxes (lodging tax), and live entertainment taxes collected in Clark County.
NEVADA TAX REVENUE STRUCTURAL DEPENDENCE
+————————————+—————————————+
| Tax Mechanism | Primary Funding Allocation |
+————————————+—————————————+
| County Room Tax (Transient Lodging) | Clark County School District, LVCVA |
Advertisement
Advertisement
| Live Entertainment Tax (LET) | Nevada State General Fund |
| Gaming Revenue Tax | State Operating Budget, Infrastructure|
| Consolidated Sales Tax (C-TAX) | Municipal Police, Fire, Local Services|
+————————————+—————————————+
Tax Revenue Allocation and Public Service Financing
The gaming tax revenue and transient lodging tax collections gathered through August 2026 revealed noticeable variances against state budget projections. The Nevada Department of Taxation reported that transient lodging tax distributions—which directly fund the Clark County School District, transportation infrastructure projects, and regional tourism promotion—fell 6.8 per cent short of projected revenue targets for the second consecutive quarter in 2026.
Advertisement
Advertisement
This revenue shortfall creates operational pressure for local public administrators. The Clark County School District, which relies heavily on room tax allocations to service capital improvement bonds and operational budgets, faces potential fiscal adjustments if visitor volumes fail to recover during the autumn and winter quarters. Similarly, the regional transportation fund, responsible for maintaining high-density transit corridors connecting Harry Reid International Airport to the resort district, faces potential deferrals of planned capital upgrades due to reduced tax distributions.
State Level Economic Stabilization Strategies
At the state executive level, economic policy advisors are actively evaluating strategies to stabilize tax collections and reduce reliance on volatile domestic leisure cycles. The Nevada Governor’s Office of Economic Development (GOED) has intensified efforts to accelerate industry diversification programs, targeting expansion in advanced logistics, green technology, healthcare research, and commercial manufacturing across Southern and Northern Nevada.
Simultaneously, municipal authorities are reviewing regulatory frameworks surrounding short-term residential rentals and commercial entertainment licensing fees. Public policy discussions centered around the US macroeconomic indicators emphasize the urgent need to establish broader economic counterweights. By diversifying the state’s tax base beyond casino-resort operations and transient room taxes, state leadership aims to build long-term structural insulation against future national consumer spending downturns and regional economic volatility.
Industry Stakeholder Responses and Strategic Realignments
In response to falling visitor numbers from key feeder markets, resort operators, airline executives, and tourism boards have initiated targeted strategic realignments aimed at revitalizing domestic demand and defending market share.
Advertisement
Advertisement
HOSPITALITY REVENUE RECOVERY STRATEGIES (LATE 2026 IMPLEMENTATION)
+———————————–+—————————————-+
| Strategic Initiative | Target Demographic / Operational Objective|
+———————————–+—————————————-+
| Dynamic Resort Fee Structuring | Re-engage price-sensitive domestic consumers|
| Midweek Package Unbundling | Boost lagging non-convention room night sales|
Advertisement
Advertisement
| Targeted Sun Belt Marketing | Recapture lost regional drive-in market share|
| International Route Subsidies | Expand long-haul, high-yield flight arrivals|
+———————————–+—————————————-+
Major hospitality chains operating on the Strip have begun recalibrating their promotional and marketing campaigns. Advertising spend previously allocated broadly across nationwide broadcast networks is being intensely re-targeted using hyper-localized digital campaigns in specific non-battleground metros and high-performing drive-in corridors. Furthermore, properties are experimenting with bundled promotional packages—including complimentary food and beverage credits, waived parking fees, and discounted show tickets—to improve consumer perception of overall travel value without formally lowering published baseline room rates.
Airline partners are similarly adjusting their operational models. Carriers are evaluating route profitability and reallocating aircraft capacity toward higher-yielding transcontinental and international routes while temporarily trimming flight frequencies from underperforming Midwest regional airports. Concurrently, the LVCVA has launched fresh marketing campaigns across domestic markets, emphasizing new sports entertainment venues, high-profile music residencies, and upcoming major athletic events scheduled for late 2026 and early 2027 to rebuild consumer urgency among middle-class households.
Comprehensive Future Outlook for Las Vegas Tourism (Late 2026–2027)
Advertisement
Advertisement
Looking forward into the final quarter of 2026 and early 2027, the outlook for Las Vegas tourism remains tied to broader domestic macroeconomic adjustments, monetary policy decisions by the Federal Reserve, and real wage growth stabilization across primary feeder states.
2026-2027 SCENARIO FORECAST MODEL
+————————–+———————–+————————-+
| Economic Scenario | Core Assumptions | Projected Visitor Impact|
+————————–+———————–+————————-+
| Base Case (Moderate) | Flat interest rates, | Slow recovery (+1.5% to |
Advertisement
Advertisement
| | mild wage growth | +2.5% YoY in Q1 2027) |
+————————–+———————–+————————-+
| Downside Case (Stagnant) | Persistent inflation, | Continued drop (-3.0% to|
| | tighter credit lines | -5.0% through winter) |
+————————–+———————–+————————-+
| Upside Case (Rebound) | Rate cuts, consumer | Sharp volume rebound |
Advertisement
Advertisement
| | confidence surge | (+4.0% to +6.0% Q2 2027)|
+————————–+———————–+————————-+
If national interest rate policy shifts toward monetary easing in late 2026, lowering consumer credit costs and borrowing friction, household savings buffers across Midwestern and Sun Belt swing states could begin to replenish. A stabilization of consumer disposable income would likely trigger a gradual recovery in leisure flight bookings heading into the spring convention and holiday travel season. Furthermore, high-profile international mega-events, marquee sporting matches, and established annual conventions scheduled in Las Vegas over the next 12 months are expected to provide a reliable baseline of high-spending visitors.
However, if domestic inflationary pressures re-accelerate or personal credit default rates rise across middle-income demographics, the domestic leisure travel contraction could persist into mid-2027. Under this scenario, hospitality operators will face mounting pressure to restructure pricing models, reconsider property fee structures, and re-evaluate capital investment timelines for planned resort expansions. The resort industry’s long-term adaptability, combined with coordinated public policy intervention, will determine whether Southern Nevada can successfully navigate this cyclical downturn and maintain its status as the world’s premier leisure and entertainment destination.
Advertisement
