
South Korea Overtakes Malaysia and All Other Asian Destinations in Witnessing Declining Interest in Thailand Beach Tourism from International Tourists in 2026
Updated
Published
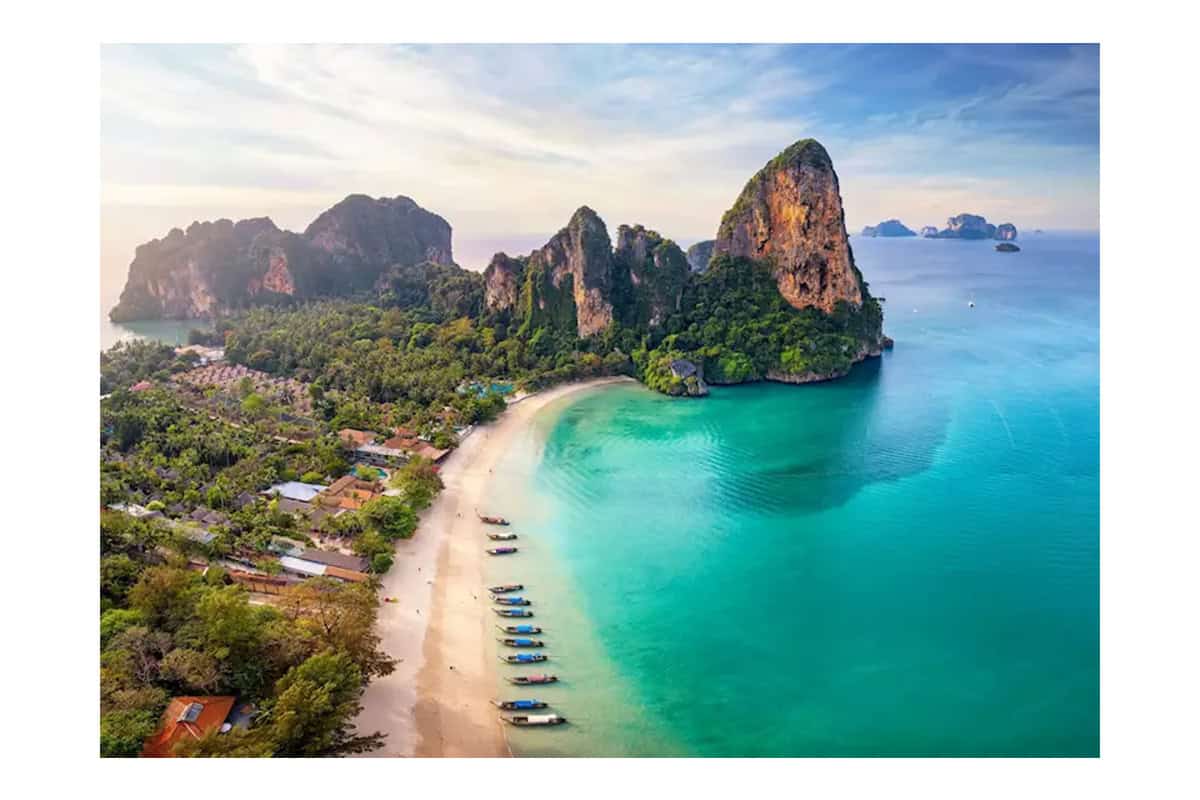
Recent reports from reliable sources have shown that from the 23rd of September, 2026, the tourism industry in Asia has started undergoing noticeable changes. Beach tourism in Thailand has been on the decline. Because of this, travelers have been passing through other countries and avoiding Thailand and other neighboring coastal countries. As of now, various islands in Thailand have been closed off to the public because of various environmental reasons. As a result, the Thai tourism ministry has been working to diversify Thailand’s tourism industry. Various other countries have also been benefitting from this shift. South Korea and Malaysia in particular have recorded a surge in tourists and revenue in the culture and arts sector.
Background: The Historical Dominance of Thai Coastal Destinations
For decades, Thailand has stood as the undisputed powerhouse of Southeast Asian tourism, built largely on the immense global appeal of its pristine beaches, island archipelagos, and world-class coastal hospitality. Destinations such as Phuket, Koh Samui, Krabi, and Pattaya have served as the fundamental pillars of the nation’s tourism-dependent economy. Historically, these regions attracted a diverse mix of international visitors, ranging from budget-conscious backpackers traversing the traditional “banana pancake trail” to ultra-high-net-worth individuals chartering private yachts in the Andaman Sea.
Before the global disruptions of the early 2020s, Thailand consistently ranked among the most visited countries on the planet, with its coastal attractions functioning as the primary magnet. The Thai government, alongside the Tourism Authority of Thailand (TAT), cultivated a masterclass in destination marketing, ensuring that the imagery of long-tail boats docked on white sands became synonymous with the ideal Asian holiday. The hospitality infrastructure expanded relentlessly to accommodate surging demand, resulting in an unprecedented concentration of resorts, coastal entertainment districts, and marine tour operators.
However, this relentless expansion was not without its systemic vulnerabilities. The hyper-concentration of international arrivals in fragile coastal ecosystems began generating severe environmental and infrastructural friction. As the post-pandemic travel rebound peaked and subsequently stabilised, underlying challenges regarding over-tourism, ecological degradation, and shifting global consumer paradigms began to surface, setting the stage for the highly documented Thailand beach tourism decline currently observed in 2026.
Advertisement
Advertisement
Latest Official Developments and the Turning Point in 2026
The narrative of continuous, unbridled growth in Thai coastal arrivals officially fractured in the third quarter of 2026. As of late September 2026, authoritative data published by the Ministry of Tourism and Sports Thailand confirmed a structural cooling in international demand for the nation’s traditional beach resorts. This contraction represents a pivotal moment in Asian tourism trends 2026, marking a definitive transition in how global travellers allocate their leisure capital across the Asia-Pacific region.
Advertisement
Advertisement
During the first eight months of 2026 (January to August), Thailand logged exactly 20,935,135 foreign arrivals. While this figure remains objectively massive, it represents a definitive 3.08% year-on-year decline compared to the corresponding period in 2025. This contraction occurred despite the fact that Thailand’s overall tourism target for the year had been aggressively set by the Ministry of Finance and TAT. Crucially, the decline is most pronounced in the demographics that traditionally fuel the high-yield beach tourism sector, signalling that the Thailand beach tourism decline is not a mere statistical anomaly, but a fundamental realignment of the Asian leisure market.
While total numbers remained somewhat buoyed by a 16.05% year-on-year increase in arrivals from China (totalling 3,543,272 visitors), this growth has largely been concentrated in urban retail hubs and cultural landmarks in Bangkok and Chiang Mai, rather than the coastal provinces. The stark reality facing Thailand’s island economies is that a significant volume of their traditional international base has opted to holiday elsewhere, prompting urgent strategic reviews within the Thai government.
Official Statistics: Analysing the Contraction in Key Source Markets
To understand the precise anatomy of the Thailand beach tourism decline, one must critically examine the performance of its historical core markets. The data from the first eight months of 2026 paints a clear picture of market erosion among key Asian and Western demographics.
Advertisement
Advertisement
The Collapse of the South Korean and Malaysian Inbound Markets
The most alarming metric for Thai tourism officials has been the precipitous drop in arrivals from South Korea and Malaysia. South Korean tourists, historically one of the most reliable demographics for premium coastal resorts in Phuket and Koh Samui, recorded a staggering 24.78% decline, dropping to just 769,930 visitors between January and August 2026.
Similarly, Malaysia, which frequently serves as a massive cross-border and short-haul aviation source market for Southern Thai beach destinations like Krabi and Phuket, saw an 11.87% decline, dropping to 2,658,686 arrivals. These two nations alone represent a catastrophic loss of high-frequency, high-spending regional tourists who are actively choosing to redirect their travel itineraries.
Advertisement
Advertisement
Contractions in the Western and Japanese Markets
The decline is not exclusively restricted to Southeast and East Asian source markets. The United Kingdom, a traditional stronghold for long-haul beach tourism to Thailand, recorded a 3.44% drop, yielding 677,689 visitors. Japan, another high-value market, saw a 5.42% decrease, falling to 665,368 arrivals. Even the Russian market, which had surged in previous years, saw a marginal decline of 0.55%.
These statistically verified contractions confirm that the global appetite for Thai coastal holidays is waning. Travellers from these jurisdictions are increasingly citing environmental fatigue, rising local costs, and a desire for more diverse, climate-resilient cultural experiences as primary reasons for altering their travel patterns.
Environmental Policies and National Park Closures
A critical, highly publicised driver of the Thailand beach tourism decline is the necessary but economically disruptive implementation of environmental preservation policies by the Thai government. Decades of mass tourism have wreaked havoc on Thailand’s marine ecosystems, most notably resulting in severe coral bleaching events driven by rising sea temperatures and sunscreen chemical pollution.
The Department of National Parks, Wildlife and Plant Conservation has been forced to take drastic action in 2025 and 2026 to prevent total ecological collapse in the Andaman Sea and the Gulf of Thailand. High-profile closures of globally renowned sites, including extended recovery periods for Maya Bay and Pling Island, have severely restricted access for marine tour operators. While these closures are unequivocally essential for long-term ecological survival, they have fundamentally degraded the immediate commercial viability of the surrounding beach tourism ecosystems.
International tourists, increasingly conscious of both their environmental footprint and the diminished quality of the marine experience (such as dying coral reefs and overcrowded alternative beaches), are actively voting with their wallets. The promise of pristine tropical waters is increasingly difficult to guarantee, prompting a massive pivot in coastal travel demand Asia.
Advertisement
Advertisement
The Impact of New Entry Policies and Economic Friction
Compounding the environmental deterrents are several newly introduced bureaucratic and economic frictions. In 2026, the Thai government fully implemented its long-debated 300-baht tourist entry fee for international air arrivals, with funds ostensibly earmarked for tourism infrastructure and visitor insurance. Furthermore, the mandatory implementation of the Thailand Digital Arrival Card (TDAC) and the incoming THIM app have added layers of digital bureaucracy that some short-haul travellers find cumbersome.
While these measures are standard practice in many developed nations, they arrived precisely at a time when regional competitors were drastically slashing entry requirements to capture market share. Furthermore, persistent complaints regarding dual-pricing structures (where foreign tourists are charged significantly higher rates than locals for national parks, historical sites, and transport) have gained viral traction on international social media, causing reputational damage that directly fuels the Thailand beach tourism decline.
The Rise of South Korea: K-Culture Overtakes Coastal Escapes
As traditional beach tourism wanes, the most spectacular beneficiary in the region has undeniably been South Korea. Shifting the paradigm from coastal relaxation to hyper-modern cultural immersion, South Korea is rewriting the rules of the Asian travel industry. According to authoritative data released in July 2026 by the Ministry of Culture, Sports and Tourism Korea, the nation welcomed an astonishing 10.71 million foreign visitors in the first half of 2026 alone.
This represents a massive 21% year-on-year increase from 2025. South Korea has successfully commodified its cultural exports—spanning K-Pop, K-Dramas, advanced cosmetics, and high-tech urban experiences—into an irresistible tourism product. The statistics indicate a massive wealth transfer within the Asian travel sector, proving that South Korea international arrivals are cannibalising demographics that previously defaulted to Southeast Asian beaches.
Record-Breaking Tourist Spending
The economic implications of this shift are profound. During the first six months of 2026, foreign visitors in South Korea spent over 10 trillion won (approximately $6.8 billion USD) via card transactions, clearing this massive financial milestone nearly three months earlier than in the previous year. June 2026 alone saw 2.05 trillion won in card spending from 1.99 million foreign arrivals.
Advertisement
Advertisement
Kang Jung-won, head of the Ministry’s tourism policy office, officially attributed this rapid inbound growth to the “irreplaceable appeal of ‘K-culture'” combined with aggressive strategic support from the government. The satisfaction score for foreign tourists in South Korea reached an impressive 90.5 in the second quarter of 2026, up from 89.8 the previous year, highlighting superior service delivery that contrasts sharply with the overcrowding complaints frequently levied against Thai beach destinations.
The Expansion of Regional Hubs: Busan and Jeju
Crucially, South Korea is not solely relying on Seoul to capture the market. A key indicator of their sustainable growth strategy is the aggressive expansion and utilisation of regional airports. Government data from mid-2026 confirms that foreigner utilisation of regional airports (outside of Incheon and Gimpo) surged by an incredible 42.5% year-on-year.
Coastal and cultural cities like Busan, alongside the island province of Jeju, are successfully presenting themselves as viable, high-end alternatives to Southeast Asian beaches. These destinations offer a hybrid model: sophisticated urban infrastructure, pristine temperate coastlines, and rich cultural heritage, completely bypassing the chaotic mass-tourism model that currently plagues parts of Thailand.
Malaysia’s Aggressive Tourism Rebound
Parallel to South Korea’s cultural ascendance, Malaysia has executed a masterstroke in strategic tourism recovery, presenting itself as the premier alternative within Southeast Asia. Taking full advantage of the Thailand beach tourism decline, Malaysia has experienced a monumental surge in arrivals, perfectly positioning itself ahead of its highly anticipated “Visit Malaysia 2026” campaign.
Surging Arrival Statistics and Visa Liberalisation
Official statistics sourced via CEIC Data reveal that Malaysia recorded a massive 2,247,382 visitor arrivals in June 2026 alone, up from 2.06 million in the previous month. This consistent, high-volume growth is largely the result of proactive governance by the Ministry of Tourism, Arts and Culture (MOTAC). Malaysia aggressively pursued visa-free entry agreements for critical high-volume markets, most notably China and India, stripping away the friction that currently hampers Thai arrivals.
Advertisement
Advertisement
While Thailand struggles with the implementation of entry fees and apps, Malaysia has streamlined the border experience. As a result, tourists seeking seamless tropical getaways are increasingly opting for Malaysian shores.
Eco-Tourism and the Reimagining of the Tropical Holiday
Malaysia has deliberately avoided attempting to replicate the Thai mass-beach model. Instead, Tourism Malaysia growth statistics are being driven by a strategic pivot towards high-value eco-tourism, cultural heritage, and luxury medical tourism.
Destinations in Sabah and Sarawak on the island of Borneo offer pristine, strictly regulated environmental experiences that appeal directly to the ecologically conscious demographic currently abandoning Thai beaches. Similarly, the coastal enclaves of Langkawi and Penang offer rich culinary and historical overlays that elevate the standard beach holiday into a multifaceted cultural experience. Malaysia’s ability to offer pristine coastlines without the severe overcrowding seen in Phuket or Pattaya has been a decisive factor in its 2026 market capture.
Industry Impact Across the Southeast Asian Region
The reverberations of the Thailand beach tourism decline are forcing a massive recalibration within the regional hospitality and aviation sectors. International hotel conglomerates are actively reassessing their capital expenditure pipelines for 2027 and 2028. While greenfield luxury developments in Thai coastal provinces face heightened scrutiny and potential delays, capital is rapidly flowing into urban South Korean projects and Malaysian eco-resorts.
Hospitality Sector Realignment
In destinations like Koh Samui and Krabi, independent hoteliers and mid-tier resort operators are reporting alarming drops in forward bookings for the late 2026 high season. To survive, many are being forced into aggressive discounting strategies, which inevitably compresses yield and degrades the overall quality of service. Conversely, hotels in Kuala Lumpur, Penang, Seoul, and Busan are commanding record-high Average Daily Rates (ADR) and Revenue Per Available Room (RevPAR).
Advertisement
Advertisement
The shift is forcing Thai hoteliers to pivot their marketing efforts toward the domestic market. Domestic tourism in Thailand remains robust, with over 202 million domestic trips projected for the year, largely sustained by government stimulus measures and co-payment schemes. However, domestic tourists yield significantly lower per-capita spending compared to international long-haul visitors, meaning the revenue gap left by the international beach tourism decline cannot be fully bridged internally.
Aviation and Route Reallocations
Regional aviation is responding to these Southeast Asia travel shifts with ruthless efficiency. Airlines are highly sensitive to load factors and yield, and 2026 has seen a notable reallocation of wide-body and high-frequency narrow-body capacity. Flights connecting secondary Chinese and South Korean cities directly to Thai coastal airports (like Phuket International) are seeing capacity reductions or being downgraded to smaller aircraft.
Simultaneously, route planners are flooding capacity into South Korea and Malaysia. The 42.5% increase in regional airport usage in South Korea is a direct result of airlines opening new direct routes to Busan and Jeju, bypassing traditional Southeast Asian beach hubs entirely.
Economic Implications for the Host Nations
The macroeconomic implications of this geopolitical shift in tourism are profound. For Thailand, a country where tourism historically accounts for upwards of 12% to 14% of gross domestic product (GDP), the Thailand beach tourism decline represents a tangible threat to national economic stability.
The Ministry of Tourism and Sports projects that full-year tourism revenue in 2026 will hover near the 2025 levels of 2.7 trillion baht, entirely avoiding a contraction only because of the inflation of prices and the increased spending of the Chinese urban-tourist demographic. However, the distribution of this wealth is heavily skewed away from the coastal provinces that desperately rely on it, threatening localized recessions in regions solely dependent on marine tourism.
Advertisement
Advertisement
Conversely, the wealth transfer to northern and maritime Southeast Asia is accelerating national development goals. South Korea’s 10 trillion won in H1 tourist card spending provides massive liquidity to its retail, hospitality, and cultural sectors. Malaysia’s booming arrival numbers are providing the crucial foreign exchange required to fund the infrastructure projects associated with the Visit Malaysia 2026 initiative, creating a virtuous cycle of investment and attraction.
Tourism, Business, and Public Impact
At the granular level, the human and business impacts of these shifting tides are stark. In Thai coastal towns, local economies—spanning taxi syndicates, independent restaurant operators, dive shops, and street vendors—are facing a severe liquidity crunch. The combination of fewer high-spending Western and Korean tourists, coupled with high domestic inflation, is placing immense strain on the coastal working class.
In stark contrast, the public sentiment and business environment in the beneficiary nations are overwhelmingly positive. South Korean citizens are witnessing a global validation of their cultural exports, driving immense national pride and localized economic booms in secondary cities. Malaysian businesses are experiencing a renaissance of entrepreneurial opportunity, heavily supported by government grants designed to elevate the tourism product ahead of the impending Visit Malaysia 2026 influx.
Official Statements and Expert Analysis
Official rhetoric from the respective nations highlights their divergent trajectories. The Thai government maintains a brave public face, with TAT officials noting that reaching 21 million visitors by September proves the resilience of the overall Thai brand. They emphasise a deliberate transition toward “quality over quantity,” actively encouraging the Thailand beach tourism decline in the lowest-yield sectors to protect the environment. However, private sector analysts suggest this rhetoric masks deep anxiety regarding the loss of market share to regional competitors.
Meanwhile, global bodies like UN Tourism (formerly UNWTO) have highlighted the changing dynamics of the Asia-Pacific region. Experts note that modern travellers are highly informed, digitally connected, and deeply intolerant of perceived poor value or environmental degradation. South Korea and Malaysia are routinely cited in 2026 industry white papers as textbook examples of adaptive, forward-thinking destination management.
Advertisement
Advertisement
Future Outlook: The Reshaping of Asian Travel by 2027
Looking ahead to late 2026 and 2027, the trajectory is irrevocably set. The Thailand beach tourism decline is not a temporary blip, but a permanent structural realignment of the Asian tourism market. As global temperatures continue to rise, tropical coastal destinations will face increasing pressure to balance environmental survival with commercial viability.
Thailand’s future success will rely heavily on its ability to diversify its offerings beyond the beach. Medical tourism, gastronomy, and historical exploration in the northern provinces must step up to replace the revenue lost from the declining coastal sector. Thailand possesses the cultural depth to achieve this, but the transition period will be economically painful for its southern provinces.
For South Korea and Malaysia, the challenge will shift from market capture to capacity management. As their popularity surges, they must vigilantly guard against the very over-tourism and environmental degradation that sparked the exodus from Thailand. By maintaining strict quality controls, investing heavily in regional infrastructure, and continually innovating their cultural and eco-tourism products, South Korea and Malaysia are poised to dominate the next decade of Asian travel, permanently altering the map of global tourism.
Advertisement
