
Netherlands Resets Travel Economics as Long Haul Flight Tax Relief Meets New Sustainable Fuel Funding
Updated
Published
The Netherlands is entering 2027 with an aviation-cost structure far more complex than a straightforward flight-tax reduction. A distance-based tax will replace the current €30.25 flat rate, while the government is proposing to reduce only the planned long-haul band from €74.81 to €59.43. Medium-haul departures would still rise to €49.87, transfer passengers remain outside the Dutch tax base, and parallel SAF measures are targeting both airline fuel uptake and domestic sustainable-fuel production.
Netherlands 2027 Flight Tax Is Not a Simple Passenger Tax Cut
The most important point for travellers, airlines and travel sellers is that the Netherlands is not reducing air passenger tax across the board.
Advertisement
Advertisement
According to the Dutch government’s official aviation-tax information, passengers departing a Dutch airport currently face a uniform tax of €30.25 in 2026. From 1 January 2027, an already enacted distance-based system introduces separate short-, medium- and long-distance bands.
The government has subsequently proposed changing only the highest band. The long-haul rate had been scheduled to reach €74.81, after indexation, but the Belastingplan 2027 proposes lowering it to €59.43. That amendment still requires parliamentary approval.
Advertisement
Advertisement
This distinction matters because €59.43 remains considerably above the €30.25 charged on every taxable departure in 2026.
| Dutch air passenger tax | 2026 | Previously scheduled 2027 | Current 2027 proposal | Change versus 2026 |
|---|---|---|---|---|
| Short distance | €30.25 | €31.04 | €31.04 | +€0.79 |
| Medium distance | €30.25 | €49.87 | €49.87 | +€19.62 |
| Long distance | €30.25 | €74.81 | €59.43 | +€29.18 |
The resulting increases against the 2026 flat rate are approximately 2.6 per cent for short-haul, 64.9 per cent for medium-haul and 96.5 per cent for long-haul under the latest proposal. The proposed long-haul amendment nevertheless cuts €15.38, or about 20.6 per cent, from the rate that had otherwise been scheduled for 2027. The underlying official rate figures are published by the Dutch government and Netherlands Enterprise Agency.
Advertisement
Advertisement
Legal Status Is Crucial for 2027 Travel Planning
The distance-based system itself is not merely an aspiration. The Dutch Wet differentiatie vliegbelasting was adopted by both chambers of parliament in December 2025, published on 23 December 2025 and is due to take effect on 1 January 2027.
What remains a proposal as of 3 October 2026 is the new reduction of the indexed long-haul rate from €74.81 to €59.43.
According to the Dutch government’s Belastingplan 2027 information, the new package still requires consideration by the Tweede Kamer and Eerste Kamer. The government expects parliamentary decisions during the remaining 2026 budget process.
Travel businesses should therefore distinguish between the confirmed 2027 distance-based architecture and the still-pending amendment to its highest rate.
The Overlooked Rule Is That Final Destination Determines the Tax
A less visible provision could matter almost as much as the headline rates.
According to the Dutch government, the distance category is determined using the passenger’s final destination, including journeys involving an intermediate connection. The bands are structured around distance from Amsterdam, with European Union destinations and journeys of roughly up to 2,000 kilometres generally falling into the short category, destinations approximately 2,000 to 5,500 kilometres away entering the medium category, and longer journeys entering the highest band.
Advertisement
Advertisement
That means an itinerary starting in the Netherlands does not automatically receive the tax associated with its first flight sector.
The government specifically identifies Egypt and Türkiye as examples of medium-distance destinations and Canada, Mexico, Indonesia and South Africa as long-distance examples. Certain territories, including Aruba, Curaçao, Sint Maarten, Bonaire, Saba and Sint Eustatius, receive the lower rate despite their geographical distance because of their constitutional relationship with the Kingdom of the Netherlands.
| Passenger situation | Dutch flight-tax treatment |
|---|---|
| Passenger starts a taxable journey at a Dutch airport | Tax applies |
| Journey includes an onward connection | Final destination determines distance band |
| International traveller merely transfers at a Dutch airport | Transfer passenger remains exempt |
| Child younger than two | Excluded from taxable passenger count |
| Flight crew | Excluded |
| Certain Caribbean Kingdom destinations | Lower band applies under the statutory exception |
The Netherlands Tax Administration confirms that transfer passengers are excluded from the tax, alongside flight crew and children under two.
Transfer Exemption Creates a Different Cost Exposure for Hub Traffic
This is where the 2027 policy becomes particularly significant for aviation economics.
A passenger beginning a taxable long-distance journey in the Netherlands could face the proposed €59.43 tax. A passenger whose international journey merely connects through a Dutch airport remains outside the Dutch passenger-tax base.
That distinction matters because connecting traffic is not marginal to the Dutch aviation system.
Advertisement
Advertisement
According to Schiphol’s official 2025 traffic figures, 68.8 million travellers used the airport during the year. Of these, 43.6 million travelled directly to or from Schiphol, while 25.2 million had a connecting flight. Schiphol directly connected the Netherlands with 301 destinations, including 125 intercontinental points.
During the first half of 2026, another 32.7 million passengers travelled to, from or through Schiphol despite weather disruption and geopolitical pressures on aviation networks.
The scale of connecting traffic makes the transfer exemption commercially important. It means the Dutch tax is structurally more exposed to passengers beginning their journeys in the Netherlands than passengers moving through its principal hub.
Exclusive Analysis: The Real 2027 Divide Is Origin Traffic Versus Connecting Traffic
The most consequential feature of the 2027 system may therefore be less about short-haul versus long-haul flying than about where the passenger begins the journey.
For locally originating passengers, the Netherlands is making distance a stronger determinant of the tax component embedded in the fare. The medium-haul increase is particularly notable because that band receives no new September 2026 relief. Its €49.87 rate is almost €20 above the current flat charge.
Long-haul travellers receive relief only against the previously scheduled 2027 level, not against 2026.
Advertisement
Advertisement
Connecting passengers occupy a different position. Their exemption helps preserve the economics of using the Netherlands as a European transfer hub even as origin passengers become subject to differentiated rates.
This does not establish that passengers will switch airports or airlines. Fare decisions depend on base fares, airport charges, fuel, competition, capacity and network availability. What it does establish is that the statutory tax burden is distributed unevenly across different passenger flows.
For travel managers and tour operators, itinerary structure will therefore become more relevant to interpreting the tax component of Dutch departures.
€90 Million SAF Fund Adds a Second Layer to the Aviation Cost Reset
Passenger taxation is only one side of the Netherlands’ emerging 2027 aviation policy.
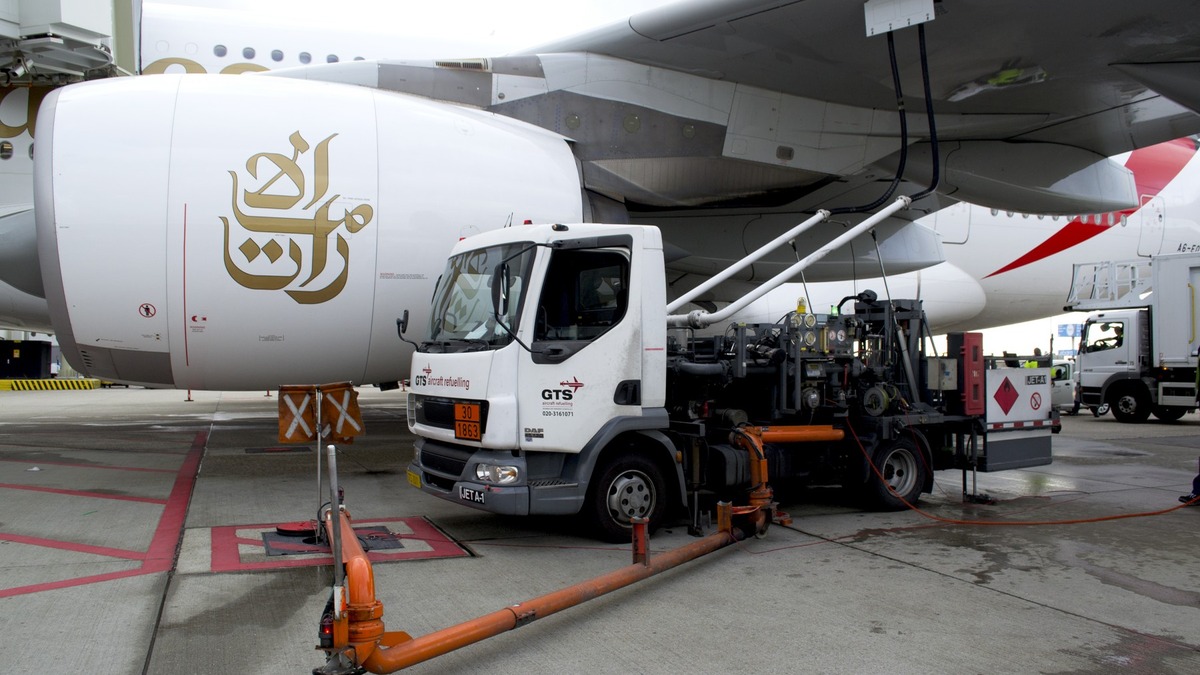
According to the Dutch Ministry of Infrastructure and Water Management, the government has reserved €45 million for a Sustainable Aviation Fuel incentive fund being developed with Schiphol. Schiphol is expected to provide another €45 million, bringing intended funding to €90 million for 2027–2029.
The fund has a very specific design.
Advertisement
Advertisement
Airlines would receive support for SAF blended above the European regulatory obligation, rather than for fuel they are already required to use. The Dutch government contribution remains conditional on European Commission approval.
That distinction prevents the initiative from being confused with a new passenger charge or an automatic airline subsidy.
It is an incentive aimed at additional sustainable-fuel consumption beyond the mandatory baseline.
EU SAF Rules Explain Why Above-Mandate Funding Matters
ReFuelEU Aviation already requires aviation-fuel suppliers at covered EU airports to meet a minimum 2 per cent SAF share from 2025. The mandated share rises to 6 per cent in 2030, with progressively higher requirements thereafter.
The new Dutch-Schiphol fund therefore targets consumption that goes beyond an existing European regulatory floor.
Schiphol identifies cost as one of the main barriers to faster SAF adoption. Its institutional sustainability information states that the fuel is currently almost three times more expensive than conventional kerosene and remains limited in availability. Its previous SAF incentive programme between 2022 and 2024 helped participating airlines use more than 40,000 tonnes.
Advertisement
Advertisement
| SAF policy layer | Scale | Purpose | Status as of 3 October 2026 |
|---|---|---|---|
| ReFuelEU Aviation | 2% minimum SAF share from 2025 | EU regulatory baseline | In force |
| ReFuelEU 2030 requirement | 6% minimum SAF share | Higher EU blending requirement | Legislated |
| Dutch government contribution to new SAF fund | €45 million | Support above-mandate airline use | Subject to EC approval |
| Schiphol contribution | €45 million | Match government funding | Planned |
| Combined Schiphol SAF incentive | €90 million | 2027–2029 additional SAF uptake | Planned |
| Dutch SAF production and scale-up support | €300 million | e-SAF and advanced bio-SAF production | First subsidy decisions expected in 2027 |
A Further €300 Million Targets the Supply Side
The 2027 Dutch infrastructure budget reveals another layer that substantially broadens the sustainability story.
According to the official 2027 budget of the Ministry of Infrastructure and Water Management, €300 million from the Climate and Energy Fund is being invested in the production and scaling of sustainable aviation fuels, including e-SAF and advanced bio-SAF produced through Alcohol-to-Jet technology. The first subsidy decisions are expected in 2027.
This should not automatically be added to the €90 million Schiphol fund and presented as one combined programme because the mechanisms, beneficiaries and budget structures differ.
They can, however, be understood as complementary interventions.
The €90 million initiative primarily targets airline demand above the EU mandate. The €300 million programme targets fuel production and industrial scale-up.
That gives the Netherlands a two-sided SAF strategy entering 2027: stimulate additional consumption while simultaneously attempting to expand the production base.
Advertisement
Advertisement
Why Airlines Face More Than One Cost Signal
Airlines operating in the Netherlands will consequently enter 2027 facing several policy signals at once.
The ticket-tax system increases the passenger-tax component for medium- and long-distance originating journeys. The proposed amendment softens the highest band relative to what had already been scheduled. Transfer traffic remains exempt. Meanwhile, targeted public and airport funding seeks to reduce part of the economic hurdle involved in using more SAF than EU rules require.
Airport charges form another separate cost category.
Schiphol previously established a charging programme under which its airline charges rise substantially over the 2024–2027 period, although the scheduled annual charge movement for 2027 itself is downward compared with 2026. The airport has also been operating a temporary daytime-flight discount through 31 March 2027 in response to exceptional fuel-cost pressures.
Travel sellers should therefore avoid treating passenger tax as a direct forecast of total ticket-price movements.
What Travel Agents and Tour Operators Should Do Before 2027
- Separate enacted law from the pending amendment. The distance-based structure is scheduled for 1 January 2027, while the €59.43 long-haul rate still depends on the Belastingplan 2027 legislative process.
- Budget medium-haul itineraries carefully. The current proposal leaves the €49.87 medium-distance rate unchanged.
- Do not describe €59.43 as a reduction from 2026. It is lower than the previously scheduled 2027 long-haul rate but higher than the current €30.25 charge.
- Check final destinations rather than first sectors. Connecting itineraries originating in the Netherlands are categorised according to final destination.
- Distinguish transfers from Dutch-origin departures. Genuine transfer passengers remain outside the Dutch air passenger tax.
- Avoid guaranteeing fare increases equal to the tax movement. Airlines determine complete fares using multiple commercial and operating inputs.
- Do not present the €90 million SAF fund as confirmed passenger funding. It targets airlines blending above the EU mandate and the government contribution requires European Commission approval.
- Monitor parliamentary decisions before publishing final 2027 packages. Tax assumptions should be updated once the Belastingplan process is complete.
Netherlands Is Shifting From One Aviation Price Signal to a More Complex Policy Architecture
The Netherlands’ 2027 aviation transition is becoming substantially broader than the flight-tax increase first outlined in 2025.
Advertisement
Advertisement
The country is moving from one uniform passenger levy to three distance-linked rates, proposing relief against the previously scheduled long-haul level, maintaining an exemption that protects transfer traffic, supporting airlines that consume SAF beyond European requirements and preparing major production-side investment in sustainable aviation fuels.
That combination creates different implications for locally originating travellers, transfer passengers, airlines, airports, fuel producers and travel intermediaries.
The central traveller message is therefore precise: 2027 does not bring a general Dutch flight-tax reduction. Medium- and long-distance originating journeys remain substantially more heavily taxed than in 2026 under the current policy path.
The broader industry message is more strategic. The Netherlands is simultaneously attempting to preserve international aviation competitiveness and accelerate aviation decarbonisation by moving some policy support towards targeted fuel incentives rather than relying on passenger taxation alone.
Whether that balance materially changes fares, airline capacity or passenger behaviour cannot yet be established. But from 1 January 2027, the structure governing the cost of departing the Netherlands will become markedly more differentiated than it is today.
Advertisement
