
Airlines in Travel Sector Under Spotlight as easyJet Faces Market Pressure, Investor Concerns, UK Aviation Scrutiny and Intensifying European Low-Cost Flight Competition
Updated
Published
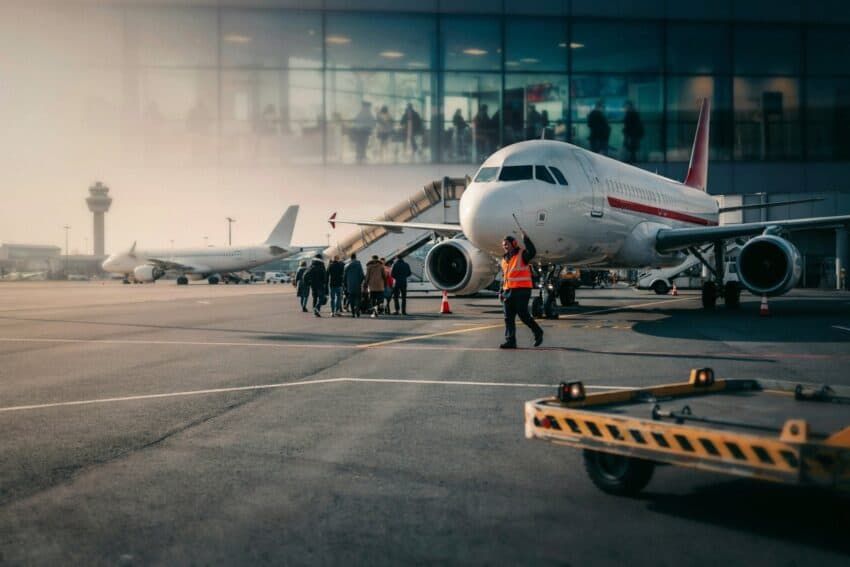
The European aviation sector is under renewed scrutiny as easyJet, one of the continent’s largest low-cost carriers, becomes a focal point for investor debate, policy discussion, and competitive pressure in 2026. According to market analysis reported by official airline regulatory disclosures and London Stock Exchange filings, the airline continues to operate at scale across Europe but faces a shifting competitive landscape.
The situation reflects broader structural challenges affecting low-cost airlines, including rising operating costs, intensified competition from Ryanair and Wizz Air, and tighter demand cycles in key UK and EU travel corridors.
The UK government’s transport policy framework, combined with Civil Aviation Authority (CAA) monitoring of airline performance standards, has placed additional attention on reliability, consumer protection, and operational resilience across major carriers such as easyJet.
European Airline Competition Intensifies Across Key Travel Hubs
easyJet’s operational footprint remains heavily concentrated in high-demand airports such as London Gatwick, Amsterdam Schiphol, Geneva, Milan, and Paris Charles de Gaulle. These hubs are among the most slot-constrained airports in Europe, as confirmed by aviation infrastructure datasets from EUROCONTROL and European Commission aviation capacity reports.
Advertisement
Advertisement
However, the airline is operating in an environment of increasing pressure from rival carriers expanding aggressively across short-haul European routes.
Key competitive developments shaping the market:
Advertisement
Advertisement
- Ryanair expanding capacity across UK–EU leisure routes
- Wizz Air strengthening Central and Eastern European connectivity
- Jet2 increasing UK leisure dominance at Gatwick and Manchester
- Legacy carriers reclaiming short-haul market share in select hubs
This intensifying competition has reduced easyJet’s relative market share in Europe, even as total seat capacity continues to grow across the sector.
The UK Civil Aviation Authority continues to emphasise consumer protection standards under UK261 regulations, which mirror EU passenger rights frameworks for delays and cancellations.
Advertisement
Advertisement
UK Travel Policy and Aviation Governance Shape Industry Direction
In Westminster, aviation policy debates increasingly focus on passenger rights, airport capacity expansion, and environmental transition targets aligned with the UK Department for Transport’s net-zero aviation roadmap.
Key regulatory priorities influencing airlines like easyJet include:
- Strengthening passenger compensation frameworks under UK261
- Expanding Heathrow, Gatwick, and regional airport capacity planning
- Supporting Sustainable Aviation Fuel (SAF) adoption targets
- Monitoring airline punctuality and cancellation performance
The Department for Transport’s long-term aviation strategy highlights the need for resilience in short-haul networks, particularly as UK leisure travel demand continues to rise post-pandemic recovery.
This regulatory backdrop creates both opportunity and pressure for airlines. While demand remains strong, compliance obligations and sustainability requirements increase operating complexity.
Advertisement
Advertisement
Structural Cost Pressures Continue to Affect Budget Airline Models
Low-cost carriers across Europe are adapting to persistent cost inflation driven by fuel volatility, airport charges, labour constraints, and aircraft delivery delays.
According to IATA industry financial outlook reports, airlines globally continue to face:
- Elevated fuel cost volatility linked to global energy markets
- Supply chain delays affecting fleet expansion timelines
- Rising airport infrastructure charges in major EU hubs
- Labour shortages in ground handling and air traffic systems
These pressures directly impact airline yield management strategies, forcing carriers like easyJet to adjust pricing models and route optimisation planning.
In the UK, aviation stakeholders including Heathrow Airport Limited and Gatwick Airport Limited have also highlighted the need for infrastructure investment to prevent long-term congestion bottlenecks.
easyJet’s Network Strategy Focuses on High-Density European Routes
Despite market challenges, easyJet continues to maintain a strong presence across major European leisure and business corridors. Its network strategy is focused on high-density routes linking UK airports with key European destinations such as Spain, France, Italy, and Portugal.
Official company filings show that easyJet’s operational model relies heavily on:
Advertisement
Advertisement
- High aircraft utilisation rates
- Point-to-point short-haul connectivity
- Seasonal demand concentration during summer travel peaks
- Strong base operations at Gatwick, Luton, and key EU airports
However, aviation analysts note that high utilisation also reduces operational flexibility, making the airline more vulnerable to cascading delays during peak demand periods or disruptions.
This structural model remains efficient in stable conditions but creates pressure during periods of operational strain.
Investor Sentiment Reflects Mixed Outlook for Airline Growth
Market sentiment toward easyJet reflects both confidence in its scale and caution regarding its long-term margin stability. Recent filings on the London Stock Exchange indicate investor interest in airline consolidation trends across Europe.
Key investor considerations include:
- Potential consolidation opportunities in the low-cost segment
- Impact of geopolitical instability on fuel and insurance costs
- Demand resilience across UK outbound tourism markets
- Exposure to currency fluctuations affecting Eurozone revenues
The airline remains a significant player in European aviation, but analysts continue to evaluate whether scale advantages can offset structural cost challenges over the next cycle.
Outlook for 2026 European Aviation Market
The wider European aviation industry is expected to remain highly competitive throughout 2026, supported by strong leisure travel demand and gradual recovery in business travel.
Advertisement
Advertisement
However, key risks remain:
- Capacity constraints at major airports
- Regulatory tightening around emissions
- Labour and operational cost inflation
- Intensifying price competition among low-cost carriers
For airlines such as easyJet, strategic resilience will depend on balancing network expansion with operational reliability and cost control discipline.
Conclusion
The current environment places easyJet at the intersection of policy scrutiny, investor attention, and structural industry transformation. While demand for travel across Europe remains strong, the competitive and regulatory landscape is becoming increasingly complex.
The UK’s aviation policy direction, combined with European market competition and global cost pressures, is shaping a new phase of airline industry evolution in 2026. easyJet’s ability to adapt its network efficiency, maintain reliability, and sustain profitability will determine its positioning in this rapidly changing travel ecosystem.
Advertisement
