

Long Island Tourism Faces a US Affordability Squeeze as Housing Costs Could Take Until 2031 to Normalise
Published
America’s housing affordability crisis could reshape more than homeownership, with implications for tourism workers, destination economies and domestic travel spending through 2031. A new Redfin analysis, reported on 12 October 2026, suggests that national housing costs may not return to their August 2018 affordability benchmark until 2031 under a favourable scenario. Long Island and several major metropolitan areas could face a recovery lasting at least another decade. For travel businesses, the concern extends beyond property prices. Persistent housing pressures may influence workforce availability, operating costs and the financial flexibility of households planning holidays. However, these tourism effects remain potential consequences, not outcomes directly measured by Redfin.
The findings arrive as American tourism continues to generate substantial economic activity. The US National Park Service recorded 331.9 million recreational visits in 2024, while nearby communities received $29 billion in visitor spending. Consequently, housing affordability deserves closer attention from destination managers, hospitality operators and travel planners, particularly in expensive coastal markets.
Long Island’s Visitor Economy Faces a Housing Affordability Test
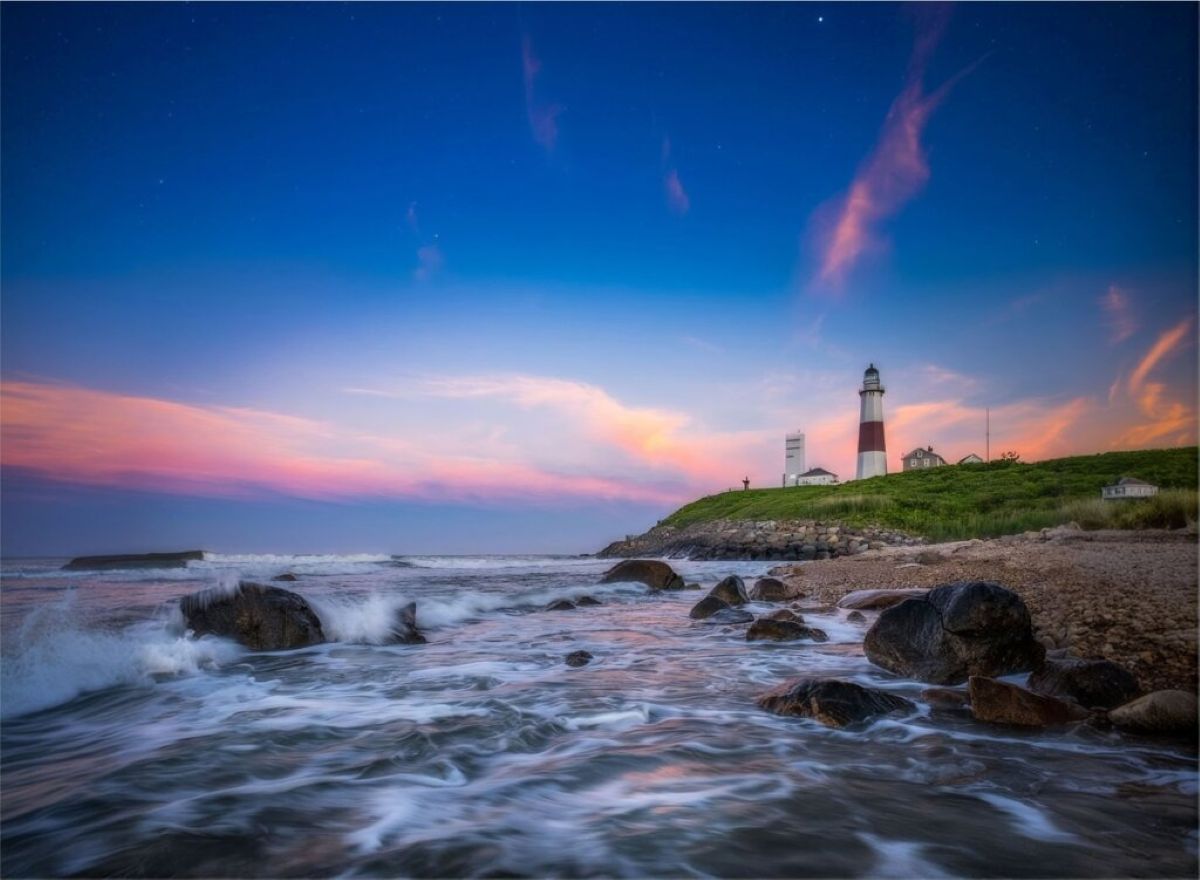
Long Island offers a compelling case study because tourism already represents a significant economic pillar. The region combines Atlantic beaches, waterfront communities, museums, golf courses, vineyards and coastal recreation. Its proximity to New York City also makes it attractive for day trips, weekend breaks and longer leisure stays.
New York State’s tourism industry recorded $7.9 billion in direct visitor spending on Long Island in 2024, according to the state’s economic impact report. Tourism supported 78,418 jobs across the region, including direct, indirect and induced employment. Visitor spending also generated $4.1 billion in personal income and substantial tax revenue.
Advertisement
Advertisement
More recent figures indicate continued expansion. Discover Long Island reported $8.4 billion in visitor spending during 2025, an increase of 6.3% from 2024. Tourism sustained 80,274 jobs and generated $989 million in state and local taxes, according to data released in August 2026.
These figures underline the stakes for the regional visitor economy. If housing costs continue to outpace earnings, some tourism employees could struggle to live near their workplaces. Employers may then face recruitment and retention difficulties, particularly in accommodation, food services, attractions and seasonal hospitality.
Advertisement
Advertisement
Nevertheless, the available figures do not establish that housing costs have already reduced tourism employment or visitor numbers. They identify a structural risk that destination planners and hospitality businesses should assess alongside wage growth, accommodation costs and transport access.
What the 2031 Projection Means for Travel
Redfin’s analysis examines 46 major US metropolitan areas and models different combinations of mortgage rates, house-price growth and projected income gains. Its national scenario assumes mortgage rates fall to 6%, while annual house-price growth remains at 2.1%. Under those conditions, housing costs could return to their August 2018 affordability benchmark by 2031.
That benchmark measures monthly housing payments against household income. Redfin uses a 30% income threshold, including mortgage principal and interest, property taxes and insurance, with a 20% deposit. Therefore, the projected recovery concerns the relationship between housing payments and earnings, not a return to historically low property prices.
The analysis offers other scenarios, too. If mortgage rates remain at 7.5% but prices stop rising, affordability could recover by April 2032. A more optimistic combination of 6% mortgage rates and flat prices could bring recovery forward to February 2029.
| Housing affordability scenario | Assumptions | Projected national recovery |
|---|---|---|
| More favourable scenario | Mortgage rates at 6%; annual house-price growth of 2.1% | 2031 |
| Higher-rate scenario | Mortgage rates at 7.5%; house prices remain flat | April 2032 |
| Optimistic scenario | Mortgage rates at 6%; house prices remain flat | February 2029 |
For tourism businesses, the importance lies in the wider economic environment rather than the dates alone. Household expenditure on travel competes with rent, mortgages, transport, food and other essential costs. Buyers facing prolonged financial pressure may postpone discretionary holidays, shorten stays or choose less expensive destinations.
However, homeownership affordability and holiday affordability are not interchangeable measures. A household unable to buy a property may still travel regularly, while a homeowner may reduce leisure spending because of mortgage costs. Tourism operators should therefore avoid treating Redfin’s projections as direct forecasts of visitor demand.
Advertisement
Advertisement
Rising Travel Costs Add Another Pressure
Housing is only one part of the affordability picture. Travellers also face changing prices for transport, accommodation, fuel, meals and activities. The latest available US Travel Association Travel Price Index figures provide a useful comparison.
In August 2026, the index stood 7.4% above August 2025 and 29.9% above its 2019 level. Airfares were 23.4% higher year on year, while hotel prices rose 2.9%. Motor fuel prices increased 4.1% during the month, according to the association’s September release.
These movements show why a single affordability measure cannot explain every travel decision. Accommodation prices have risen much less than some other categories, but transport costs can still increase the overall expense of a holiday. Consequently, households facing housing pressure may look more closely at travel dates, journey length and destination choice.
| Indicator | Latest reported figure | Potential relevance to travellers |
|---|---|---|
| US travel prices | 7.4% higher year on year | Overall trip budgets face continued pressure |
| Airfares | 23.4% higher year on year | Flight timing and route selection become more important |
| Hotel prices | 2.9% higher year on year | Accommodation inflation remains comparatively moderate |
| Motor fuel | 4.1% monthly increase | Road-trip costs can change quickly |
| Overall travel prices versus 2019 | 29.9% higher | Travellers may need larger budgets than before the pandemic |
Figures refer to August 2026 and are based on the US Travel Association’s Travel Price Index release. Changes cover different comparison periods.
The distinction matters for travel advisers and tour operators. A customer may face a higher mortgage payment without encountering a comparable increase in hotel prices. Yet the combined effect of housing, transport and everyday expenses can narrow the amount available for discretionary travel.
Tourism Workers Could Face Longer Commutes
The workforce question may prove especially important for destinations that depend on local employees. Hotels, restaurants, visitor attractions and transport providers need staff who can reach workplaces reliably, including during early shifts, late evenings and peak holiday periods.
Advertisement
Advertisement
When nearby housing becomes less affordable, workers may seek accommodation farther from employment centres. Longer commutes can increase transport expenses and reduce the practical appeal of jobs with modest wages. For seasonal businesses, these pressures could complicate recruitment during busy periods.
The US travel industry has considerable economic weight. The US Travel Association estimates that travel supported 15 million American jobs and generated $1.4 trillion in travel spending in 2025. The industry also contributed $3 trillion in total economic output.
These national figures illustrate the scale of the sector, although they do not establish how many travel workers face housing insecurity. The potential consequences vary considerably between destinations, depending on local wages, transport networks, housing supply and employment patterns.
For tourism employers, workforce housing deserves attention alongside staffing, training and service quality. Partnerships with local authorities, improved public transport and appropriate housing development could help destinations retain employees. Businesses should also examine whether pay and working arrangements remain competitive against the total cost of living.
National Parks Demonstrate Tourism’s Economic Value
America’s national parks offer another perspective on the relationship between visitors and local communities. Their economic contribution demonstrates why destination affordability involves residents and workers, not just tourists.
The National Park Service recorded 331.9 million recreational visits in 2024, up 2% from 2023. Visitors spent an estimated $29 billion in nearby gateway communities, an annual increase of 10%. That spending supported 340,100 jobs and generated $56.3 billion in economic output nationwide.
Advertisement
Advertisement
Lodging recorded the largest direct contribution among the reported sectors, generating $11.1 billion in economic output. Restaurants followed with $5.7 billion. These figures demonstrate how visitor expenditure supports businesses beyond park entrances, including accommodation providers, restaurants and other local services.
However, the national park data do not show that housing costs are reducing visits or employment. Instead, they establish the economic importance of communities that host tourism activity. If housing pressures make it harder for workers to remain in these areas, destination managers may need to consider affordability as part of long-term tourism planning.
The broader lesson extends to beach resorts, wine regions and smaller heritage destinations. Successful tourism requires more than attractive scenery and visitor marketing. It also depends on functioning communities, accessible services and a workforce able to live within reasonable travelling distance.
What Travellers Should Consider Before Booking
For visitors, the housing projections do not mean holidays will become unaffordable until 2031. Nor do they indicate that Long Island hotels will necessarily raise prices because of the property market. Travellers should assess actual fares, accommodation rates and transport options when planning individual trips.
Long Island remains accessible from New York City, with the Long Island Rail Road serving communities across the region. Nassau County’s official visitor information highlights its beaches, museums, restaurants, golf courses and outdoor recreation. The county also promotes its proximity to Manhattan as a practical advantage for visitors
Travellers can compare rail fares with car-hire costs before choosing an itinerary. They should also check seasonal accommodation rates, parking charges and local transport connections. For beach holidays and weekend breaks, travelling outside peak periods may offer more flexibility, although savings depend on actual availability and demand.
Advertisement
Advertisement
The following comparison can help visitors assess the practical implications without confusing property-market projections with travel prices.
| Travel consideration | Practical approach | Why it matters |
|---|---|---|
| Flights | Compare dates and nearby airports | Airfare changes can materially affect the total trip budget |
| Accommodation | Check several locations and booking dates | Prices vary by season, demand and proximity to attractions |
| Transport | Compare rail, public transport and car-hire costs | Longer journeys can offset cheaper accommodation |
| Dining | Review restaurant prices before arrival | Food is a significant component of many holiday budgets |
| Trip duration | Compare a short break with a longer stay | Total expenditure depends on both daily costs and length of stay |
For international visitors, exchange rates and visa requirements add further considerations. These factors should be assessed separately because the Redfin analysis does not measure their effect on overseas travel demand.
Tourism Leaders Need a Broader Affordability Strategy
The outlook also has implications for destination marketing organisations and public authorities. Marketing campaigns can increase visitor interest, but sustained growth requires sufficient accommodation, transport capacity and a reliable workforce. Housing availability should therefore feature in wider destination planning, particularly in high-cost coastal communities.
Long Island’s latest tourism figures demonstrate that strong visitor spending can coexist with a challenging housing market. Its reported $8.4 billion in 2025 visitor spending represents a substantial economic opportunity. Yet maintaining that momentum will require businesses and public agencies to monitor staffing pressures, local infrastructure and the distribution of tourism benefits.
Industry analysis should also distinguish between short-term visitor demand and long-term structural risks. The US Travel Association reported that domestic travel spending supported growth in August 2026, even as short-term rental demand declined. Hotel demand increased modestly, highlighting the different trajectories of accommodation segments.
That divergence reinforces the need for detailed market monitoring. Destination managers should track hotel occupancy, average daily rates, tourism employment, wages and local housing conditions together. Such evidence can help identify emerging constraints before they undermine service standards or community support for tourism.
Advertisement
Advertisement
Affordable Destinations Will Need Resilience
America’s housing affordability outlook presents a potential challenge for the wider visitor economy, but it does not predict a nationwide tourism downturn. Redfin’s projections concern homeownership costs, while travel demand depends on a wider combination of household finances, prices, employment and consumer confidence.
For Long Island, the stakes are particularly visible because tourism supports thousands of jobs and billions of dollars in visitor spending. The region’s long-term competitiveness will depend partly on whether residents and employees can continue to participate in the economy that visitors sustain.
For travellers, the immediate priority remains practical budgeting rather than reacting to a distant housing forecast. For businesses, however, the message is broader. Housing access, workforce stability and destination affordability belong in the same long-term planning conversation, even when their individual effects require further evidence.
Advertisement
