
Spain Aligns With Portugal and Other European Hubs as Airport Expansion Intensifies Southern Europe’s Aviation Gateway Race
Published
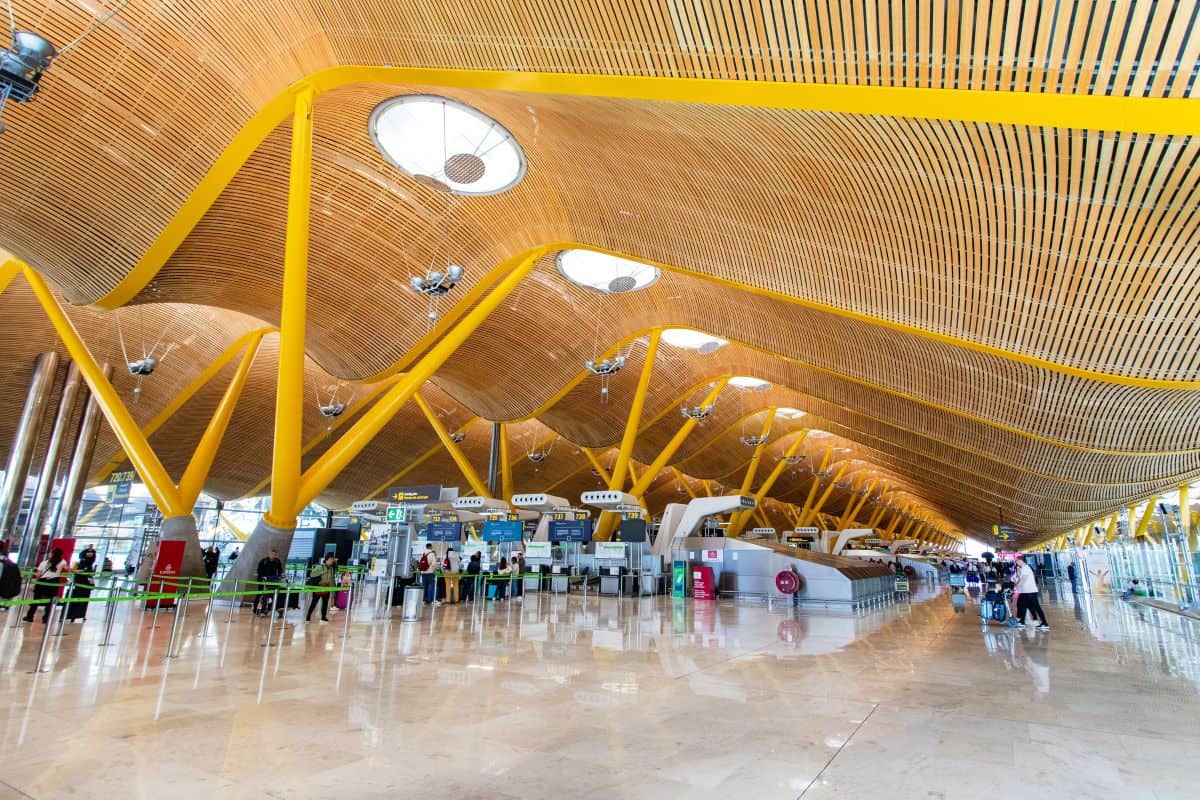
Madrid, Barcelona and Lisbon are entering a new phase of competition for aviation influence across Southern Europe. Madrid-Barajas handled 68.18 million passengers in 2025, retaining a clear lead over Barcelona-El Prat and Lisbon. Barcelona nevertheless grew faster, reaching 57.48 million passengers, while Lisbon recorded 36.1 million, its highest annual figure. The contest now extends beyond passenger totals. Airport expansion, long-haul connectivity, airline alliances, cargo capacity and transfer traffic will determine which gateway gains lasting strategic weight. Madrid is strengthening its established hub, Barcelona is pursuing a larger intercontinental role, while Lisbon is preparing a transformational new airport. For travellers, this competition could mean more routes, stronger connections and greater airline choice.
Three Airports, Three Distinct Strategies
The Iberian Peninsula is becoming one of Europe’s most consequential aviation arenas. Yet Madrid, Barcelona and Lisbon are not pursuing identical ambitions, despite their geographical proximity and overlapping catchment areas.
Madrid already possesses the strongest hub architecture. Barcelona has the faster recent passenger trajectory, while Lisbon has an unusually powerful Atlantic proposition. Therefore, the real contest concerns what kind of gateway each airport can become, rather than simply which handles the most passengers.
Official 2025 figures reveal the current hierarchy.
Advertisement
Advertisement
| Airport | 2025 Passengers | Annual Growth | 2025 Aircraft Movements | 2025 Routes |
|---|---|---|---|---|
| Madrid-Barajas | 68.18 million | +3.0% | 430,616 | 447 |
| Barcelona-El Prat | 57.48 million | +4.4% | 360,786 | 379 |
| Lisbon | 36.1 million | +2.9% | 226,990 commercial | Not directly comparable |
Madrid therefore remains roughly 10.7 million passengers ahead of Barcelona. Barcelona, however, added passengers at a faster rate during 2025, narrowing part of that gap.
The wider Spanish market also provides favourable conditions. Aena reported 321.59 million passengers across its Spanish airport network in 2025, up 3.9%. Spain’s hotel sector simultaneously recorded 366.7 million overnight stays, another historic high.
Advertisement
Advertisement
Madrid Builds From a Position of Scale
Madrid’s advantage is not merely size. Barajas already operates as a mature international hub, linking Latin America with Spain and the wider European market.
In 2025, the airport handled 51.39 million international commercial passengers. International commercial traffic rose 5.5%, while domestic commercial traffic declined 4.2%. That distinction matters because it shows Madrid’s growth increasingly reflects international demand.
Advertisement
Advertisement
Cargo provides another important advantage. Madrid handled 840,331 tonnes of freight in 2025, up 9.6% and representing more than 61% of Aena’s total Spanish airport cargo volume.
Madrid’s winter schedule also reveals where airlines see future demand. Airlines scheduled almost 33.9 million seats for winter 2025–26, up 4.6%. Asia-Pacific capacity increased 33.5%, Middle Eastern capacity rose 28.6%, and Latin American seats climbed 10.5%.
The airport is consequently evolving beyond a European tourist gateway. Its network is increasingly positioned around intercontinental connectivity and transfer economics.
That position will receive further infrastructure support. Spain’s approved 2027–2031 airport investment programme allocates approximately €4.488 billion to airports in the Madrid region. The national programme covers almost €13 billion across Aena’s network.
Advertisement
Advertisement
For travellers, that investment should ultimately matter through greater capacity, improved passenger processing and more opportunities for long-haul connections.
Barcelona Wants the Hub To Catch Up
Barcelona presents a different proposition. It already has enormous international demand, but its challenge is converting that demand into a deeper connecting hub.
The airport reached 57.48 million passengers in 2025, up 4.4%. Aircraft movements climbed 3.7% to almost 361,000, while cargo rose 10.5% to more than 200,000 tonnes. The airport also expanded its route count to 379, compared with 356 in 2024.
The strategic distinction is crucial. Barcelona already has substantial point-to-point demand from tourists and business travellers. The next stage requires more long-haul services and feeder flights that connect passengers through the airport.
Aena’s own hub-development analysis states that growth towards 70 million passengers would need to come substantially from long-haul flights and potential hub operations. Connecting passengers could allow airlines to sustain routes that local origin-and-destination demand alone might not support.
That makes Barcelona’s infrastructure programme particularly significant.
Advertisement
Advertisement
The approved expansion plan involves approximately €3.2 billion of Aena investment. It includes a 500-metre extension of the sea runway to 3,160 metres and a new satellite terminal. The project aims to increase intercontinental operating capability while addressing environmental constraints around La Ricarda.
Barcelona therefore faces a delicate balancing act. It wants the capacity of a major global hub without sacrificing the environmental assets and regional acceptance that surround the airport.
Lisbon Has the Atlantic Advantage
Lisbon is smaller by passenger volume, but its strategic geography gives it a different competitive weapon.
Lisbon Airport handled 36.1 million passengers in 2025, up 2.9%. Commercial movements reached 226,990, while airlines offered more than 42.24 million seats. The airport also serves a metropolitan tourism market that welcomed more than 9.5 million tourists during the year.
The airport’s strongest proposition lies westwards across the Atlantic. TAP has positioned Lisbon as a bridge between Europe, the Americas and Africa, supported by established cultural and commercial links.
TAP’s own analysis places Lisbon approximately 430 kilometres closer to major North American East Coast airports than competing European hubs. It estimates Lisbon is roughly 1,250 kilometres closer to major South American airports than Madrid, Paris, London and Frankfurt. The airline says this can translate into shorter flight times and lower operating costs.
Advertisement
Advertisement
That gives Lisbon a particularly strong proposition for Brazil and parts of North America.
The bigger story, however, is infrastructure.
Portugal is preparing the Luís de Camões Airport, intended to transform the country’s airport system. The Portuguese Government estimates investment at €7.9 billion to €8.9 billion, at 2024 prices. Construction is scheduled to begin in 2029, with completion targeted by 2033 and opening expected from 2035 after testing and certification.
Lisbon’s problem is therefore not a lack of strategic geography. It is the time required to convert that advantage into additional physical capacity.
TAP Could Alter Lisbon’s Trajectory
The future of TAP adds another variable to the contest.
Portugal’s Government has advanced TAP’s reprivatisation process with Air France-KLM and Lufthansa entering the final phase. In September 2026, the Government authorised negotiations with both groups over the potential sale of up to 44.9% of TAP.
Advertisement
Advertisement
The significance extends well beyond corporate ownership. A stronger European airline group could provide TAP with additional feed, partnerships, network coordination and capital.
That could reinforce Lisbon’s role as an Atlantic connecting point. However, the eventual strategy will determine whether TAP remains primarily a Portugal-focused carrier or becomes a more deeply integrated component of a European network.
For travellers, the implications could include additional frequencies, improved connections and potentially more competitive fares across selected long-haul markets.
Barcelona And Madrid Are Also Converging
The competition is not always straightforward rivalry. Airlines can use both Spanish airports as complementary gateways.
Singapore Airlines offers a useful illustration. From 26 October 2026, it plans five weekly Singapore–Barcelona–Madrid services using an Airbus A350-900. The revised operation will make Madrid the airline’s second Spanish destination and its 15th European destination.
This arrangement shows how modern airline networks can blur traditional airport competition.
Advertisement
Advertisement
A passenger may arrive through Barcelona and continue to Madrid. Another traveller could use Madrid as the long-haul gateway while Barcelona supplies a major tourism market. Consequently, network value increasingly depends on how airports interact with airline schedules.
The strongest gateway may not necessarily be the airport with the most destinations. It may be the airport where timing, aircraft capacity, feeder networks and long-haul demand intersect most efficiently.
Capacity Will Decide The Next Chapter
Passenger growth creates pressure because airport infrastructure cannot expand instantly.
| Gateway | Current Position | Major Development | Strategic Purpose |
|---|---|---|---|
| Madrid | Largest of the three | €4.488bn regional airport investment | Strengthen existing scale and connectivity |
| Barcelona | Fast-growing international airport | About €3.2bn expansion | Develop intercontinental hub capability |
| Lisbon | Smaller but Atlantic-focused | €7.9bn–€8.9bn new airport | Create long-term national capacity |
Barcelona currently faces the clearest near-term capacity tension. Aena said its 2025 growth would be constrained until expansion occurs, with greater use of available off-peak slots and more seasonal balancing required.
Madrid, by contrast, has more immediate scale and an established hub system. Lisbon has perhaps the most dramatic long-term solution, but its new airport remains years away.
Therefore, the competitive timetable is uneven. Madrid has the present advantage, Barcelona is pressing the accelerator, and Lisbon is preparing for a longer structural shift.
Advertisement
Advertisement
How Each Gateway Could Serve Travellers
For travellers, the emerging Iberian aviation contest is not simply about passenger numbers. Each gateway offers a different strategic advantage, depending on the journey, airline network and destination. Madrid currently offers the deepest overall hub ecosystem, particularly for Latin America, while Lisbon’s Atlantic position can be advantageous for Brazil, Africa and parts of North America. Barcelona’s strength lies in its enormous international leisure market and expanding long-haul ambitions, making it increasingly relevant for travellers combining Mediterranean Europe with intercontinental journeys.
| Traveller Need | Madrid | Barcelona | Lisbon |
|---|---|---|---|
| Latin America Connections | Very strong | Strong | Very strong |
| Brazil Connectivity | Strong | Moderate–Strong | Very strong |
| Africa Connectivity | Strong | Moderate | Very strong |
| North America | Very strong | Strong | Strong |
| Asia-Pacific Growth | Very strong | Strong | Growing |
| European Connections | Very extensive | Very extensive | Extensive |
| Hub Development | Mature | Expanding | Long-term transformation |
| Future Capacity Story | Major expansion | Major expansion | New airport planned |
For passengers, this creates a more useful choice than simply selecting the airport with the largest network. Madrid is the strongest all-round connecting option today, Barcelona could become more significant as its hub infrastructure develops, while Lisbon offers a particularly compelling Atlantic proposition. Travellers should therefore compare nonstop availability, connection times, seasonal frequency and competing airlines before choosing an Iberian gateway, especially on long-haul itineraries.
What The Race Means For Travellers
For passengers, the airport competition has tangible consequences.
More intercontinental capacity can create additional nonstop choices. Stronger hub competition can also encourage airlines to sharpen schedules and pricing, particularly on markets served by multiple gateways.
Travellers heading towards Latin America may find Madrid especially useful because of its established network. Passengers travelling between Europe and Brazil or parts of Africa may benefit from Lisbon’s geography and TAP’s network. Barcelona could become increasingly attractive for travellers seeking direct access to Asia, North America and Mediterranean Europe.
The difference also matters during disruption. A stronger choice of gateways can give passengers more alternatives when an airline cancels a service or when a route operates seasonally.
Advertisement
Advertisement
Spain’s tourism economy demonstrates why this matters. International visitors spent €134.7 billion in Spain during 2025, up 6.8%. Catalonia alone accounted for €24.8 billion, while the Madrid region captured €17.9 billion.
Air connectivity is therefore not simply an airport statistic. It directly influences hotel demand, business travel, meetings, cruise connections, regional tourism and visitor spending.
The Gateway Race Is Far From Settled
The evidence points towards three different versions of Southern Europe’s aviation future.
Madrid currently holds the strongest overall position. Its 68.18 million passengers, 447 routes, enormous cargo operation and deep Latin American connectivity provide a formidable foundation. Its winter capacity programme also shows strong expansion towards Asia, the Middle East and Latin America.
Barcelona represents the most credible near-term challenger. Its 4.4% passenger growth outpaced Madrid in 2025, while its planned runway and satellite-terminal expansion could unlock a more sophisticated intercontinental hub model.
Lisbon remains the strategic wildcard. Its Atlantic geography, TAP network and proposed Luís de Camões Airport could eventually reshape the balance, particularly if new airline ownership strengthens TAP’s international reach.
Advertisement
Advertisement
The most important development for travellers will therefore not be a single airport overtaking another. It will be the emergence of a more competitive Iberian aviation triangle, giving passengers more routes, stronger connections and potentially greater choice across Europe, the Americas, Africa and Asia.
The Southern European gateway of the future may ultimately be less about one dominant airport. It may instead be a network in which Madrid, Barcelona and Lisbon each exploit a different geographical and commercial advantage.
Advertisement
