Hawaii Outpaces Florida and Arizona in Visitor Spending Growth as Winter Sun Destinations Compete for American Travellers
Published
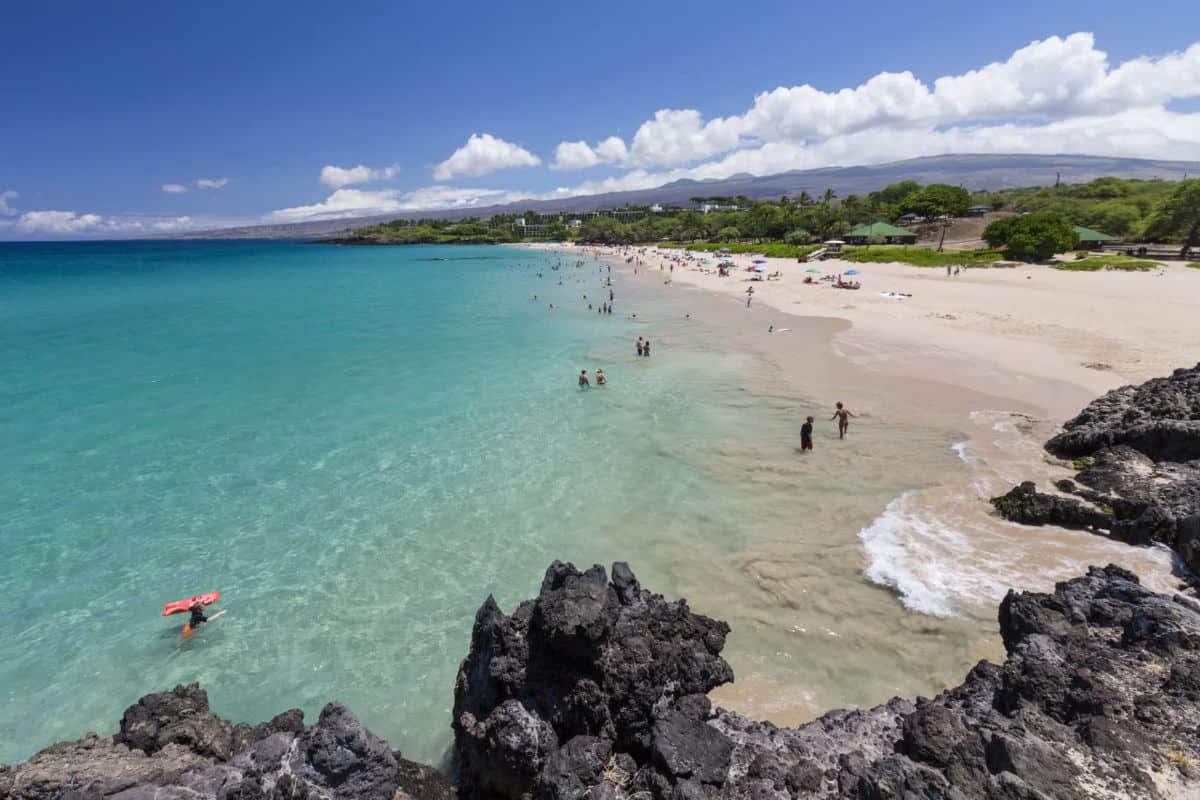
Americans seeking winter sunshine face four contrasting holiday markets, from Florida’s extensive beach network to Hawaii’s premium island resorts, Arizona’s desert retreats and Southern California’s Pacific coastline. The latest tourism figures reveal a revealing divide between visitor numbers and economic returns. Florida welcomed 143.3 million visitors in 2025, while Hawaii generated $21.75 billion in visitor spending, despite fewer arrivals. Arizona recorded $29.7 billion in direct travel spending in 2024, while San Diego County reported $14.4 billion in 2025. Meanwhile, Hawaii’s early-2026 figures show renewed demand and higher expenditure. These figures establish the competition, but winter hotel performance, flight costs and comparable holiday budgets determine which destination offers travellers the strongest proposition.
Florida’s Visitor Scale Meets the Winter Value Test
Florida enters the winter travel contest with a substantial advantage: its domestic market is enormous, its tourism infrastructure spans multiple regions, and visitors can arrive by road or air. Preliminary estimates recorded 143.3 million visitors in 2025, representing a 0.2% annual increase. Domestic travellers accounted for 131.1 million visits, or 91.5% of the total, while overseas visitors reached 9.3 million. Canadian arrivals added another 2.9 million.
The fourth quarter offered further evidence of demand. Florida received an estimated 33.5 million visitors between October and December 2025, its strongest fourth-quarter result on record. Passenger enplanements across 19 Florida airports reached 27.4 million during that period, increasing 2.8% year on year. However, these figures cover the whole quarter, not the winter holiday period alone. They also measure different things: visitor trips include road arrivals, whereas airport enplanements count departing passengers.
For holidaymakers, Florida’s breadth matters as much as its headline volume. Orlando combines theme parks and family resorts, while Miami and Fort Lauderdale offer beaches, cruise connections and urban entertainment. Tampa and the Gulf Coast provide another mix of coastal stays and family attractions. This diversity gives travellers more ways to adjust their itineraries, although school holidays and major events can still raise prices sharply.
Advertisement
Advertisement
Florida’s road-trip appeal also separates it from Hawaii. Visit Florida estimates that 59.3% of all visitors arrived by non-air transport in 2025, against 40.7% by air. That split makes driving a material part of the state’s visitor economy, although a road trip still involves fuel, tolls, parking and potentially long distances between attractions.
The central question is whether Florida’s scale translates into lower total holiday costs. Its large accommodation market offers a wide range of hotel categories, but the cheapest headline room rate may sit far from the beach or major attractions. Families should compare the full cost of transport, parking, theme-park tickets and mandatory hotel fees before treating Florida as the automatic budget winner.
Advertisement
Advertisement
Hawaii’s Spending Growth Tells a Different Story
Hawaii offers a contrasting picture: fewer visitors can still generate stronger tourism revenue when daily expenditure rises. The state welcomed 9.64 million visitors in 2025, down 0.6% from 2024. Yet visitor spending increased 5.7%, reaching $21.75 billion. That divergence makes Hawaii one of the most revealing markets in this comparison.
The latest completed winter provides an even sharper signal. In December 2025, Hawaii recorded 868,894 visitors, a 4.3% decline from a year earlier. Nevertheless, total spending rose 3.7% to $2.12 billion. Average daily expenditure increased 11% to $273 per person, while the average stay shortened from 9.14 to 8.92 days. Travellers were spending more each day despite spending slightly less time on the islands.
Advertisement
Advertisement
Momentum strengthened in early 2026. January brought 874,358 visitors, up 10.4% year on year, while expenditure climbed 19% to $2.26 billion. February arrivals reached 787,024, a 3.6% annual increase, and visitor spending rose 10.3% to $1.91 billion. Across January and February, spending reached $4.17 billion, up 14.8% from the same period in 2025. These are preliminary figures and nominal expenditure, so they do not establish equivalent growth in real spending after inflation.
Airline supply also expanded. Hawaii recorded 1,072,409 transpacific seats in February 2026, up 7.9% year on year. This increase suggests more scheduled capacity was available, although seat supply alone does not prove that every flight sold more tickets or that fares fell.
The islands also differ substantially. Maui welcomed 2.52 million visitors in 2025, up 7%, while spending increased 12.7% to $5.97 billion. Oahu received 5.68 million visitors, down 2%, yet expenditure rose 5.3% to $9.42 billion. These figures show why travellers should not treat Hawaii as one uniform hotel market.
For visitors, the trade-off remains clear. Hawaii can reward a longer, carefully planned stay, but flights, accommodation and inter-island transport can make short breaks expensive. Travellers should compare hotel rooms with condominiums or other lawful accommodation options, check island-specific transport requirements, and calculate costs per person per day. Daily visitor expenditure is an economic measure, not a ready-made holiday budget: it includes different spending categories and does not represent a guaranteed price for an individual trip.
Advertisement
Advertisement
Arizona’s Desert Resorts Challenge Coastal Markets
Arizona competes through a different combination of winter conditions, resort infrastructure and outdoor recreation. Its appeal extends beyond Phoenix and Scottsdale to Tucson, desert landscapes and national parks. The state’s official travel-impact study recorded $29.7 billion in direct travel spending in 2024, up 1.1% from $29.3 billion in 2023. Travel-generated employment reached 193,860, while tourism-related tax revenue increased 3.8% to $4.3 billion.
The accommodation figures offer a more specific view of winter demand. Arizona’s first-quarter 2026 lodging report recorded statewide occupancy of 71.4%, compared with 69.7% in the first quarter of 2025. Average daily rates rose from $195.20 to $201.64, while revenue per available room increased from $136.06 to $143.98. The figures cover January to March, so they include early spring and should not be described as a pure December-to-February result.
Metro Phoenix performed particularly strongly. Its first-quarter occupancy reached 78.6%, up from 76% a year earlier. Average daily rates climbed to $232.14, while RevPAR reached $182.49, an annual increase of 7.2%. Tucson recorded occupancy of 72.5%, compared with 70.5% in the previous year, but its average daily rate declined 2.1% to $179.83. The contrasting results show how regional pricing can diverge even within one state.
| Arizona lodging indicator | Q1 2025 | Q1 2026 | Annual change |
|---|---|---|---|
| Statewide occupancy | 69.7% | 71.4% | +2.4% |
| Statewide average daily rate | $195.20 | $201.64 | +3.3% |
| Statewide RevPAR | $136.06 | $143.98 | +5.8% |
| Metro Phoenix occupancy | 76.0% | 78.6% | +3.4% |
| Metro Phoenix average daily rate | $223.86 | $232.14 | +3.7% |
| Metro Phoenix RevPAR | $170.22 | $182.49 | +7.2% |
| Metro Tucson average daily rate | $183.69 | $179.83 | −2.1% |
Arizona therefore cannot automatically claim the cheapest winter stay. Phoenix’s strong occupancy and rising rates suggest robust demand, while Tucson’s lower daily rate offers a different pricing proposition. Resort fees, car hire and distances between attractions can also change the final bill. Visitors should compare accommodation in the exact area they plan to explore, rather than relying on a statewide average.
The state’s outdoor economy adds another dimension. National Park Service data show that 11.3 million visitors to Arizona’s national parks spent $1.4 billion in the state in 2024. That spending generated an estimated $2.2 billion in cumulative economic benefits. For travellers, the figures underline the value of combining desert landscapes and outdoor attractions with city-based accommodation, rather than limiting a winter trip to resort pools.
Southern California Balances Coastal Appeal and Cost
Southern California offers beaches, entertainment, cultural attractions and mild coastal conditions, but its markets have distinct price profiles. San Diego County provides a useful measurable case study, although it should not be mistaken for the entire Southern California region.
Advertisement
Advertisement
San Diego recorded 32.4 million visitors in 2025, including 17.8 million overnight visitors. Direct visitor spending reached $14.4 billion, down from $14.8 billion in 2024. Average daily hotel occupancy fell from 74.2% to 72.2%, while the average daily rate edged up from $212 to $213. Hotels sold 17.4 million room nights, slightly below the 17.5 million recorded in 2024.
These figures reveal a subtle pressure point. Room prices remained broadly stable, yet occupancy and direct visitor spending declined. The data do not establish a single cause, but they show why higher room rates should not automatically be interpreted as stronger tourism demand. Supply, visitor mix, length of stay and spending beyond hotels can all influence the wider result.
California’s statewide economy nevertheless remains formidable. Visit California reported $158.9 billion in travel spending in 2025, up 1.7% from $156.2 billion in 2024. Accommodation spending increased 2.2% to $35.2 billion, while spending on food services rose 4.6% to $38.5 billion. Travel generated $13.6 billion in state and local tax revenue. These statewide figures provide economic context, not a direct measure of Southern California’s winter performance.
Airfare data also illustrate the importance of route selection. The US Bureau of Transportation Statistics reported average domestic itinerary fares for 2025 of $423.63 from Los Angeles, $371.54 from San Diego and $389.54 from Honolulu. These are average fares for passengers departing those airports, not prices for flights into them. They therefore cannot establish which destination is cheapest to reach.
For travellers, Southern California’s appeal lies in the ability to combine several experiences without changing states. However, beach-area hotels, car parking and travel between Los Angeles, Anaheim and San Diego can add materially to costs. A carefully located hotel and a realistic transport plan may matter more than a small difference in the advertised nightly rate.
Flight Demand Exposes the Real Cost Gap
Air travel is an important part of the winter comparison, but reliable analysis must separate scheduled capacity, passenger numbers and ticket prices. The three measures answer different questions: capacity indicates how many seats airlines offer, passenger statistics record actual travel, and airfare datasets reveal what passengers paid on defined routes or itineraries.
Advertisement
Advertisement
AAA’s year-end 2025 forecast projected a record 8.03 million domestic air travellers over the holiday period, an increase of 2.3% from the previous year. Its booking data indicated an average round-trip domestic ticket price approaching $900, approximately 7% higher than the previous holiday season. That national average is a holiday-period forecast, not a destination-specific fare comparison.
The distinction matters for the four markets. Florida benefits from substantial non-air access, Arizona can suit road trips and regional flights, and Southern California has several major airports. Hawaii, by contrast, requires an air journey for visitors travelling from the US mainland. A fare that looks competitive can still become expensive when luggage, seat selection, transfers and ground transport enter the calculation.
The most useful airfare test would compare round-trip economy journeys from the same origin airports, on the same dates and with equivalent booking lead times. December holiday departures should be assessed separately from January and February trips. Without that control, a cheaper fare may simply reflect a different travel date, route or set of conditions.
The Four Markets at a Glance
The available evidence does not support a single, definitive winter winner across all four destinations. However, it does identify different strengths and the data travellers should examine before booking.
| Measure | Florida | Hawaii | Arizona | Southern California |
|---|---|---|---|---|
| Latest cited annual tourism indicator | 143.3m visitors, 2025 | $21.75bn visitor spending, 2025 | $29.7bn direct travel spending, 2024 | $14.4bn direct spending in San Diego County, 2025 |
| Strongest evidence in this comparison | Domestic visitor scale | Spending growth despite lower annual arrivals | Strong first-quarter hotel performance | Extensive coastal and urban visitor economy |
| Key accommodation consideration | Resort location and attraction costs | Island-specific rates and length of stay | Phoenix and Scottsdale versus Tucson | Coastal rates and transport between cities |
| Principal transport consideration | Road access and multiple airports | Mainland flights and island transfers | Regional flights and car hire | Multiple airports and inter-city travel |
| Best comparison for travellers | Total family holiday cost | Cost per day and length of stay | Room rate plus transport | Hotel location plus local travel |
Figures cover different reporting periods and geographic definitions. They are contextual indicators, not directly comparable rankings.
How Travellers Can Compare Costs Fairly
A credible comparison of winter sun destinations must account for more than hotel prices and flight tickets. A three-night trip and a seven-night holiday can produce different value outcomes because flights represent a larger share of shorter stays. Families should also calculate attraction tickets, meals, car hire, parking, taxes and mandatory accommodation charges.
Advertisement
Advertisement
The following framework offers a practical way to compare quotations without presenting unverified prices as facts.
| Budget component | What to check before booking |
|---|---|
| Return flights | Same origin, dates, baggage and booking lead time |
| Accommodation | Same number of nights and comparable room standards |
| Taxes and fees | Mandatory resort fees, lodging taxes and cleaning charges |
| Ground transport | Car hire, fuel, parking, transfers or public transport |
| Activities | Theme parks, excursions, outdoor permits and attraction tickets |
| Overall value | Total trip cost divided by travellers and nights |
Travellers should also distinguish winter weather from guaranteed sunshine. Conditions vary across each region, while coastal temperatures, desert nights and mountain elevations can differ substantially. Flexible cancellation terms and suitable travel insurance can reduce the financial risk of weather-related disruption.
For the industry, the comparison also carries a wider lesson. Visitor volume, hotel performance and tourism revenue are separate indicators. Hawaii’s rising spending alongside lower 2025 arrivals illustrates that distinction, while San Diego’s declining occupancy alongside a slightly higher average room rate demonstrates why one measure cannot explain an entire destination economy. Arizona’s first-quarter lodging gains offer a further reminder that demand and pricing can strengthen together.
Why the Winter Market Matters
The competition between these four regions reflects more than a seasonal search for warmer weather. Tourism supports accommodation businesses, airlines, restaurants, attractions, transport providers and local tax revenues. California generated $13.6 billion in state and local tax revenue from travel in 2025, while Arizona’s 2024 travel-impact study recorded $4.3 billion in tax revenue across local, state and federal levels. These figures use different reporting scopes, but they underline tourism’s importance to public finances and employment.
The next useful development will be a matched winter dataset covering December 2025 to February 2026. It should combine monthly hotel occupancy, average daily rates, RevPAR, domestic passenger traffic and route-level airfares. Until all four markets have comparable figures, declaring one the definitive winner would overstate the evidence.
Four Destinations, Different Winter Wins
Florida remains a formidable option for travellers seeking choice, family attractions and road access. Hawaii combines a premium island experience with rising visitor expenditure, while Arizona offers desert resorts and strong recent hotel indicators. Southern California brings together beaches, entertainment and urban exploration, although its transport and accommodation costs require careful planning. The smartest winter escape depends on the complete itinerary, not a headline visitor ranking. For travellers, the decisive calculation is the total cost of reaching, staying in and exploring a destination. For tourism businesses, the same comparison reveals why arrivals, room demand and visitor spending must be assessed together.
Advertisement