
Massachusetts and New York Mirror Leading Aviation Markets as Transatlantic Capacity Redefines Europe Travel
Published
New York, Boston, Chicago and Atlanta are emerging as four distinctly different gateways for transatlantic travel, but their strengths extend well beyond raw flight numbers. Current schedule data shows Atlanta leading the US in overall airport capacity, while Chicago O’Hare is expanding rapidly and has become the most connected megahub in the Americas. New York retains exceptional long-haul scale across JFK and Newark, while Boston is building an unusually concentrated Europe network led by Delta and JetBlue.
The distinction matters for travellers. More seats do not automatically mean more choice, and a larger airport does not necessarily offer the broadest European network. Frequency, nonstop destinations, airline competition, connecting opportunities and capacity growth can materially change the best gateway for a European holiday, business trip or multi-country itinerary.
Four Gateways, Four Different Aviation Models
The most revealing way to compare these cities is to treat them as aviation markets rather than isolated airports. New York therefore includes JFK and Newark, while Chicago centres on O’Hare, Boston on Logan and Atlanta on Hartsfield-Jackson.
OAG’s September 2026 schedule data shows Atlanta with 5.09 million scheduled seats across its network. Chicago O’Hare follows with 4.89 million, while JFK alone carries 3.07 million. O’Hare added 471,100 seats year on year, representing growth of about 10.7%.
Advertisement
Advertisement
These figures are total airport capacity, not transatlantic capacity. That distinction is critical because Atlanta’s enormous domestic network creates a much larger overall seat base. The comparison becomes more meaningful when Europe-bound services are isolated from domestic and other international markets.
| Gateway | Primary airport(s) | September 2026 total scheduled seats | Notable capacity signal |
|---|---|---|---|
| New York | JFK + Newark | JFK 3.07m alone | JFK capacity down 2.8% at state level context |
| Boston | BOS | Smaller overall market | Strong Europe-focused expansion |
| Chicago | ORD | 4.89m | +10.7% year on year |
| Atlanta | ATL | 5.09m | +5.0% year on year |
The wider US market also provides an important backdrop. Scheduled US capacity reached 111.6 million seats in September 2026, up 0.5% year on year. Domestic capacity rose 1%, while international capacity fell 1% to 25.6 million seats.
Advertisement
Advertisement
That contraction makes transatlantic expansion particularly significant. Airlines are increasingly concentrating aircraft on markets where premium demand, connecting traffic and network economics support sustained long-haul operations.
New York’s Two-Airport Advantage
New York’s biggest strength is structural rather than numerical. Its transatlantic network is divided between John F. Kennedy International Airport and Newark Liberty International Airport, allowing several large airline groups to compete for passengers across the metropolitan area.
Advertisement
Advertisement
JFK–London Heathrow remains one of the world’s most substantial international city pairs. OAG recorded 986,480 seats on the route in the second quarter of 2026, although capacity fell 5.7% from a year earlier. Paris–JFK also experienced an 8.4% capacity reduction in the same comparison.
That softening on two flagship corridors does not mean New York is losing its European relevance. Instead, it highlights an important shift towards network diversification and yield management. Airlines can adjust capacity on mature trunk routes while preserving service to secondary European markets with attractive leisure or premium demand.
United also expanded Newark’s European reach in 2026, launching services to Bari, Split, Santiago de Compostela and Glasgow.
The New York market is simultaneously undergoing a substantial infrastructure transformation. The Port Authority says JFK is in the middle of a $19 billion transformation, including new terminals and a redesigned roadway network.
Advertisement
Advertisement
For travellers, this matters because capacity growth eventually depends on gates, terminal space, aircraft stands and passenger-processing infrastructure. New York therefore represents the classic scale-plus-choice gateway, even when individual routes experience seasonal or annual capacity adjustments.
Boston Turns Concentration Into an Advantage
Boston presents a different proposition. Logan does not need New York’s sheer metropolitan scale to become influential across the Atlantic because its airline network is unusually focused on Europe.
The 2026 summer schedule illustrates that strategy. JetBlue planned 238,800 departure seats on transatlantic routes from Boston, up from 188,948 the previous summer. That represented 9.4% of Boston’s Europe capacity, behind Delta’s 25% share.
JetBlue’s expansion also illustrates how smaller aircraft can reshape a long-haul market. Its transatlantic fleet uses Airbus A321LR and A321neo aircraft, allowing the airline to serve European cities without relying exclusively on large widebody aircraft.
Delta has simultaneously added Madrid and Nice to Boston’s network while increasing service on Barcelona and Milan. The carrier later announced Boston–Venice service, reinforcing Logan’s position as a Europe-oriented gateway.
| Boston Europe strategy | 2025–26 development |
|---|---|
| Delta | 25% of summer 2026 BOS-Europe capacity |
| JetBlue | 238,800 transatlantic departure seats |
| JetBlue year-on-year change | +26.4% |
| JetBlue Europe capacity share | 9.4% |
| New destinations | Madrid, Nice, Venice |
| Network emphasis | Western and Southern Europe |
The lesson for travellers is subtle. Boston may offer less total aviation capacity than the largest US hubs, but its Europe proposition can be highly efficient for passengers originating in New England.
Advertisement
Advertisement
Chicago Builds a Continental Launchpad
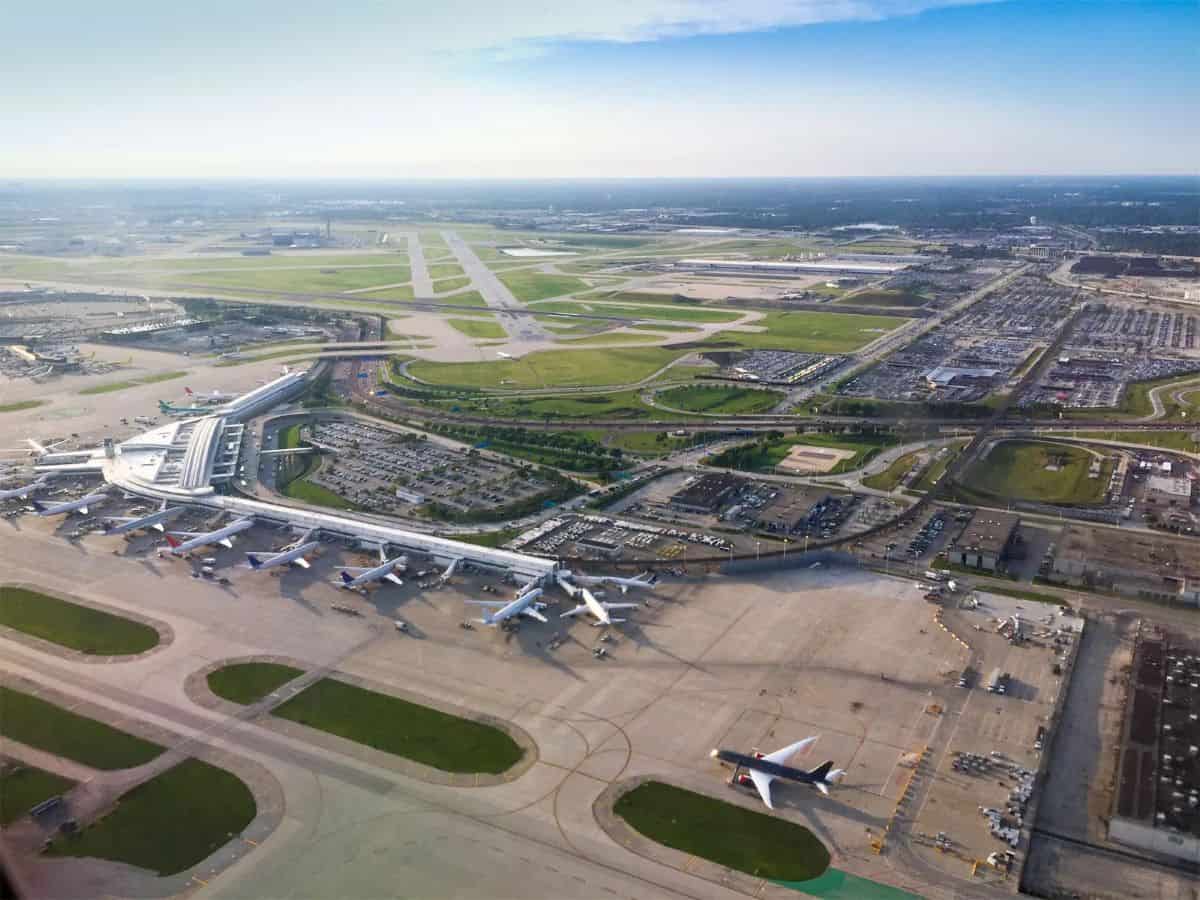
Chicago O’Hare has perhaps the most compelling growth story among the four markets. OAG ranked O’Hare fifth globally in its 2026 Megahubs index and first among airports in the Americas. The airport recorded 71,497 potential connections, 308 destinations and 54.2 million seats between September 2025 and August 2026.
O’Hare’s capacity grew more than 10.6%, while potential connections rose 9.8%. Its destination count also increased from 297 to 308 within a year.
That growth changes Chicago’s role in the transatlantic market. It is not simply a Midwestern origin airport. It functions as a continental distribution platform, pulling passengers from across the United States and feeding them towards Europe.
The airport’s September 2026 schedule listed approximately 128 daily international direct flights to 62 destinations. Its published international network includes Amsterdam, Athens, Barcelona, Brussels, Copenhagen, Dublin, Edinburgh, Frankfurt and other European gateways.
Chicago’s competitive advantage also comes from airline diversity. OAG identifies United as the dominant carrier at 49% of airport capacity, but that is materially less concentrated than Atlanta’s dependence on Delta.
For travellers, that means Chicago combines scale with choice. A passenger can often compare different alliance structures, departure times and connecting options rather than relying on a single dominant network.
Advertisement
Advertisement
Atlanta’s Hidden Transatlantic Power
Atlanta can look less impressive if the comparison focuses only on the number of European cities. Its real strength lies in the enormous domestic network feeding its international flights.
Hartsfield-Jackson remains the largest US airport by scheduled seat capacity. OAG recorded 5.09 million seats in September 2026, with capacity up 5% year on year.
Delta’s dominance is central to that model. OAG’s 2026 Megahubs analysis puts Delta’s share of ATL flights at about 80%, making Atlanta fundamentally different from Chicago’s more diversified structure.
This creates a powerful network effect. A traveller in a smaller US city may connect through Atlanta before continuing to Europe, even when Atlanta is not the most obvious origin market.
Delta’s 2026 transatlantic programme reinforces this role. Its summer network with Air France, KLM and Virgin Atlantic spans major European gateways including Amsterdam, Paris, London, Frankfurt, Munich, Milan, Rome, Madrid, Lisbon, Copenhagen and Stockholm.
The resulting proposition is therefore different from New York or Boston. Atlanta’s value lies in network reach and connecting efficiency, rather than simply the number of European destinations visible from the airport’s departure board.
Advertisement
Advertisement
Capacity Is Not the Same as Choice
The central mistake in airport comparisons is treating every seat as equivalent. A 300-seat widebody flight and two 150-seat departures provide the same nominal capacity but very different experiences for travellers.
Frequency can be more valuable than aggregate seats. A business traveller may prefer four daily departures over one large aircraft, while a leisure traveller may value a direct seasonal flight that eliminates a connection.
The aircraft mix also matters. Boston’s use of A321LR and A321neo aircraft demonstrates how long-range narrowbodies can support thinner European routes. This allows airlines to test markets that might not justify a large widebody operation.
| Traveller priority | Gateway likely to stand out | Why |
|---|---|---|
| Maximum metropolitan choice | New York | JFK + Newark network |
| Broad connecting network | Chicago | Major domestic and international connectivity |
| Hub-based US connections | Atlanta | Exceptional Delta feed |
| Focused Europe access | Boston | Strong Europe concentration |
| Airline variety | New York / Chicago | Multiple major network carriers |
| Network growth | Chicago | Rapid capacity and connectivity expansion |
These are analytical strengths rather than an absolute ranking. The best gateway changes according to the traveller’s origin, destination and tolerance for connections.
Competition Can Shape the Fare Environment
Capacity also has consequences for fares. OAG’s 2026 analysis found that modest reductions on major transatlantic markets have supported fare stability or slight increases, particularly where business demand remains resilient.
That makes airline competition important. More carriers do not guarantee cheap tickets, but competing schedules can create greater flexibility in departure times, cabin products and loyalty benefits.
Advertisement
Advertisement
Boston offers a useful example. JetBlue’s expansion places it against established European carriers on routes such as Boston–Barcelona, where Iberia already provides substantial capacity.
Chicago offers a different competitive equation because United and American have major network positions. New York goes further by combining multiple US and European carriers across two principal international airports.
Atlanta, by contrast, offers exceptional connectivity but much greater dependence on one dominant carrier. That can simplify itineraries for loyal Delta passengers while narrowing the range of network alternatives.
Growth Will Matter More Than Today’s Ranking
The most durable insight from this comparison is that today’s biggest airport is not necessarily tomorrow’s fastest-growing gateway.
Chicago’s 10.6% capacity growth and 9.8% increase in potential connections demonstrate a particularly strong expansion trajectory. Atlanta remains the largest overall US airport, but its 5% growth rate was lower in the same September comparison.
New York is simultaneously investing heavily in infrastructure. Boston is attracting additional European routes through both Delta and JetBlue. These developments suggest that the transatlantic market is becoming more differentiated rather than simply larger.
Advertisement
Advertisement
The wider international picture supports that interpretation. US international scheduled capacity declined 1% year on year in September 2026, even while domestic capacity expanded.
That environment rewards airlines that can deploy long-haul aircraft selectively. It also makes route launches, seasonal extensions and aircraft gauge increasingly important indicators for travellers.
What Travellers Should Watch Before Booking
Travellers should look beyond the airport name when choosing a transatlantic departure. First, compare nonstop destinations and daily frequency, rather than relying solely on the total number of destinations.
Second, check whether a route operates year-round or only during the summer schedule. Airlines increasingly adjust European services seasonally, and a city available in July may disappear from the timetable during winter.
Third, compare the entire journey rather than the first flight. A slightly longer domestic connection can sometimes provide a much better European departure time or substantially more competitive fare.
Finally, check the operating carrier and aircraft. The growth of long-range narrowbody aircraft means that some European routes now operate with different cabin configurations and capacity profiles from traditional widebody services.
Advertisement
Advertisement
The US Department of Transportation’s Air Travel Consumer Reports provide another useful reference point. These monthly reports cover delays, baggage problems, oversales and consumer complaints, while the underlying delay and baggage datasets come through the Bureau of Transportation Statistics.
The Gateway Choice Depends on the Journey
There is no single winner across every measure. New York remains the scale leader, with two major international airports creating a formidable transatlantic marketplace and an extraordinary concentration of European routes.
Boston’s strength lies in focused European access and growing competition. Chicago combines an expanding international network with exceptional domestic connectivity, making it arguably the most compelling growth story among these four gateways. Atlanta remains the industry’s quintessential connecting machine, powered by Delta’s dominant network and enormous domestic feed.
For travellers, the smartest choice is therefore destination-specific. A New Yorker may benefit from JFK or Newark’s extraordinary frequency, while a Midwestern traveller may find Chicago’s network breadth decisive. New England passengers can exploit Boston’s concentrated Europe schedule, while travellers from smaller US cities may find Atlanta’s connecting architecture difficult to beat.
The more useful question is not which airport is biggest. It is which gateway offers the right combination of nonstop reach, schedule frequency, airline competition and connecting convenience for the journey being planned.
Advertisement
