

Cancún Goes Hand in Hand With Tulum, Los Cabos and Others in Leading Mexican Tourism Through High Hotel Occupancy in 2026
Published
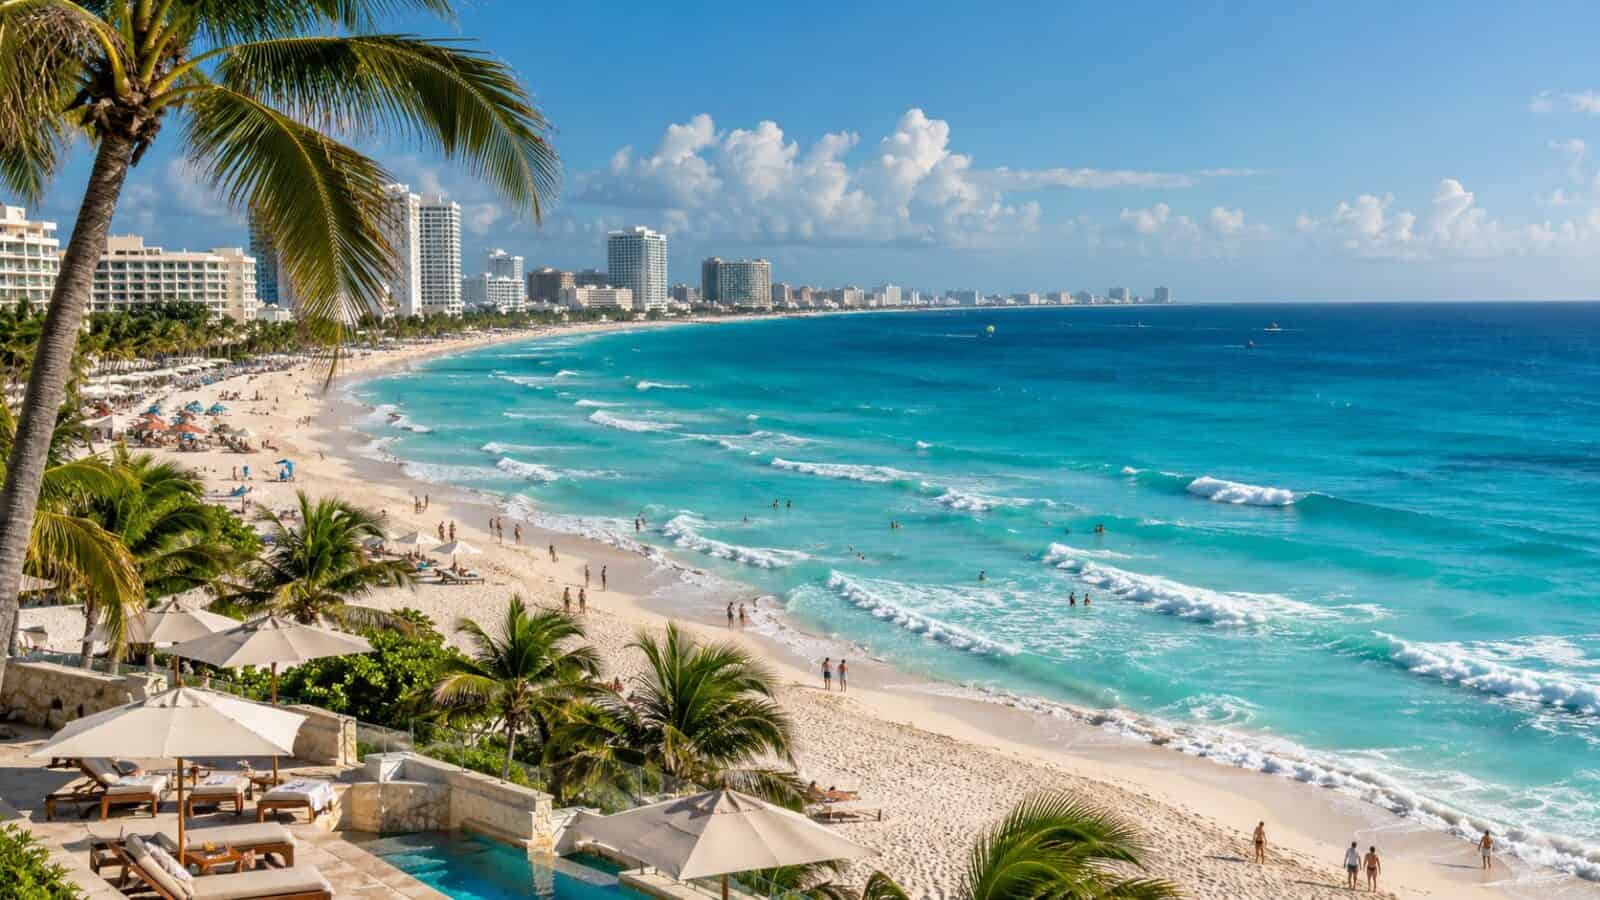
Cancún goes hand in hand with Tulum, Los Cabos and others in leading Mexican tourism through high hotel occupancy in 2026, driven by strong international appeal, luxury resorts, beachfront attractions and established tourism infrastructure. Cancún recorded 74.44% occupancy, while Los Cabos maintained 73.5% and Tulum reached 63.69% during January–July. Despite declines from 2025, these destinations continue attracting domestic and international travellers, supported by diverse accommodation options, aviation connectivity and demand for coastal holidays. Their performance highlights Mexico’s tourism strength while revealing growing competition, seasonal pressures and changing visitor preferences across its hospitality industry.
From the Caribbean beaches of Quintana Roo to the luxury resorts of Baja California Sur and the Pacific coastline of Jalisco, Mexico’s hotel industry is navigating a changing tourism environment. Established destinations continue to benefit from international recognition, resort infrastructure and aviation connectivity, while emerging markets face increasing competition and changing visitor preferences.
According to tourism statistics reported by Mexico’s tourism ministry and regional tourism monitoring agencies, Cancún recorded average hotel occupancy of 74.44% during January–July 2026, while the wider Los Cabos market maintained approximately 73.5% over the same period. Cabo San Lucas performed particularly strongly during the first quarter, recording occupancy of approximately 81.4%.
Other destinations experienced more pronounced reductions. Tulum’s January–July occupancy fell to 63.69%, while Puerto Vallarta recorded approximately 73.7% during the first quarter, below its corresponding 2025 performance.
Advertisement
Advertisement
These figures demonstrate that Mexico’s tourism industry remains active, but hotel performance varies considerably by destination, season and accommodation category.
Mexico Hotel Occupancy in 2026 – Major Tourism Destinations Compared
The following table presents reported hotel occupancy rates across leading Mexican destinations. The figures cover different reporting periods and should not be interpreted as directly comparable annual averages.
Advertisement
Advertisement
| Destination | 2025 Hotel Occupancy | 2026 Hotel Occupancy | Change | Reporting Period |
|---|---|---|---|---|
| Cancún | 76.77% | 74.44% | -2.33 percentage points | January–July |
| Tulum | 72.67% | 63.69% | -8.98 percentage points | January–July |
| Playa del Carmen | 75.76% | 71.27% | -4.49 percentage points | January–July |
| Riviera Maya | 75.34% | 70.71% | -4.63 percentage points | January–July |
| Costa Mujeres | 81.76% | 75.64% | -6.12 percentage points | January–July |
| Isla Mujeres | 68.57% | 72.57% | +4.00 percentage points | January–July |
| Cozumel | 71.13% | 69.44% | -1.69 percentage points | January–July |
| Los Cabos | 76.10% | 73.50% | -2.60 percentage points | January–July |
| Cabo San Lucas | 82.90% | 81.40% | -1.50 percentage points | January–March |
| Puerto Vallarta | 83.50% | 73.70% | -9.80 percentage points | January–March |
Source: Reported DataTur statistics and Quintana Roo tourism monitoring figures. Cabo San Lucas and Los Cabos refer to overlapping geographic markets and should not be added together. These are reported occupancy comparisons rather than a complete national hotel census.
Cancún – Caribbean Tourism Maintains Strong Hotel Demand Despite Softer Occupancy
Cancún continues to occupy an important position in Mexico’s international tourism industry, supported by its established resort infrastructure, extensive accommodation choices and access to the Caribbean coastline.
Advertisement
Advertisement
The destination recorded average hotel occupancy of 74.44% during January–July 2026, compared with 76.77% during the corresponding period in 2025. Although the decline of 2.33 percentage points indicates softer room utilisation, the figures suggest that approximately three-quarters of available hotel capacity remained occupied on average during the reporting period.
Cancún’s accommodation market includes large all-inclusive resorts, luxury beachfront properties, family-oriented hotels and independent accommodation. This variety allows the destination to attract different traveller segments, including families, couples, honeymooners, conference delegates and international leisure visitors.
However, the city’s hotel industry is facing increasing competition as accommodation capacity expands across Quintana Roo. Additional hotel rooms can reduce occupancy percentages even when visitor numbers remain relatively stable.
Monthly data also indicates changing seasonal demand. Reported occupancy declined from approximately 71% in June 2025 to 66.5% in June 2026. July also recorded a reduction, falling from 75.3% to 68.3%.
Advertisement
Advertisement
Aviation activity provides additional context. Cancún International Airport handled approximately 14.76 million passenger movements during the first half of 2026, representing a 4.7% decline compared with the corresponding period of 2025.
For Cancún’s tourism businesses, the challenge is to maintain competitive room rates and attractive holiday experiences while responding to changing airline schedules, accommodation supply and international demand.
Despite softer annual comparisons, Cancún’s occupancy levels demonstrate the continued importance of the destination within Mexico’s Caribbean tourism market.
Tulum – Boutique Hotels Face Pressure While Larger Resorts Maintain Stronger Demand
Tulum presents one of the most contrasting accommodation markets in Mexico during 2026. Known for its Caribbean beaches, archaeological heritage, wellness retreats and boutique hospitality, the destination has developed a distinctive international tourism identity.
However, the latest occupancy figures reveal that demand is not distributed evenly across its accommodation sector.
Tulum recorded average hotel occupancy of 63.69% during January–July 2026, compared with 72.67% during the same period in 2025. The reduction of 8.98 percentage points represents one of the more substantial declines among the major destinations examined.
Advertisement
Advertisement
Some boutique hotels experienced considerably weaker results during selected periods. Local industry reports indicated occupancy of approximately 15–20% at certain coastal properties, although these figures do not represent the entire Tulum hotel market.
Larger resorts performed differently. Hotel association figures for part of April indicated overall occupancy of approximately 68%, with all-inclusive properties averaging 77.6% and European-plan hotels recording approximately 45%.
This contrast reveals an important change in accommodation demand. Travellers choosing all-inclusive resorts may value predictable holiday costs, integrated dining, recreational facilities and convenient services.
Independent boutique hotels often compete through personalised experiences, distinctive architecture, wellness programmes and beachfront locations. However, they may face greater challenges when travellers become more price-sensitive or accommodation supply expands.
Air connectivity is another important consideration. Tulum International Airport has introduced additional access to the destination, but airline network adjustments and competition from Cancún continue to influence travel patterns.
For Tulum’s hospitality sector, improving occupancy will require a balance between competitive pricing, reliable accessibility and preserving the destination’s distinctive appeal.
Advertisement
Advertisement
The figures suggest that Tulum remains an important Mexican tourism destination, but its hotel market is undergoing a period of adjustment rather than experiencing uniform growth.
Los Cabos – Luxury Resorts Sustain High Occupancy Along Mexico’s Pacific Coast
Los Cabos continues to demonstrate the strength of Mexico’s premium resort tourism market, supported by luxury accommodation, coastal landscapes, internationally recognised golf courses and strong connections with North American travellers.
The wider Los Cabos destination recorded average hotel occupancy of approximately 73.5% during January–July 2026, compared with 76.1% during the corresponding period of 2025.
Although this represents a reduction of 2.6 percentage points, the destination maintained relatively high room utilisation.
Cabo San Lucas, one of the principal tourism centres within Los Cabos, recorded even stronger performance during the first quarter. Hotel occupancy reached approximately 81.4% between January and March 2026, compared with 82.9% during the same period in 2025.
The figures highlight the importance of seasonal demand and accommodation positioning.
Advertisement
Advertisement
Los Cabos attracts travellers seeking premium beachfront resorts, private villas, spa experiences, marine activities, golf holidays and high-end dining.
Its accommodation market includes internationally recognised luxury hotel brands alongside independent resorts and boutique properties.
For investors and hotel operators, occupancy is only one measure of performance. Average daily room rates, revenue per available room and operating costs are also essential when evaluating profitability.
A luxury property may generate substantial revenue even with slightly lower occupancy if room rates remain strong.
The destination’s relatively modest annual occupancy decline suggests that premium tourism demand has remained resilient, although the available figures do not establish whether hotel revenue or profitability increased.
Los Cabos’ long-term competitiveness will depend on maintaining its luxury positioning while adapting to changing travel costs, environmental considerations and international visitor expectations.
Advertisement
Advertisement
Puerto Vallarta – Holiday Occupancy Peaks Contrast With Softer Quarterly Performance
Puerto Vallarta remains one of Mexico’s leading Pacific coast tourism destinations, attracting visitors through its beaches, historic centre, gastronomy, cultural experiences and resort accommodation.
However, its 2026 hotel occupancy figures reveal a more complicated picture than peak holiday performance alone might suggest.
During January–March 2026, Puerto Vallarta recorded average hotel occupancy of approximately 73.7%, compared with 83.5% during the corresponding period in 2025.
The reduction of 9.8 percentage points represents a substantial change in average room utilisation.
At the same time, selected holiday periods reportedly generated occupancy levels approaching 95%, demonstrating the destination’s ability to attract strong short-term demand.
These figures are not contradictory. A destination can experience exceptionally high occupancy during major holidays while recording weaker averages across an entire quarter.
Advertisement
Advertisement
For Puerto Vallarta, this distinction is particularly important because its tourism economy depends on both international holidaymakers and domestic travellers.
The destination offers a combination of large all-inclusive resorts, boutique accommodation, luxury properties and independently operated hotels.
Visitors also explore nearby coastal communities, marine attractions and destinations around Bahía de Banderas.
Maintaining stronger occupancy outside peak holiday periods could help hotels generate more consistent revenue and support year-round employment.
Cultural festivals, gastronomy, wellness tourism and regional experiences may provide opportunities to attract visitors during quieter months.
Puerto Vallarta’s figures therefore demonstrate that high holiday demand remains valuable, but sustained hotel performance requires consistent room utilisation throughout the year.
Advertisement
Advertisement
Playa del Carmen – Riviera Maya Tourism Faces Increasing Accommodation Competition
Playa del Carmen continues to attract visitors through its beaches, restaurants, shopping areas, nightlife and convenient access to attractions throughout the Riviera Maya.
The destination recorded average hotel occupancy of 71.27% during January–July 2026, compared with 75.76% during the corresponding period in 2025.
The reduction of 4.49 percentage points indicates softer accommodation demand relative to available room capacity.
Playa del Carmen occupies an important position between Cancún and Tulum, allowing visitors to explore several destinations during a single holiday.
Its hotel market includes all-inclusive resorts, beachfront accommodation, boutique properties and urban hotels near the city’s commercial and entertainment districts.
However, competition has increased as travellers gain access to a wider range of accommodation options across Quintana Roo.
Advertisement
Advertisement
The broader Riviera Maya region recorded occupancy of approximately 70.71% during January–July 2026, down from 75.34% in 2025.
This suggests that the decline was not confined to Playa del Carmen but extended across parts of the surrounding tourism corridor.
For hotel operators, maintaining occupancy may depend on differentiating accommodation products, improving guest experiences and attracting visitors outside traditional peak seasons.
The destination’s established tourism infrastructure remains an advantage, but the figures indicate that stronger competition is influencing room utilisation.
Costa Mujeres – High Occupancy Continues Despite a Noticeable Annual Decline
Costa Mujeres remains one of the stronger-performing accommodation markets in Quintana Roo, supported by modern beachfront resorts and an extensive all-inclusive hospitality offering.
The destination recorded average hotel occupancy of 75.64% during January–July 2026, compared with 81.76% during the corresponding period of 2025.
Advertisement
Advertisement
Although the decline of 6.12 percentage points was substantial, Costa Mujeres maintained one of the higher occupancy rates among the Caribbean destinations examined.
Its accommodation sector is characterised by large resort properties, premium facilities and integrated holiday experiences.
Many visitors choose the area for its beaches, resort amenities and proximity to Cancún International Airport.
The destination’s performance illustrates the importance of distinguishing between occupancy levels and occupancy growth.
Costa Mujeres recorded relatively high room utilisation, but its annual decline indicates that the market was weaker than in 2025.
For hotel operators, maintaining strong demand may require competitive holiday packages, service differentiation and improved international market reach.
Advertisement
Advertisement
Isla Mujeres – Hotel Occupancy Growth Stands Out Across Quintana Roo
Isla Mujeres delivered one of the most encouraging occupancy performances among the destinations examined.
The island recorded average hotel occupancy of 72.57% during January–July 2026, compared with 68.57% during the same period in 2025.
The increase of four percentage points contrasts with the declines recorded across several larger resort markets in Quintana Roo.
Isla Mujeres attracts visitors through its beaches, coastal landscapes, snorkelling opportunities, restaurants and relaxed island atmosphere.
Its accommodation sector includes boutique hotels, beachfront properties and smaller hospitality establishments.
The island’s growth suggests that demand remained comparatively strong relative to available hotel capacity during the reporting period.
Advertisement
Advertisement
However, occupancy growth does not automatically establish an increase in total visitor arrivals or hotel revenue.
Changes in accommodation supply can also influence occupancy percentages.
For Isla Mujeres, the challenge will be maintaining tourism growth while protecting the island’s environment and managing transport, water and waste infrastructure.
The positive occupancy performance demonstrates that smaller destinations can achieve growth even when larger neighbouring resort markets experience softer conditions.
Cozumel – Island Tourism Maintains Demand Despite a Modest Occupancy Decline
Cozumel continues to benefit from its reputation for diving, marine experiences, beaches and cruise tourism.
The island recorded average hotel occupancy of 69.44% during January–July 2026, compared with 71.13% during the corresponding period in 2025.
Advertisement
Advertisement
The reduction of 1.69 percentage points was relatively modest compared with declines in Tulum, Costa Mujeres and parts of the Riviera Maya.
Cozumel’s tourism economy differs from mainland resort destinations because cruise passengers, diving visitors and overnight hotel guests contribute to different segments of demand.
Cruise arrivals can support restaurants, attractions and local businesses without necessarily generating hotel room-nights.
This distinction is important when interpreting occupancy statistics.
The island’s hotel sector depends on overnight travellers, while its wider visitor economy also benefits from short-duration cruise visits.
For Cozumel, maintaining occupancy could involve promoting longer stays, diving holidays, marine conservation experiences and cultural attractions.
Advertisement
Advertisement
The relatively limited annual decline suggests that the destination retained a substantial level of hotel demand, although the available data does not establish whether tourism revenue increased.
Mexico City – International Events and New Hotel Supply Shape Urban Tourism
Mexico City represents a different tourism market from Mexico’s coastal resort destinations.
The capital attracts visitors through cultural heritage, museums, gastronomy, business events, conferences, entertainment and major international sporting occasions.
Its hotel sector includes luxury properties, international business hotels, boutique accommodation and independently operated establishments.
The supplied industry research references an occupancy figure of approximately 50.8% across urban accommodation markets, alongside the addition of more than 2,000 hotel rooms.
However, the precise reporting period and geographic coverage of that occupancy figure require confirmation before it can be treated as an official Mexico City average.
Advertisement
Advertisement
The city’s accommodation industry has also been influenced by the 2026 FIFA World Cup, which created opportunities for hotels, restaurants and tourism businesses.
Major sporting events can generate substantial demand during selected dates, particularly near stadiums, transport hubs and entertainment districts.
However, temporary occupancy increases during international events should not be confused with sustained annual hotel performance.
Additional accommodation supply can also influence reported occupancy rates.
Even when the number of occupied rooms increases, the overall occupancy percentage may decline if available room capacity expands more quickly.
For Mexico City, the long-term opportunity lies in converting international event exposure into repeat tourism, business travel and stronger year-round demand.
Advertisement
Advertisement
Mazatlán – Domestic Holiday Travel Supports Pacific Coast Tourism
Mazatlán remains an important Pacific coast destination, particularly for domestic travellers seeking beach holidays, family experiences and regional cultural attractions.
The city’s tourism economy benefits from its extensive Malecón, historic centre, beaches, restaurants and seasonal events.
The supplied research references an expected 1.44 million visitors during a peak summer holiday period, although this figure should be treated as a projection until the reporting period and official methodology are confirmed.
Unlike destinations that depend heavily on international air travel, Mazatlán benefits significantly from domestic road tourism and regional aviation connections.
This creates opportunities during national holidays and school vacation periods.
However, hotel occupancy can fluctuate considerably between peak travel dates and quieter weeks.
Advertisement
Advertisement
For Mazatlán’s hospitality sector, the challenge is to attract visitors throughout the year rather than relying primarily on concentrated holiday demand.
Improved destination promotion, cultural events, gastronomy and regional connectivity could support more consistent accommodation demand.
Without a verified comparable 2026 occupancy series, Mazatlán cannot be directly ranked against Cancún, Los Cabos or Tulum.
Why Hotel Occupancy Is Falling in Some Mexican Destinations Despite Tourism Growth
Mexico’s hotel occupancy figures reveal an important distinction between visitor arrivals and accommodation performance.
The country welcomed approximately 28.9 million international tourists during January–July 2026, representing growth of 4.5% compared with the corresponding period of 2025.
However, several leading resort destinations recorded lower occupancy rates.
Advertisement
Advertisement
This difference can arise from multiple factors, including hotel supply expansion, changing airline capacity, seasonal demand and variations in accommodation preferences.
Hotel Supply Expansion Changes Occupancy Calculations
Hotel occupancy measures the proportion of available rooms that are occupied.
A destination can welcome more visitors while recording lower occupancy if the number of available hotel rooms increases more quickly than demand.
For example, a destination with 10,000 rooms and 7,500 occupied rooms records occupancy of 75%.
If available supply increases to 11,000 rooms while occupied rooms remain unchanged, occupancy falls to approximately 68.2%.
This illustrates why occupancy rates should be examined alongside room supply and actual room-night demand.
Advertisement
Advertisement
Airline Connectivity Influences Coastal Resort Markets
International aviation remains important for Cancún, Los Cabos, Puerto Vallarta and other major resort destinations.
Changes in airline schedules, available seats and travel costs can influence hotel bookings.
However, airport passenger traffic and hotel occupancy measure different aspects of tourism activity.
A decline in airport movements does not automatically produce an equivalent decline in hotel occupancy.
Seasonal Demand Creates Sharp Differences Between Destinations
Mexico’s tourism markets experience different seasonal patterns.
Caribbean destinations attract international beach travellers throughout much of the year, while Pacific coast resorts often experience strong demand during winter and holiday periods.
Advertisement
Advertisement
Domestic tourism also contributes to peaks around school holidays and national celebrations.
As a result, occupancy recorded during a major holiday may be considerably higher than the average across an entire quarter.
Accommodation Categories Perform Differently Across Mexico’s Tourism Markets
Tulum demonstrates how independent boutique hotels and large all-inclusive resorts can experience significantly different occupancy levels, even within the same destination.
While some smaller beachfront properties reported occupancy as low as 15–20% during selected periods in 2026, larger all-inclusive resorts maintained considerably stronger demand. Hotel association figures for part of April indicated occupancy of approximately 77.6% among all-inclusive properties, compared with around 45% for European-plan hotels.
This difference reflects the contrasting business models operating within Mexico’s hospitality industry. All-inclusive resorts generally offer accommodation, dining, entertainment and recreational facilities within a single package. Such arrangements can appeal to travellers seeking predictable holiday costs and convenience.
Boutique hotels, meanwhile, often compete through distinctive architecture, personalised service, wellness experiences and exclusive locations. Their performance may be more sensitive to pricing, distribution channels and changes in visitor preferences.
Advertisement
Advertisement
For independent hotel operators, improving occupancy may require more flexible pricing, stronger online visibility, partnerships with travel agencies and differentiated guest experiences.
However, lower occupancy does not necessarily indicate weaker profitability. Smaller luxury properties may generate higher revenue per occupied room, making average daily rates and operating margins equally important measures of performance.
The contrasting results in Tulum highlight why Mexico’s hotel industry should be assessed by accommodation category as well as destination.
Environmental Challenges Add Pressure to Mexico’s Coastal Hotel Industry
Environmental conditions are becoming an increasingly important consideration for Mexico’s beach tourism destinations, particularly those along the Caribbean coastline.
Cancún, Playa del Carmen, Tulum and other destinations in Quintana Roo face recurring challenges associated with sargassum seaweed, coastal erosion, water management and seasonal weather conditions.
Sargassum accumulation can affect beach access, coastal appearance and maintenance costs for beachfront hotels. Resorts may need to invest in additional cleaning operations, monitoring systems and beach management infrastructure to maintain guest experiences.
Advertisement
Advertisement
For destinations where beaches represent a major attraction, environmental management is closely connected to long-term tourism competitiveness.
However, it would be inaccurate to attribute the reported occupancy declines directly to sargassum without destination-specific evidence establishing that relationship.
Airline capacity, accommodation prices, room supply and seasonal demand may also influence hotel performance.
Climate adaptation is particularly relevant to Mexico’s coastal tourism economy because hotels, restaurants, transport operators and local communities depend on reliable infrastructure and healthy natural environments.
Investment in wastewater treatment, coastal protection, sustainable construction and efficient resource management could help destinations maintain their appeal while reducing environmental pressures.
For hotel operators, environmental resilience is increasingly part of long-term business planning rather than simply a destination management concern.
Advertisement
Advertisement
Mexico’s Tourism Investment Outlook Depends on Occupancy, Room Rates and Revenue Growth
Mexico remains an important market for hospitality investment, supported by internationally recognised destinations, extensive resort infrastructure and demand from domestic and overseas travellers.
However, the contrasting occupancy figures across Cancún, Tulum, Los Cabos and Puerto Vallarta demonstrate why investors must examine more than visitor arrival numbers.
Three performance indicators are particularly important when assessing hotel investment opportunities.
| Hotel performance indicator | What it measures | Why it matters |
|---|---|---|
| Occupancy rate | Percentage of available rooms occupied | Indicates room utilisation and demand relative to supply |
| Average daily rate (ADR) | Average revenue earned per occupied room | Measures hotel pricing performance |
| Revenue per available room (RevPAR) | Room revenue divided by available rooms | Combines occupancy and room pricing into a broader revenue indicator |
| Available room supply | Number of rooms available for sale | Helps explain changes in occupancy |
| Length of stay | Average duration of guest visits | Influences room-night demand and visitor spending |
| Seasonality | Changes in demand throughout the year | Helps assess revenue stability and staffing requirements |
A destination reporting high occupancy may still face profitability challenges if hotels rely heavily on discounted rates or experience rising operating costs.
Conversely, a luxury resort market can generate substantial room revenue with comparatively lower occupancy if average daily rates remain strong.
This distinction is especially relevant to Los Cabos, where premium accommodation forms an important part of the hospitality market.
Advertisement
Advertisement
For Cancún, the challenge involves maintaining room utilisation while responding to additional accommodation supply and changing international demand.
Tulum requires a more detailed assessment of performance differences between boutique properties and larger resorts.
Puerto Vallarta’s figures highlight the importance of consistent occupancy beyond peak holiday periods.
Hotel investors should therefore consider destination-level revenue performance, operating expenses, infrastructure capacity and long-term demand before interpreting occupancy changes as evidence of either expansion opportunities or market weakness.
Regional Tourism Diversification Could Strengthen Mexico’s Hospitality Economy
Mexico’s tourism development is not limited to its most established beach destinations.
Cultural cities, mountain regions, heritage towns, nature-based attractions and emerging coastal markets provide opportunities to distribute visitor spending more widely.
Advertisement
Advertisement
Mexico City demonstrates the potential of urban tourism through museums, gastronomy, business events and major international attractions.
Mazatlán benefits from domestic road travel and seasonal family holidays, while smaller destinations across the country offer opportunities for boutique accommodation, cultural tourism and regional experiences.
Diversifying tourism activity can help reduce dependence on individual markets and peak travel periods.
For example, destinations with strong summer demand may benefit from developing conferences, wellness tourism and cultural events during quieter months.
Coastal destinations can also encourage visitors to explore inland attractions, local communities and regional experiences.
However, diversification requires investment in transport, accommodation standards, workforce training and visitor infrastructure.
Advertisement
Advertisement
The objective should not simply be to attract more visitors to additional destinations. Tourism development must also consider environmental capacity, local economic benefits and the quality of the visitor experience.
For Mexico, a broader tourism offering could strengthen the resilience of its hospitality industry while supporting employment and business opportunities beyond established resort corridors.
What Hotel Operators Should Watch During the Remainder of 2026
The available figures indicate that Mexico’s hotel industry is entering the final months of 2026 with different levels of demand across its major tourism markets.
For Cancún and the Riviera Maya, the principal questions concern international air connectivity, accommodation supply and the ability to maintain occupancy during seasonal changes.
In Tulum, operators will be watching whether boutique hotels can improve room utilisation and narrow the gap with larger all-inclusive resorts.
Los Cabos will remain an important market for monitoring premium accommodation demand, particularly through average daily rates and revenue per available room.
Advertisement
Advertisement
Puerto Vallarta’s performance will depend partly on its ability to convert strong holiday peaks into more consistent demand across surrounding weeks.
For Mexico City, the longer-term focus will be on sustaining international interest beyond major events and ensuring that new accommodation supply is supported by demand.
Mazatlán’s tourism businesses will continue to depend on domestic travel patterns, regional accessibility and seasonal visitor activity.
Across all these destinations, comparable monthly occupancy figures will be essential for assessing whether hotel performance is improving.
The most meaningful evidence of sustained growth would be a combination of stronger room-night demand, stable or improving occupancy, healthy room rates and consistent visitor spending.
Conclusion – Cancún, Tulum, Los Cabos and Other Destinations Shape Mexico’s Tourism Future
Mexico’s tourism industry continues to demonstrate substantial demand in 2026, with Cancún, Los Cabos, Tulum, Puerto Vallarta and other destinations supporting the country’s hospitality economy. However, hotel occupancy figures reveal contrasting regional performances, with several established resorts experiencing softer annual comparisons despite maintaining significant room utilisation.
Advertisement
Advertisement
Cancún remains an important Caribbean tourism hub, while Los Cabos benefits from its established luxury market. Tulum faces uneven demand across accommodation categories, and Puerto Vallarta must balance strong holiday peaks with weaker quarterly averages.
For Mexico’s tourism industry, long-term competitiveness will depend on maintaining accommodation quality, improving connectivity, managing environmental challenges and generating sustainable revenue throughout the year. The most successful hospitality strategies will be those that balance visitor demand with room supply, operational efficiency and the economic needs of local communities.
Cancún goes hand in hand with Tulum, Los Cabos and others in leading Mexican tourism through high hotel occupancy in 2026, driven by luxury resorts, strong international demand, beachfront attractions and extensive hospitality infrastructure.
In conclusion, Cancún goes hand in hand with Tulum, Los Cabos and others in leading Mexican tourism through high hotel occupancy in 2026, supported by luxury resorts, international demand and coastal attractions. Despite softer occupancy in some destinations, strong tourism infrastructure, diverse accommodation and sustained visitor interest continue to support Mexico’s hospitality industry.
Advertisement
