Spain Sees Castellón Hotel Occupancy Growth as Overseas Guests Now Make Up More of the September Market

Updated
Published
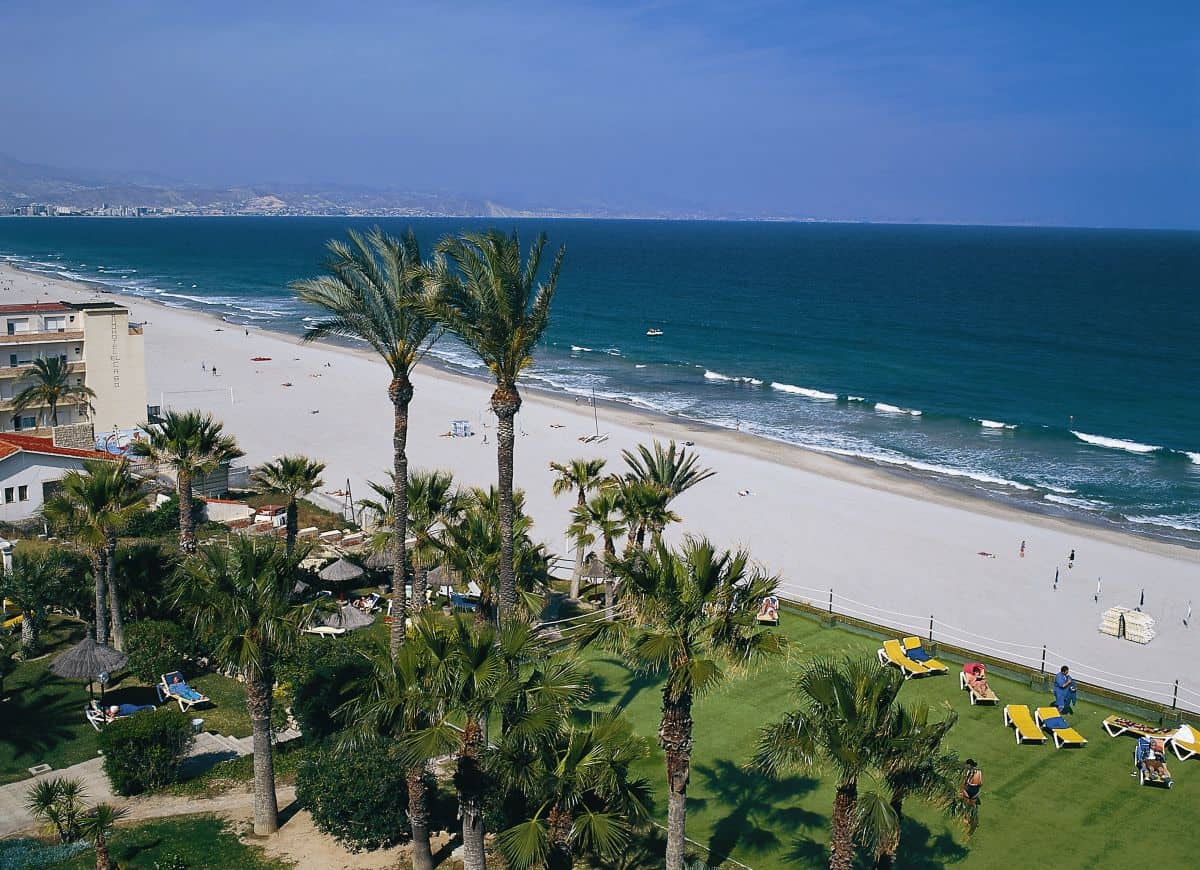
Spain’s Castellón province recorded Hotel Occupancy of 83.1% in September 2026, compared with 79.8% a year earlier, according to a published member hotel survey. International guests increased their share, while confirmed reservations represented 71.4% occupancy for early October when reported. For visitors and accommodation businesses, the results show stronger activity beyond summer, although they do not establish room availability or prices for individual trips. The provincial figures are primary industry evidence; separate government statistics provide the wider tourism and economic context.
What the September Evidence Establishes
Castellón Hotel Occupancy Growth is principally an accommodation story, supported by a changing customer mix. The province recorded the largest annual occupancy increase among the regional destinations surveyed, although it remained below the Valencian Community’s 89.4% average. The table assigns editorial weight to the verified subjects covered here. Its percentages are an editorial assessment totalling 100%, not official tourism statistics, market shares or estimates of economic impact. Castellón’s monthly rate remained 6.3 percentage points below the regional average.
| News Component | Share of Story | Officially Verified Finding | Relevance to Travellers | Official Source |
| Hotel performance | 55% | September occupancy reached 83.1%, against 79.8% in 2025 | Stronger accommodation activity | Published industry survey |
| International demand | 25% | September international share rose to 25.7%, from 20% | A broader customer mix | Published industry survey |
| Economic conditions | 15% | September’s advance national inflation estimate was 4.9% | Cost context, not local hotel pricing | Government price statistics |
| Transport activity | 5% | September airport passengers reached 45,900, up 15.8% annually | Separate evidence of travel activity | Official airport release |
The evidence establishes stronger use of surveyed hotel capacity and a larger international customer share. It does not establish higher provincial tourism expenditure, additional jobs or increased hotel profits. The monthly findings also cannot represent every apartment, campsite or visitor staying with relatives. For travellers, the practical significance is continued accommodation activity after peak summer, rather than a guaranteed price advantage, shortage of rooms or change to entry requirements. Member establishments supply the underlying information through regular surveys, making this a measure of participating businesses rather than a census of all provincial tourism.
Hotel Occupancy and the Changing International Mix
The international figures are central to understanding Castellón Hotel Occupancy Growth. Domestic customers represented 74.3% of September’s total, compared with 80% a year earlier. International participation therefore increased from 20% to 25.7%, a rise of 5.7 percentage points. During the second fortnight, the overseas share reached 30.7%, leaving domestic customers at 69.3%. The full month consequently attracted slightly more than one international customer in four; the figure above three in ten applies only to its second half. The monthly international total is calculated from domestic shares.
Advertisement
Advertisement
Across September, the UK accounted for 4.7% of all surveyed customers, France 4%, Portugal 2.5%, the Czech Republic 1.8% and Slovakia 1.7%. British and French shares reached 6.7% and 6% during the second fortnight. Occupancy during that fortnight stood at 79.6%, against 78.8% a year earlier. Monthly three-star occupancy rose from 77% to 84.7%, while four-star properties increased from 81.9% to 84%. These represent gains of 7.7 and 2.1 percentage points, respectively; the survey does not establish why the categories performed differently. British and French monthly customer shares had each stood at 3.2% one year earlier.
Understanding the Context Behind the Development
Demand beyond the summer peak
The immediate news trigger is the completed September survey, rather than a new policy or transport announcement. No definitive cause of the improvement has been established. The wider regional survey recorded annual occupancy gains each month from February through September 2026. Separately, government data recorded over 48.7 million hotel overnight stays nationally in August, up 1.4%. Resident overnight stays fell 1.1%, while non-resident stays increased 2.8%. These different periods and measures provide background and should not be treated as confirmation of Castellón’s September result. An overnight stay means one guest spending one night, whereas occupancy measures the use of available capacity.
Advertisement
Advertisement
The difference between revenue and profit
The commercial value of Castellón Hotel Occupancy Growth depends on costs as well as demand. The published industry assessment identifies staffing, food, utilities and taxation as pressures on hotel margins. Nationally, average revenue per occupied room reached €166.90 in August, up 7.3% annually. Separately, September’s preliminary consumer inflation estimate was 4.9%, against 4.3% in August. Neither measure establishes local hotel profits. Fuller properties can create opportunities for restaurants and visitor services, but additional spending or employment remains an unmeasured potential consequence. Revenue records money received before expenses; profit depends on what remains after those expenses have been paid.
What Travellers Should Check Before Booking
The confirmed increase concerns accommodation use, rather than a disruption requiring visitors to change plans. Airport traffic also rose: 295,484 passengers travelled through the provincial airport during January–September, up 13%. The September total cannot identify which passengers stayed in surveyed hotels, so it does not prove that aviation caused the hotel improvement. Visitors should instead use current transport information and property availability to assess the practical arrangements for their own journey.
- Check transfers: The airport bus connects with Castellón’s bus station, beside the railway station; the published single fare is €12.
- Confirm route coverage: The Valencia connection lists a €26 single fare, with availability dependent on the flight route.
- Review rail access: The airport–Torreblanca station shuttle lists a €1.65 standard single fare; schedules vary by day.
- Compare booking terms: Check room availability, included services and cancellation conditions for your exact dates.
Published transfer information helps visitors plan the journey beyond the terminal, but they should check the current timetable for their travel date. A provincial occupancy average cannot establish whether a particular hotel has suitable rooms or accessible facilities. The hotel release announces no passport or visa change. Travellers should continue checking nationality-specific entry requirements through the appropriate official channels, while monitoring their accommodation and transfer arrangements. Compare accommodation and transport costs together before deciding whether an offer meets your budget and itinerary.
The October Dates That Matter
The chronology separates completed travel from forward reservations. September 2025 provides the annual comparison; September 2026 supplies the latest completed hotel results. The airport published its September passenger announcement on 4 October 2026. The hotel survey’s early October position covers confirmed bookings for 1–15 October, rather than completed stays or the whole month. Its 71.4% figure can change through additional bookings, cancellations and changes in available capacity. Comparing that forward position directly with September’s completed monthly result would therefore combine two different types of evidence.
The next evidence for assessing Castellón Hotel Occupancy Growth will include September’s government hotel report, scheduled for 23 October 2026. Before that, final national September consumer price figures are scheduled for 14 October. These are confirmed publication dates, not promises of stronger tourism results. The government hotel figures may differ from the industry survey because their coverage and measurement methods are not identical. Neither release predetermines how the rest of autumn will perform.
A Stronger September With Autumn Still to Be Measured
Castellón’s September results show stronger Hotel Occupancy and a larger international customer share, while domestic visitors remain the main market. The improvement supports a positive assessment of hotel activity beyond summer, but does not prove higher profits or wider economic gains. Travellers should judge their plans through current accommodation availability, transfer schedules and official entry guidance. Early October reservations provide a starting point rather than a final result. The forthcoming government releases will add evidence on prices and hotel activity. Following those updates will help distinguish sustained autumn demand from a strong September within a season that is still unfolding.
Advertisement